United States Biodiesel Market Size, Industry Trends, Share, Growth and Report 2026-2034
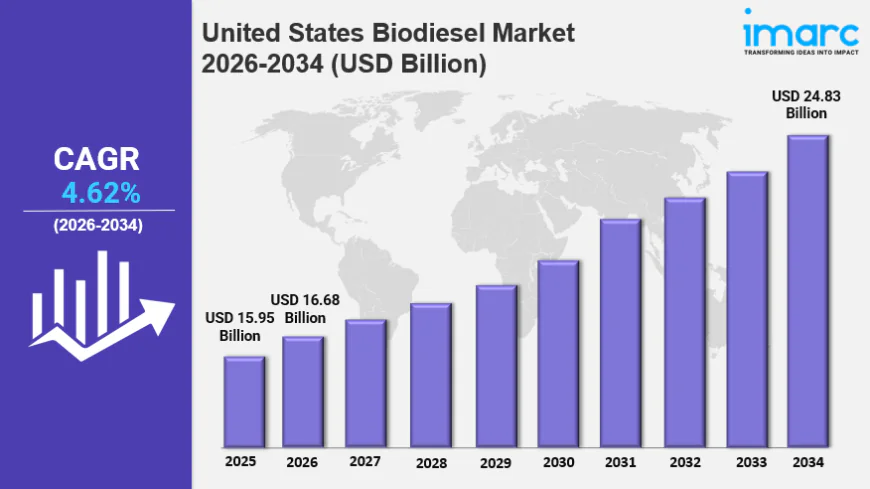
The United States biodiesel market size increased from USD 15.95 Billion in 2025 to USD 16.68 Billion in 2026 and is projected to reach USD 24.83 Billion by 2034, exhibiting a CAGR of 4.62% during 2026–2034
 marketinsights
IMARC Group has recently released a report titled "United States Biodiesel Market Size, Share, Trends and Forecast by Feedstock, Application, Type, Production Technology, and Region, 2026-2034", providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.
United States Biodiesel Market Size and Forecast 2026–2034
The United States biodiesel market size increased from USD 15.95 Billion in 2025 to USD 16.68 Billion in 2026 and is projected to reach USD 24.83 Billion by 2034, exhibiting a CAGR of 4.62% during 2026–2034. Robust support from the federal Renewable Fuel Standard (RFS), with the Environmental Protection Agency (EPA) proposing a biomass-based diesel volume of 5.61 Billion gallons for 2026, is the primary driver of expansion. Federal blending mandates, fleet decarbonization, and abundant domestic soybean oil are further expanding market share.
In 2026, the United States biodiesel market growth is being fueled by the Section 45Z clean fuel production credit, which took effect in January 2025 and was extended through 2029, expanding renewable diesel capacity, and state low-carbon fuel program incentives. The market expanded from USD 12.72 Billion in 2020 to USD 15.95 Billion in 2025 and is anchored at USD 19.98 Billion in 2030, with the forecast to 2034 reinforced by fleet adoption of B5 to B20 blends. Vegetable oils lead the feedstock segment at 47.6%, fuel dominates the application segment at 68.3%, and the West commands a 34.2% market share in 2025.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020–2025
- Forecast Period: 2026–2034
- Market Size (2025): USD 15.95 Billion
- Market Size (2026): USD 16.68 Billion
- Projected Size (2034): USD 24.83 Billion
- Growth Rate: CAGR of 4.62%
- Leading Feedstock: Vegetable Oils (47.6%, 2025)
- Leading Application: Fuel (68.3%, 2025)
- Largest Region: West (34.2%, 2025)
Explore Opportunities in the United States Biodiesel Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-biodiesel-market/requestsample
United States Biodiesel Market Growth: Key Trends and Market Insights
The United States biodiesel market growth is supported by a shift toward lower-carbon-intensity feedstocks. Producers are reformulating feedstock slates to favor used cooking oil, distillers corn oil, and tallow over virgin vegetable oils, capturing higher Section 45Z and Low Carbon Fuel Standard (LCFS) credit values, which is reshaping procurement networks and elevating renderer partners. New biodiesel and renewable diesel projects are also co-locating with expanded soybean crushing facilities across Iowa, North Dakota, and the Mid-South, reducing logistics costs and improving feedstock visibility.
Key United States biodiesel market trends include the convergence with renewable diesel and sustainable aviation fuel (SAF) production, as multi-product biorefineries that flex between FAME biodiesel, renewable diesel, and SAF gain traction and reduce exposure to single-product volatility. State low-carbon fuel programs are also expanding: California, Oregon, Washington, and New Mexico operate LCFS programs, and in April 2026 New Mexico began implementing regulations to reduce road fuel carbon intensity by 20% in this decade under its Clean Transportation Fuel Program.
The United States biodiesel market growth is also being supported by the integration of biodiesel with fleet sustainability reporting. Large logistics operators and municipal fleets are embedding B20 to B100 biodiesel into ESG reporting and scope-1 reduction commitments and signing multi-year supply agreements, strengthening long-term offtake visibility. According to the Energy Information Administration, biodiesel and renewable diesel together met about 9% of on-road diesel demand in 2024, and soybean oil production in the United States reached 13.76 Million Metric Tons in 2025/2026.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=2722&flag=C
United States Biodiesel Market Segmentation Analysis
The United States biodiesel market is segmented by feedstock, application, type, production technology, and region, offering a comprehensive view of demand patterns, production pathways, and regional dynamics across the country.
Breakup by Feedstock
- Vegetable Oils: Command a 47.6% majority share in 2025, anchored by United States soybean oil supply and soybean processing expansions across the Mid-South, Plains, and Eastern Corn Belt.
- Animal Fats: Hold a 32.4% share in 2025, capturing beef tallow, choice white grease, poultry fat, and yellow grease, which earn lower carbon-intensity scores and preferential treatment from refiners.
- Others: Account for the remaining 20.0% share in 2025, including other waste and recycled oil feedstocks.
Breakup by Application
- Fuel: Dominates with a 68.3% share in 2025, reflecting non-discretionary blending into the on-road diesel pool to meet RFS biomass-based diesel obligations and strong adoption across trucking and municipal fleets.
- Power Generation: Holds an 18.7% share in 2025, covering standby diesel gensets, data center backup, microgrids, and remote off-grid power.
- Others: Includes marine, rail, agricultural, and home-heating applications, such as Bioheat in the Northeast.
Breakup by Type
- B100: Pure biodiesel, whose use is limited in northern winter conditions because of higher cloud and pour points than petroleum diesel.
- B20: The leading blend type, widely adopted by fleets to reduce scope-1 emissions without engine modifications.
- B10: A mid-level blend used by fleets and fuel marketers to meet blending requirements.
- B5: A low-level blend suited to broad on-road diesel blending and compliance.
Breakup by Production Technology
- Conventional Alcohol Trans-Esterification: The leading production technology, combining feedstock oils with methanol and a catalyst to yield fatty acid methyl esters and glycerin.
- Pyrolysis: Thermal conversion pathway used to produce biofuel from feedstocks without conventional trans-esterification.
- Hydro Heating: Hydrotreatment-based pathway associated with hydrocarbon drop-in fuels.
Breakup by Region
- West: Leads with a 34.2% share in 2025, driven by premium credit pricing under California LCFS, active programs in Oregon and Washington, mature distribution networks, and strong fleet decarbonization commitments.
- Midwest: Holds a 27.8% share in 2025 and is the highest-growth region through 2034, supported by proximity to soybean crushing and animal-fat rendering capacity and dense biorefinery clusters in Iowa, Minnesota, Missouri, and Illinois.
- South: Accounts for a 22.6% share in 2025, supported by expanding soybean processing investments, growing logistics and trucking demand, port-based export optionality, and rising fleet decarbonization commitments.
- Northeast: Represents a 15.4% share in 2025, supported by established Bioheat home-heating-oil mandates, dense urban municipal fleet adoption, and state-level low-carbon transportation fuel program development.
Key Challenges and Growth Opportunities in the United States Biodiesel Market
The United States biodiesel market faces several challenges that could affect its growth, including high feedstock cost volatility, since soybean oil and animal fat prices are the dominant cost component and sharp swings can compress margins, and competition from renewable diesel for the same fats and oils feedstocks. The expiration of the legacy USD 1 per gallon blender credit at the end of 2024 paused several projects and curtailed early-2025 production, while RIN price volatility, small refinery exemption decisions, and cold-weather performance constraints add further uncertainty and operational complexity.
Despite these challenges, the market offers significant growth opportunities driven by waste and used cooking oil pathways that earn lower carbon-intensity scores and premium pricing, and by SAF co-production at co-located or convertible facilities. Bioheat home heating oil, off-road agriculture and construction equipment, marine bunker fuel, and rail switching represent under-penetrated growth pools. Companies investing in low-carbon feedstocks, vertical integration, and multi-product biorefineries will be well positioned to strengthen their competitive advantage through 2034.
Competitive Landscape
The United States biodiesel market is moderately fragmented, with a handful of large vertically integrated producers commanding national scale alongside numerous regional and specialty producers. Feedstock-procurement depth, biorefinery scale, and LCFS pathway approvals form the primary competitive advantages, and the top five producers are estimated to hold approximately 50–60% of operating capacity in 2025. The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the space.
Key players include Chevron Corporation, ADM, Louis Dreyfus Company, Cargill, Incorporated, and Western Iowa Energy, LLC, among others. Barriers to entry include EPA RFS producer registration, pathway approvals under the California LCFS, and access to long-term feedstock contracts, which favor well-capitalized incumbents with vertically integrated supply, while consolidation is being driven by capital intensity and the shift to renewable diesel and SAF co-production.
Latest News and Developments
- April 2026: New Mexico started implementing regulations under its Clean Transportation Fuel Program to reduce road fuel carbon intensity by 20% in this decade, becoming the first United States low-carbon fuel initiative beyond the West Coast.
- August 2025: Chevron confirmed that its Geismar, Louisiana renewable fuels plant began production following an expansion that increased capacity from 7,000 to 22,000 barrels per day, lifting annual renewable diesel output at the site from approximately 90 Million gallons to 340 Million gallons.
- June 2025: Louis Dreyfus Company announced plans to reopen its Burns Harbor grain export facility in Portage, Indiana, supporting feedstock and origination flows for its Claypool, Indiana biodiesel plant.
- 2023: Cargill completed its acquisition of Owensboro Grain Company, expanding its oilseed crushing footprint along the Ohio River and strengthening feedstock supply for biodiesel and renewable diesel customers.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: [email protected]
United States: +1-201-971-6302