Medical Oxygen Concentrators Market: Next-Generation Devices Reshape Respiratory Care
Portable systems are designed to provide greater mobility and convenience, while stationary systems are commonly used for continuous oxygen therapy in homes and healthcare facilities.
 Eknath Girhepunje
The global medical oxygen concentrators market is expanding as healthcare providers increasingly adopt oxygen therapy solutions for patients requiring supplemental oxygen. Medical oxygen concentrators extract oxygen from ambient air and deliver concentrated oxygen without the need for continuous oxygen-cylinder replacement. Rising demand for home-based healthcare, increasing respiratory disorders, and improvements in oxygen delivery technologies are supporting market growth.
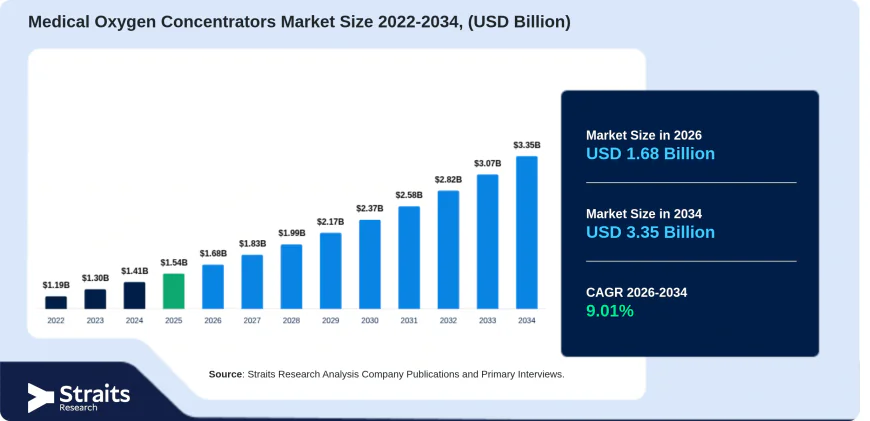
The global medical oxygen concentrators market size was valued at USD 1.54 billion in 2025 and is projected to grow from USD 1.68 billion in 2026 to USD 3.35 billion by 2034, registering a CAGR of 9.01% during the forecast period from 2026 to 2034. North America dominated the medical oxygen concentrators market with a market share of 38.5% in 2025, supported by advanced healthcare infrastructure, growing adoption of home oxygen therapy, and increasing demand for respiratory care equipment.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/medical-oxygen-concentrators-market
Market Drivers
Rising prevalence of respiratory disorders
The increasing prevalence of respiratory conditions is driving demand for reliable oxygen therapy equipment across hospitals, clinics, and home-care settings. Patients with chronic respiratory conditions may require supplemental oxygen for extended periods, increasing the need for convenient oxygen delivery systems. Medical oxygen concentrators provide a continuous oxygen supply without requiring frequent cylinder replacement, supporting their adoption.
Growing adoption of home healthcare
The shift toward home-based healthcare is creating new demand for compact and easy-to-use oxygen concentrators. Healthcare providers and patients increasingly prefer treatment solutions that allow eligible individuals to receive oxygen therapy outside hospitals. Portable and home-use concentrators can improve convenience while reducing the logistical challenges associated with transporting and storing oxygen cylinders.
Technological advancements in oxygen concentrators
Manufacturers are developing lighter, quieter, and more energy-efficient oxygen concentrators to improve patient convenience and treatment flexibility. Portable systems with improved battery performance and oxygen delivery capabilities are becoming increasingly suitable for patients who need mobility during daily activities. These technological improvements are supporting broader adoption across home and clinical applications.
Market Challenges
High equipment costs
Advanced medical oxygen concentrators can involve significant acquisition costs, particularly portable and technologically sophisticated systems. The cost of equipment can be a barrier for patients and healthcare facilities with limited budgets. Maintenance, replacement components, and service requirements can further increase the overall cost of ownership.
Power dependency
Medical oxygen concentrators require a reliable electricity supply to operate continuously. Power interruptions can create challenges for patients who depend on oxygen therapy, particularly in areas with unstable electricity infrastructure. Backup oxygen sources and battery systems may be necessary, increasing costs and operational requirements.
Maintenance and technical requirements
Oxygen concentrators require regular maintenance to ensure reliable performance and appropriate oxygen concentration. Filters, compressors, tubing, and other components may require inspection or replacement over time. Limited access to trained technicians and after-sales services can create additional challenges in developing healthcare markets.
Market Segmentation
By product type
The medical oxygen concentrators market can be segmented into portable oxygen concentrators and stationary oxygen concentrators. Portable systems are designed to provide greater mobility and convenience, while stationary systems are commonly used for continuous oxygen therapy in homes and healthcare facilities.
By technology
Based on technology, the market includes continuous flow and pulse dose oxygen concentrators. Continuous-flow systems deliver oxygen at a consistent rate, while pulse-dose systems provide oxygen based on inhalation. Technology selection depends on patient requirements, mobility needs, and clinical recommendations.
By application
Applications include chronic obstructive pulmonary disease, asthma, respiratory distress syndrome, sleep apnea, and other respiratory conditions. Medical oxygen concentrators are used in hospitals and home-care environments to provide supplemental oxygen to patients who require respiratory support.
By end user
End users include hospitals, home healthcare providers, clinics, ambulatory care centers, and other healthcare facilities. Home healthcare is becoming increasingly important as healthcare systems encourage appropriate treatment outside traditional hospital environments. Hospitals and clinics continue to require concentrators for emergency care, respiratory therapy, and long-term patient management.
Regional Insights
North America
North America dominated the medical oxygen concentrators market with a 38.5% share in 2025. The region benefits from advanced healthcare infrastructure, high adoption of home healthcare services, and strong demand for respiratory care equipment. Growing preference for portable oxygen therapy and continued investments in healthcare technologies are supporting regional market development.
Europe
Europe represents a significant market for medical oxygen concentrators due to its established healthcare systems and increasing demand for respiratory care. Aging populations and the growing need for long-term disease management are supporting adoption of home oxygen therapy. Healthcare providers are also increasingly emphasizing convenient and cost-effective care delivery models.
Asia Pacific
Asia Pacific is witnessing increasing demand for medical oxygen concentrators as healthcare infrastructure expands and access to respiratory care improves. Rising awareness of oxygen therapy, increasing healthcare expenditure, and growing adoption of home-based medical equipment are supporting regional demand. Improvements in healthcare accessibility are also creating opportunities for manufacturers of portable and stationary systems.
Key Players Analysis
The major players in the medical oxygen concentrators market include Koninklijke Philips N.V., Invacare Corporation, Drive DeVilbiss Healthcare, Inogen, Inc., and Nidek Medical Products, Inc.
- Koninklijke Philips N.V.
- Invacare Corporation
- Drive DeVilbiss Healthcare
- Inogen, Inc.
- Nidek Medical Products, Inc.
Conclusion
The global medical oxygen concentrators market is expected to experience steady growth as respiratory care needs increase and healthcare delivery continues to shift toward home-based treatment. The market is projected to grow from USD 1.68 billion in 2026 to USD 3.35 billion by 2034 at a CAGR of 9.01%. Rising respiratory disorders, expanding home healthcare, technological advancements, and growing demand for convenient oxygen therapy solutions are expected to remain key factors supporting market growth during the forecast period from 2026 to 2034.
About Us
Straits Research is a leading market research and intelligence organization specializing in research, analytics, and advisory services. The company provides comprehensive market reports, industry insights, and strategic business intelligence across multiple industries, helping organizations identify growth opportunities and make informed business decisions.
Contact Us
Email: [email protected]
Tel: +1 646 905 0080 (U.S.)
Tel: +44 203 695 0070 (U.K.)