Group II and III Base Oil Market Forecast 2026–2034: Major Drivers and Challenges
The hydrocracking segment dominated the technology segment with a share of 42.6% in 2025, owing to its ability to improve base oil purity, enhance oxidation stability, and produce high-quality lubricants for modern engine applications.
 Eknath Girhepunje
The global group ii and iii base oil market is gaining attention as lubricant manufacturers focus on fuel efficiency, oxidation stability, and reliable performance across automotive and industrial applications. Group ii and iii base oils offer improved purity and performance characteristics, making them suitable for modern engine oils, transmission fluids, hydraulic systems, and other high-performance lubricants. Their role in supporting lubricant quality and equipment reliability is strengthening their importance across the global lubricants industry.
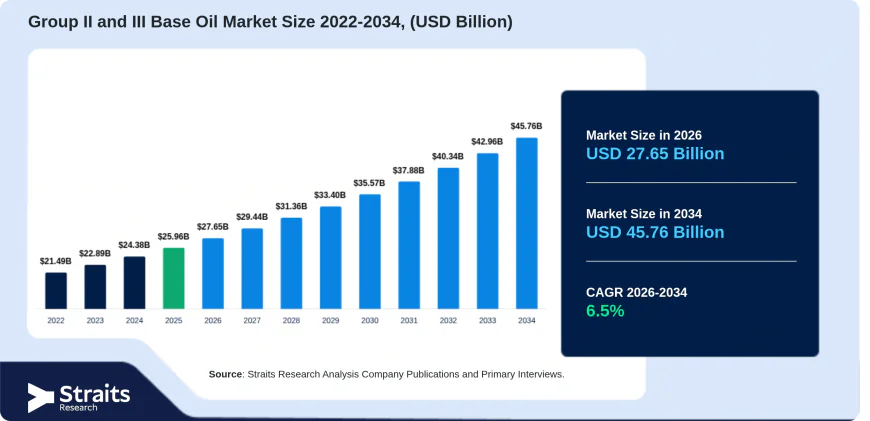
The global group ii and iii base oil market size was valued at USD 25.96 billion in 2025 and is projected to grow from USD 27.65 billion in 2026 to USD 45.76 billion by 2034, registering a CAGR of 6.5% during the forecast period from 2026 to 2034. North America dominated the market with a share of 34.2% in 2025, supported by its established refining infrastructure, lubricant manufacturing capabilities, and automotive and industrial applications.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/group-ii-and-iii-base-oil-market
Market Drivers
Demand for Oxidation-Stable Lubricants
The need for lubricants that maintain their properties under demanding operating conditions supports the adoption of group ii and iii base oils. Their refined composition and oxidation stability help control oil degradation and deposit formation when used in suitable formulations. Industrial gearboxes, hydraulic systems, and manufacturing equipment require lubricants that provide dependable protection during extended operating cycles. These performance requirements support the use of higher-quality base oils and encourage lubricant manufacturers to develop formulations for specialized industrial applications.
Automotive Lubricants and Engine Performance Requirements
The automotive industry remains a major application area for group ii and iii base oils because engine oils and transmission fluids require suitable viscosity characteristics, thermal stability, and oxidation resistance. Modern vehicle designs place emphasis on fuel efficiency and dependable engine performance, supporting the use of advanced lubricant formulations. Group ii and iii base oils provide lubricant manufacturers with suitable feedstocks for producing oils that meet specific performance requirements. These applications support the market's position within the automotive lubricants supply chain.
Use in Industrial Compressors and Turbine Systems
The need for reliable lubrication in compressors, turbines, and other industrial machinery supports the use of group ii and iii base oils. Equipment operating under elevated temperatures and demanding conditions requires lubricants that maintain viscosity and resist oxidation over appropriate service intervals. High-performance base oils help formulators develop products suited to these operating requirements. Industrial maintenance practices and the need for consistent equipment performance therefore support the use of advanced base stocks across several industrial applications.
Market Challenges
Feedstock Availability and Refinery Constraints
The availability of suitable petroleum feedstocks can constrain group ii and iii base oil production because advanced refining processes require consistent raw material quality. Supply disruptions and changes in refinery throughput can affect procurement schedules and production costs. Refiners may face additional pressure when competing for suitable feedstocks across different petroleum product categories. These constraints can affect operating margins and limit the ability of producers to maintain consistent supplies to lubricant manufacturers.
High Energy Consumption and Operating Costs
Advanced base oil production requires energy-intensive refining processes, including heating, separation, and hydroprocessing. Changes in fuel and electricity prices can increase operating expenses and reduce producer margins. Refinery operators may also need to invest in process optimization and equipment upgrades to maintain product quality and operational efficiency. These financial and technical requirements can create barriers for producers seeking to improve production capacity or enter higher-value base oil categories.
Supply Chain Dependence and Distribution Challenges
The group ii and iii base oil market depends on reliable transportation, storage, and distribution networks to connect refiners with lubricant manufacturers and industrial customers. Geographic differences in production capacity can create dependence on imported base stocks in certain markets. Shipping delays, logistics costs, and changes in supplier arrangements may affect product availability and delivery schedules. These challenges encourage producers and distributors to strengthen regional supply networks and establish long-term commercial agreements.
Market Segmentation
By Technology
The market is segmented into hydrocracking, hydrotreating, catalytic dewaxing, and other technologies. The hydrocracking segment dominated the technology segment with a share of 42.6% in 2025, owing to its ability to improve base oil purity, enhance oxidation stability, and produce high-quality lubricants for modern engine applications.
The catalytic dewaxing segment is expected to register a CAGR of 5.6% during the forecast period from 2026 to 2034, fueled by its ability to improve low-temperature performance and viscosity characteristics. These properties support the production of base oils used in high-performance lubricant formulations.
By Applications
The market is segmented into automotive oil, industrial oil, process oil, and other applications. The automotive oil segment dominated the applications segment with a share of 48.7% in 2025, supported by its extensive use in engine oils, transmission fluids, and other automotive lubricants that require reliable thermal and oxidation stability.
The industrial oil segment is expected to register a CAGR of 4.5% during the forecast period from 2026 to 2034, driven by the use of high-performance lubricants in industrial machinery, hydraulic systems, and manufacturing equipment. The need for equipment protection and dependable lubrication supports the use of advanced base stocks across industrial applications.
Regional Insights
North America
North America dominated the group ii and iii base oil market with a share of 34.2% in 2025. The region benefits from established petroleum refining operations, lubricant blending facilities, and demand from automotive and industrial customers. In the U.S., Vertex Energy announced a project in June 2026 to add 6,000 barrels per day of conventional group iii base oil production capacity at its Mobile, Alabama, refinery, with production targeted to begin in 2029. The project could strengthen domestic availability of premium base stocks for lubricant manufacturers and blenders.
Europe
The Europe group ii and iii base oil market is expected to register a CAGR of 5.7% during the forecast period from 2026 to 2034, showcasing the fastest-growing regional market. Investments in advanced refining and base oil production infrastructure are supporting the region's supply capabilities. In Germany, Shell Energy and Chemicals Park Rheinland completed a major construction milestone for a new base oil distillation unit at Wesseling in April 2026. The project is designed to produce approximately 300,000 tonnes of group iii base oils annually from 2028, potentially strengthening regional access to premium lubricant feedstocks.
Asia Pacific
The Asia Pacific group ii and iii base oil market is expected to register a CAGR of 5.2% during the forecast period from 2026 to 2034. The region's refining industry, automotive manufacturing base, and lubricant production activities support the use of advanced base stocks. In China, group iii base oil production exceeded 40,000 tonnes in June 2026, reaching a 15-month high, according to the report's cited industry data. This production level helped offset reduced imports from the Middle East and could improve feedstock availability for lubricant blenders.
Key Players Analysis
The major players in the group ii and iii base oil market include Exxon Mobil Corporation, Chevron Corporation, SK Enmove Co., Ltd., Shell plc, and Petroliam Nasional Berhad (PETRONAS).
- Exxon Mobil Corporation
- Chevron Corporation
- SK Enmove Co., Ltd.
- Shell plc
- Petroliam Nasional Berhad (PETRONAS)
Market participants compete on production capacity, base oil quality, refining technology, supply reliability, and distribution networks. Established producers focus on maintaining consistent product specifications and serving lubricant manufacturers across automotive and industrial applications. Specialized suppliers and regional distributors within the group ii and iii base oil market ecosystem also compete through tailored product grades, technical support, and flexible supply arrangements.
Conclusion
The group ii and iii base oil market is projected to reach USD 45.76 billion by 2034, supported by demand for advanced automotive lubricants, industrial oils, and base stocks with reliable performance characteristics. Hydrocracking remains a leading production technology, while automotive oil represents the dominant application segment. North America held the largest regional share in 2025, while investment in production infrastructure and regional supply capabilities is shaping the industry's outlook. Feedstock availability, energy costs, and distribution challenges remain important considerations for producers. Refining investments, technology development, and supply chain partnerships will continue to influence market competitiveness during the forecast period from 2026 to 2034.
About Us
Straits Research is a market intelligence and consulting firm that provides industry analysis, market forecasts, competitive assessments, and strategic insights across multiple industries. The company supports businesses in understanding market dynamics, evaluating opportunities, and making informed decisions through research-driven insights.
Contact Us
Website: https://straitsresearch.com/
Email: [email protected]
Phone: +1 646 905 0080 (U.S.)
Phone: +91 8087085354 (India)
Phone: +44 203 695 0070 (U.K.)