Europe Agricultural Robot Market: Why Labor Shortages Are Accelerating Farm Automation Faster Than Any Policy Ever Could
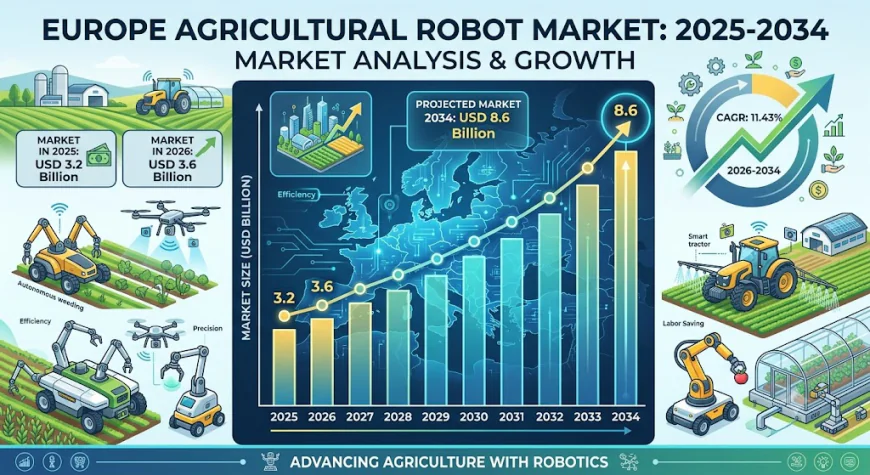
The Europe agricultural robot market increased from USD 3.2 Billion in 2025 to USD 3.6 Billion in 2026 and is expected to reach USD 8.6 Billion by 2034, growing at a CAGR of 11.43% during 2026–2034.
 Team Imarc
Walk through the grape-growing regions of La Rioja, the olive orchards of Andalusia, or the greenhouse corridors of the Netherlands, and the same challenge presents itself in every language. The seasonal workers who have sustained European agriculture for generations are becoming harder to find, more expensive to employ, and increasingly unlikely to be replaced by the next generation of young workers willing to take on physically demanding rural roles. That structural labour reality — not any single technology breakthrough or government subsidy — is the most powerful force driving agricultural robotics adoption across the European continent.
The market data reflects the commercial consequence of that force decisively. The Europe agricultural robot market increased from USD 3.2 Billion in 2025 to USD 3.6 Billion in 2026 and is expected to reach USD 8.6 Billion by 2034, growing at a CAGR of 11.43% during 2026–2034. A market that more than doubles in under a decade — driven simultaneously by demographic pressure, environmental regulation, and accelerating AI capability — is not following a typical technology adoption curve. It is responding to a structural necessity that European farmers can no longer defer.
What's Driving Growth in the Europe Agricultural Robot Market?
- Chronic and deepening agricultural labour shortages are compressing the timeline for automation adoption across the entire continent. Nations including Spain, Italy, and France have historically relied on seasonal migrant workers for labour-intensive tasks including fruit harvesting, weeding, and vine management. Tightening immigration policies, rising labour costs, and a generational disinterest in farm work among European youth have opened a widening supply gap that no recruitment strategy alone can sustainably close — making robotics investment a commercial necessity rather than a productivity aspiration.
- EU environmental regulation mandating precision agriculture practice is simultaneously creating both compliance requirements and technology opportunity. The European Green Deal and Farm to Fork strategy are driving farmers toward precision interventions that minimise pesticide use, reduce water consumption, and lower carbon footprints — objectives that agricultural robots are structurally designed to deliver through targeted, sensor-guided application that replaces the broad-area treatments of conventional farming practice.
- Significant EU institutional funding accelerating commercialisation timelines is compressing the gap between laboratory innovation and field deployment at a scale that private capital alone could not achieve. The European Innovation Council's EUR 10 Billion budget for 2021–2027 supporting academics, entrepreneurs, and innovators from early-stage development to market-ready solutions is creating a commercialisation pipeline that is producing deployable robotics products at a pace that matches the urgency of the labour challenge it is designed to address.
- Spain's market leadership anchoring regional adoption momentum provides both a commercial proof point and a geographic centre of gravity for the broader European market. Spain's combination of labour-intensive viticulture, olive cultivation, greenhouse horticulture, and active government and cooperative support for agri-tech pilot programmes has made it the dominant market share holder in 2025 — demonstrating the commercial viability of agricultural robotics across a diverse range of crop types and operational environments.
- Automated harvesting systems establishing the dominant product category with the largest segment share in 2025 reflects where the labour shortage pain is most acutely felt. Robotic arms equipped with computer vision that can identify ripeness, selectively pick fragile crops including berries, apples, and grapes, and minimise post-harvest damage are addressing the single most labour-intensive and time-critical task in European specialty crop production — the commercial case for which becomes more compelling with every harvest season that passes without sufficient human labour to complete it.
Three Trends Reshaping the Industry
Drone and UAV adoption transforming crop monitoring and precision input management
The rapid adoption of drones and unmanned aerial vehicles across European farming operations represents one of the most commercially accessible and rapidly scaling entry points into agricultural robotics. Approximately one in ten European farms is currently using drones — a penetration rate that positions agriculture as an unexpected leader in commercial drone utilisation. In the Netherlands and France, where high-value horticulture and greenhouse production require constant crop health monitoring, UAVs equipped with thermal and multispectral imaging are enabling farmers to identify plant stress, nutrient deficiencies, and pest invasions across large acreages in the time previously required for manual inspection of a single field section. The April 2025 EU-funded AgRibot project — awarded a EUR 4.97 Million grant to test six robotic systems across Europe focusing on precision spraying, weed management, and harvesting — illustrates how institutional funding is systematically validating drone-based precision agriculture across multiple crop types and geographies simultaneously. Harmonised European drone regulation enabling cross-border testing is further accelerating deployment by removing the regulatory fragmentation that previously made pan-European commercialisation complex for manufacturers.
AI, big data, and advanced sensing creating the intelligent farm operating system
The integration of artificial intelligence, big data analytics, advanced sensor arrays, and precision GPS navigation into the next generation of European agricultural robots is producing systems of a fundamentally different commercial character from the first wave of farm automation equipment. Leading European manufacturers are equipping autonomous tractors, weed robots, and harvesting systems with on-board AI capable of identifying crop varieties, disease signatures, developmental stages, and yield indicators in real time — generating high-resolution data from cameras, LiDAR sensors, and soil probes that cloud platforms aggregate into actionable farm management intelligence. Carbon Robotics' October 2024 raise of USD 70 Million in Series D funding to expand its LaserWeeder business and introduce new products across North America, Europe, and Asia-Pacific signals the scale of private capital conviction in AI-driven agricultural robotics — with the LaserWeeder's machine learning-powered precision weed removal by laser eliminating the need for chemical herbicides in a manner that simultaneously addresses labour costs, regulatory compliance, and sustainability objectives. As edge computing capabilities embedded within the robots themselves improve, the requirement for continuous cloud connectivity is diminishing — enabling autonomous operation in the remote field environments where European arable farming predominantly occurs.
EU-funded collaborative programmes building the commercialisation infrastructure
The structured, multi-stakeholder approach to agricultural robotics development that characterises Europe's innovation ecosystem is producing a commercialisation pathway qualitatively different from market-led technology development. The GRAPE project — developing precision harvesting systems for sensitive viticulture crops in Italian, French, and Spanish wine-growing regions — and the MARS project, focused on multi-purpose autonomous robots for sowing, weeding, and crop scouting in open-field environments, are both engaging universities, technology startups, and established agribusiness companies in co-developing and co-validating solutions in actual farm environments across multiple national contexts simultaneously. The June 2025 launch by Arugga AI Farming of "Louie" — the first autonomous plant lowering robot for greenhouse-grown tomatoes and cucumbers, capable of managing 300 plants per hour — with active deployments already underway in the Netherlands, Belgium, and France, illustrates how EU-backed research is translating into commercially deployable products on an accelerating timeline. The May 2025 acquisition by Manitou Group of the robotics division of Sitia, a French engineering company, as part of its LIFT strategic roadmap, further demonstrates how established European industrial manufacturers are integrating agricultural robotics capability into their core business strategy rather than treating it as a peripheral innovation bet.
What the Market Numbers Actually Tell Us
The single-year growth from USD 3.2 Billion in 2025 to USD 3.6 Billion in 2026 — before the longer CAGR of 11.43% compounds through to USD 8.6 Billion by 2034 — reflects a market that is already in active acceleration rather than early formation. Hardware commands 59.8% of current market share, reflecting a market still in the build-out phase of installing the physical robotic infrastructure across European farms — with software and services positioned to grow their relative contribution as that installed base matures and requires ongoing management, optimisation, and data analytics support. Field farming's leadership in the application segment confirms that the addressable market extends well beyond the specialty crop and viticulture contexts most prominently associated with agricultural robotics in public commentary — encompassing the extensive arable farm footprint across France's grain belt, Germany's diversified farms, and Eastern Europe's large-scale cereal and oilseed operations that represent the continent's highest-volume agricultural production.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe agricultural robot market lies in the convergence of AI-driven precision robotics and the dairy and livestock management segment — currently underrepresented relative to its commercial scale and labour intensity. Milking robots are already an established technology in European dairy farming, but the integration of broader AI-powered animal health monitoring, automated feeding management, and predictive veterinary analytics into a comprehensive dairy farm operating system represents a structurally new product category that the current market has not yet delivered at commercial scale. Simultaneously, Eastern Europe — currently underpenetrated relative to its agricultural land area and growing labour shortage intensity — represents a geographic expansion opportunity for manufacturers who have established commercial validation in Western European markets and are positioned to extend distribution through the cooperative networks and government agricultural support programmes that structure farming investment decisions across Poland, Romania, Hungary, and the Czech Republic. As EU agricultural funding increasingly conditions support on precision farming adoption, the policy environment for accelerated Eastern European uptake is developing in parallel with the commercial readiness of the robotics products designed to serve it.