Agriculture Industry in India 2026–2034: Farm Mechanization, Precision Agriculture & Sustainable Crop Productivity
The India acetic acid market size reached 1.39 Million Tons in 2025 and is projected to reach 2.03 Million Tons by 2034 at 4.32% CAGR.
 chetan kalyan
India Agriculture Industry Outlook
The agriculture sector in India is moving from subsistence-oriented primary production toward a diversified, value-chain-driven ecosystem spanning farming, food processing, dairy, animal husbandry, fisheries, cold chain logistics, and AgriTech-enabled services. Rising incomes, urbanization, and a growing middle class are reshaping food consumption, while government programs continue to anchor investment at the farm level.
As value addition moves downstream into processing, storage, and branded distribution, the industry is becoming more integrated and more investable. Digital public infrastructure, precision farming, and cold chain expansion are accelerating that change across every major subsector.
Market Snapshot
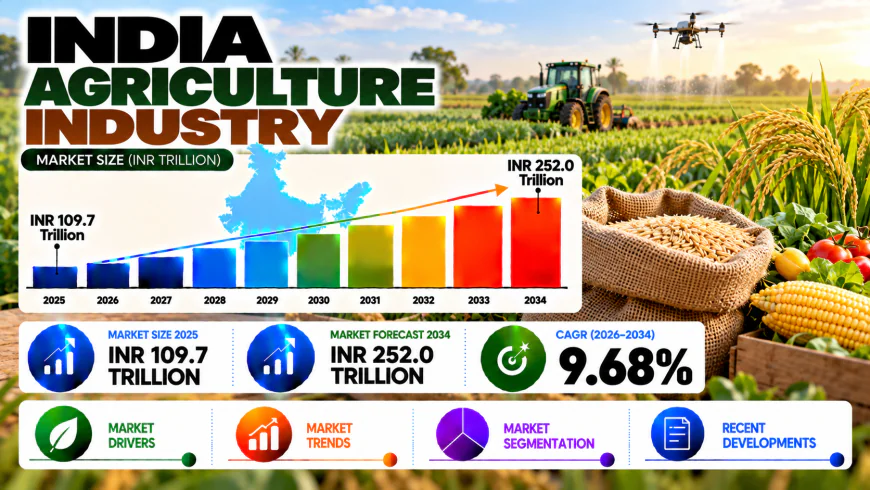
- Market Size (2025): INR 109.7 Trillion
- Historical Market Size (2020): INR 69.1 Trillion
- Forecast Market Size (2034): INR 252.0 Trillion
- CAGR (2026-2034): 9.68%
- Leading Subsector: Farming, 18.0% share (2025)
- Second Largest Subsector: Food Processing, 14.0% share (2025)
- Faster-Growing Subsectors: Food processing and bio-agriculture, expanding faster than the overall market CAGR
- Key Growth Drivers: Government income support, rising food demand, AgriTech adoption, cold chain and processing expansion
Executive Summary
IMARC Group values the India agriculture industry at INR 109.7 Trillion in 2025, up from INR 69.1 Trillion in 2020, and projects INR 252.0 Trillion by 2034 at a CAGR of 9.68%, adding approximately INR 142.3 Trillion in incremental annual market value. These are estimates of industry market value across the report’s subsectors.
They are not GDP contribution, agricultural output, or crop production figures. The agriculture growth rate in India described here is therefore a market value growth rate, and should not be read as a GDP growth rate. Farming holds the largest subsector share at 18.0% and food processing follows at 14.0%. The budget allocation for the Department of Agriculture and Farmers Welfare rose from INR 21,933.50 Crore (around USD 2.64 Billion) in 2013-2014 to INR 1,27,290.16 Crore (around USD 15.34 Billion) for 2025-26.
Competition is concentrated downstream, where ITC, GCMMF, UPL, and DCM Shriram lead in food processing, dairy, agri-inputs, and crop protection, while primary production remains highly fragmented. Government investment in farm income support and infrastructure, AgriTech adoption, growth in processing and cold chains, and expanding exports of high-value commodities are expected to define the next phase of growth.
India Agriculture Industry Key Drivers
- Government Policy and Direct Income Support:
PM-KISAN direct income transfers and expanded minimum support price coverage give farmers income security and production incentives, which support farm-level investment and output growth across the agriculture sector in India.
- Rising Domestic Food Demand:
A population of 1,425,775,850 as of April 2023, growing urbanization, rising per capita incomes, and a shift toward processed and protein-rich foods are creating sustained demand across farming, dairy, poultry, food processing, and fisheries.
- AgriTech Adoption and Digital Infrastructure:
Precision farming, drone-based crop monitoring, IoT-enabled soil sensors, and the AgriStack digital public infrastructure are improving productivity and reducing input wastage across India’s diverse agricultural landscape.
- Expansion of Cold Chain and Food Processing Infrastructure:
Government-funded schemes are supporting integrated cold chain networks, food processing clusters, and mega food parks. These investments enable value addition and reduce post-harvest losses.
Explore the Full Report with Charts, Table of Contents, and List of Figures
India Agriculture Industry Emerging Trends
- Digital Agriculture and the AgriStack Ecosystem:
AgriStack combines a farmer registry, a geo-referenced plot registry, and a crop sown registry, allowing precise targeting of subsidies, credit, insurance, and market information. It is expected to catalyze AI-driven advisory, satellite-based crop monitoring, and e-commerce linkages for small and marginal farmers.
- Shift Toward Processed and Value-Added Foods:
Rising urban incomes and modern retail are accelerating the move from raw commodity sales to branded, packaged, and processed foods. This encourages investment in processing facilities and cold chains, which can raise farmer incomes and cut post-harvest losses.
- Natural and Organic Farming Expansion:
Government policy promotes zero-budget natural farming and organic certification, and consumers are willing to pay a premium for certified organic produce. This is stimulating demand for bio-fertilizers, biopesticides, and compost within bio-agriculture.
- Mechanization and Precision Agriculture:
Farm mechanization remains well below global averages, leaving room for the agriculture equipment subsector. Subsidies on tractors, harvesters, and implements, custom hiring centers, and farmer producer organization-led machinery sharing are widening access.
India Agriculture Industry Challenges
Despite strong momentum, the agriculture market in India faces persistent structural headwinds:
- Fragmented and small landholdings limit machinery use and economies of scale, and make it harder to access institutional finance, advanced technology, and favorable input and marketing terms
- A significant share of cultivated area depends on monsoon rainfall, so erratic monsoons, rising temperatures, and extreme weather raise production risk and yield volatility
- Access to affordable formal credit remains limited for many small and marginal farmers, constraining investment in productivity-enhancing inputs and technologies
- Multiple intermediary layers and fragmented mandi regulation across states reduce price realization for farmers and create inefficiencies in distribution
India Agriculture Industry Segment Insights
By Subsector
- Farming: 18.0% (food grains, fruits, vegetables, and cash crops)
- Food Processing: 14.0% (organized retail, export of processed foods, food parks)
- Other subsectors covered: Agriculture Equipment, Fertilizers, Pesticides, Warehousing, Cold Chains, Dairy Market, Floriculture, Apiculture, Sericulture, Seeds, Fisheries, Poultry, Animal Husbandry, Animal Feed, and Bio-agriculture Market
The report covers seventeen subsectors. Share data is provided for farming and food processing.
By Value Chain Stage
- Input Supply (seeds, fertilizers, pesticides, irrigation equipment, farm machinery)
- Primary Production (farms, livestock, fisheries, poultry, apiculture, sericulture, horticulture)
- Processing and Value Addition (food processing plants, dairy cooperatives, poultry and fish processors)
- Storage and Logistics (cold chain operators, warehousing, transport)
- Retail and Distribution (wholesale mandis, modern retail, e-commerce, export trading houses)
- Enablers (government agencies, agricultural banks, cooperatives, AgriTech firms, research institutions)
Evaluate Market Opportunity with the Business Sample Report
Competitive Landscape
The industry is highly diversified and fragmented at the primary production level, while organized competition is concentrated in food processing, dairy, agri-inputs, equipment, and export trade. Brand strength, backward integration, cold chain capability, and regulatory compliance form the main competitive advantages. Vertically integrated players that combine input supply, production, processing, and branded distribution are positioned to capture the most value.
- ITC: Brand / Platform: Aashirvaad
Core Strength: Diversified agribusiness with integrated supply chain and the e-Choupal farmer network - GCMMF: Brand / Platform: Amul
Core Strength: Cooperative-led dairy and food processing at national scale - UPL: Brand / Platform: Brucia, Centurion EZ, Saaf, Uthane M45
Core Strength: Crop protection, seeds, and sustainable farming solutions - DCM Shriram: Brand / Platform: Shriram Farm Solutions
Core Strength: Agri inputs and seeds
Government Initiatives Supporting the Market
- PM-KISAN: Direct income support that anchors farm-level investment and spending
- Minimum Support Price Coverage: Price support that gives farmers income security and production incentives
- Pradhan Mantri Matsya Sampada Yojana: Flagship program supporting fisheries development
- AgriStack and Digital Agriculture: Digital public infrastructure for registries, subsidy targeting, credit, and insurance
- Food Processing and Cold Chain Schemes: Government-funded support for mega food parks, cold chain networks, and processing clusters
- Natural Farming and Organic Certification: Policy support for natural farming and certified organic production
Recent Developments
- November 2025: PM-KISAN had disbursed more than 3.70 Lakh Crores to over 11 Crore farmer families since inception
- 2025: ITC’s Agri Business Division received multiple awards at the 4th Edition of the BW Businessworld Supply Chain Leadership Awards 2025
Investment Opportunities
- High-Growth Segments: Bio-agriculture is expected to grow at the highest rate through 2034, driven by preference for organic and chemical-free food. Food processing and cold chains follow, supported by organized retail, exports, and infrastructure investment.
- Geographic Expansion: Tier-2 and tier-3 cities, Northeastern India, and coastal aquaculture zones are largely untapped, with openings in cold chain connectivity, digital market access, and organized dairy and poultry in eastern and northeastern India.
- Venture & Strategic Investment: Private equity, venture capital, and corporate investors are targeting AgriTech platforms, precision farming, digital marketplaces, advisory services, and processing infrastructure, while export growth rewards investment in quality compliance and value-added processing.
Request Customized Data Tailored to Your Interest
Frequently Asked Questions (FAQ)
- What is the size of the agriculture industry in India?
IMARC Group values the India agriculture industry at INR 109.7 Trillion in 2025, covering farming, food processing, dairy, animal husbandry, and allied subsectors.
- What is the projected growth rate?
The industry is projected to grow at a CAGR of 9.68% during 2026-2034, reaching INR 252.0 Trillion by 2034. This is a market value forecast, not a GDP or crop output forecast.
- Which subsector leads?
Farming leads with an 18.0% share in 2025, followed by food processing at 14.0%.
- Which government programs support the industry?
PM-KISAN and Pradhan Mantri Matsya Sampada Yojana are key flagship programs, alongside minimum support prices, AgriStack, and food processing and cold chain schemes.
- Who are the leading companies?
Leading players include ITC, GCMMF, UPL, and DCM Shriram, among others.
Conclusion
The India agriculture industry is on a sustained growth path, supported by income support policy, rising food demand, and a steady move toward processed and value-added products. Fragmented landholdings and monsoon dependency remain real constraints, but digital infrastructure, mechanization, and cold chain expansion are narrowing the gap.
Four forces will shape the industry through 2034: government investment in farm income and infrastructure, accelerating AgriTech adoption, rapid growth in food processing, cold chains, and dairy, and expanding trade in high-value commodities. Organizations that invest in integrated supply chains, digital market access, and processing capability will be best placed to capture a significant share of the INR 142.3 Trillion in incremental market value.
Source: IMARC Group