Canada Cement Market Size, Share, Trends & Growth Report 2026-2034
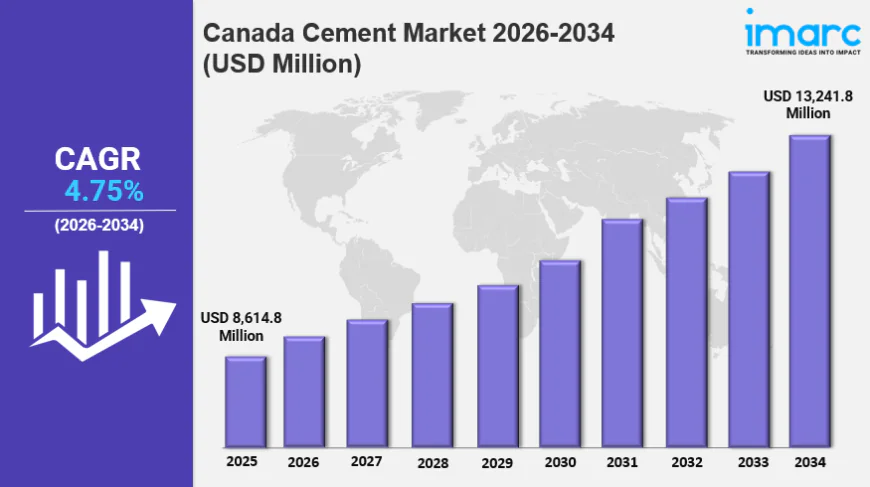
The Canada cement market size reached USD 8,614.8 Million in 2025 and is projected to reach USD 13,241.8 Million by 2034, expanding at a CAGR of 4.75% during 2026-2034.
 marketinsights
IMARC Group has recently released a new research study titled "Canada Cement Market Report by Type (Blended, Portland, Others), End-Use (Residential, Commercial, Infrastructure), and Region 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
Canada Cement Market Size & Share 2026-2034
The Canada cement market size reached USD 8,614.8 Million in 2025 and is projected to reach USD 13,241.8 Million by 2034, expanding at a CAGR of 4.75% during 2026-2034. In 2026, the market continues to gain momentum, shaped by rising residential and infrastructure construction, replacement demand for aging structures, and government-backed housing and green infrastructure programs.
Growth in 2026 is further reinforced by low interest rates, industrial recovery, population growth, and proximity to US export opportunities, particularly in Ontario and British Columbia. These dynamics are expected to strengthen the Canada cement market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 8,614.8 Million
- Projected Market Size (2034): USD 13,241.8 Million
- Growth Rate: CAGR of 4.75% (2026-2034)
Explore Opportunities in the Canada Cement Market: Download the IMARC Sample Report: https://www.imarcgroup.com/canada-cement-market/requestsample
Key Growth Drivers and Trends in the Canada Cement Market
Growth in the Canada cement market is being driven primarily by the decarbonization push shaping plant upgrades. Cement producers are moving toward cleaner operations by upgrading legacy facilities with more efficient digital systems and advanced automation platforms that cut emissions and optimize output. Plants producing low-carbon cement blends are scaling up, often alongside pilot carbon capture initiatives, reflecting a strategy focused less on expanding capacity and more on retooling existing assets to align with climate goals.
One example of this trend is Lafarge Canada's modernization of its Bath Cement Plant in Ontario in October 2024 using ABB's advanced control system, ABB Ability System 800xA. The upgrade is expected to improve process efficiency and support Lafarge's decarbonization goals. The plant produces over 1 Million Tons of low-carbon OneCem annually and is also piloting carbon capture technology.
Another key factor supporting Canada cement market growth is the rise of low-carbon cement alternatives. New materials based on magnesium cement are entering the Canadian market as viable substitutes for traditional options. These fire-rated, moisture-resistant products use locally sourced components, reducing reliance on gypsum and imported MgO, and use proprietary technology that converts industrial waste into cement. In March 2025, ZS2 Technologies introduced its second-generation magnesium cement materials in Canada, including TechBoard, TechTile, and TechStone, backed by USD 9.9 Million in grants.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=37418&flag=C
Canada Cement Industry Segmentation Insights
Breakup by Type:
- Blended: Cement produced by combining clinker with supplementary materials, supporting lower-carbon construction.
- Portland: The most widely used type of cement, forming the basis of conventional concrete across construction applications.
- Others: Includes specialty and alternative cements, such as emerging magnesium-based products.
Breakup by End-Use:
- Residential: Cement used in housing construction, supported by population growth and government-backed housing programs.
- Commercial: Cement used in offices, retail spaces, and other commercial buildings.
- Infrastructure: Cement used in roads, bridges, and other public works, supported by replacement demand for aging structures and green infrastructure programs.
Breakup by Region:
- Ontario: A leading market with strong residential and infrastructure construction and plants such as Lafarge's Bath Cement Plant pivoting toward low-carbon production.
- Quebec: A major regional market supported by ongoing construction and infrastructure activity.
- Alberta: A regional market that is home to Heidelberg Materials' planned Edmonton carbon capture project.
- British Columbia: A leading market with strong residential and infrastructure construction demand.
- Others: Includes the remaining provinces and territories of Canada.
Key Challenges and Growth Opportunities in the Canada Cement Market
The Canada cement market faces challenges including the cost and complexity of upgrading legacy facilities, the need to reduce emissions in a carbon-intensive industry, and the pressure to meet stricter building codes and climate targets.
Despite these challenges, the market offers considerable growth opportunities driven by rising residential and infrastructure construction, replacement demand for aging structures, and government-backed housing and green infrastructure programs. Investment in smart technologies, low-carbon cement blends, magnesium cement alternatives, and carbon capture is also expected to support long-term growth.
Competitive Landscape
The Canada cement market is competitive and is shaped by established cement producers such as Lafarge Canada and Heidelberg Materials, alongside technology suppliers such as ABB and emerging low-carbon material developers such as ZS2 Technologies. Key players focus on plant modernization, low-carbon products, and carbon capture initiatives. The IMARC report examines the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of the major companies.
Recent Developments in the Canada Cement Market
- March 2025: Canada advanced emissions reduction in heavy industry by supporting Heidelberg Materials' carbon capture project in Edmonton. Innovation, Science and Economic Development Canada is negotiating a federal contribution agreement of up to USD 275 Million, following a 2023 memorandum of understanding. A USD 49 Million agreement has already been signed for the first phase of the project, the first full-scale CCUS plant in North America's cement sector.
- March 2025: ZS2 Technologies introduced its second-generation magnesium cement materials in Canada, offering fire-rated, low-carbon alternatives to traditional gypsum and MgO imports, backed by USD 9.9 Million in grants.
- October 2024: Lafarge Canada modernized its Bath Cement Plant in Ontario using ABB's ABB Ability System 800xA control system to improve process efficiency and support its decarbonization goals.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: [email protected]
United States: +1-201-971-6302