Used Car Loan Eligibility: CIBIL Score, Income & Documents
Learn about used car loan eligibility, CIBIL score, income requirements and documents needed. Find out how to improve your chances of loan approval.
 RajasthanAutomobileNews
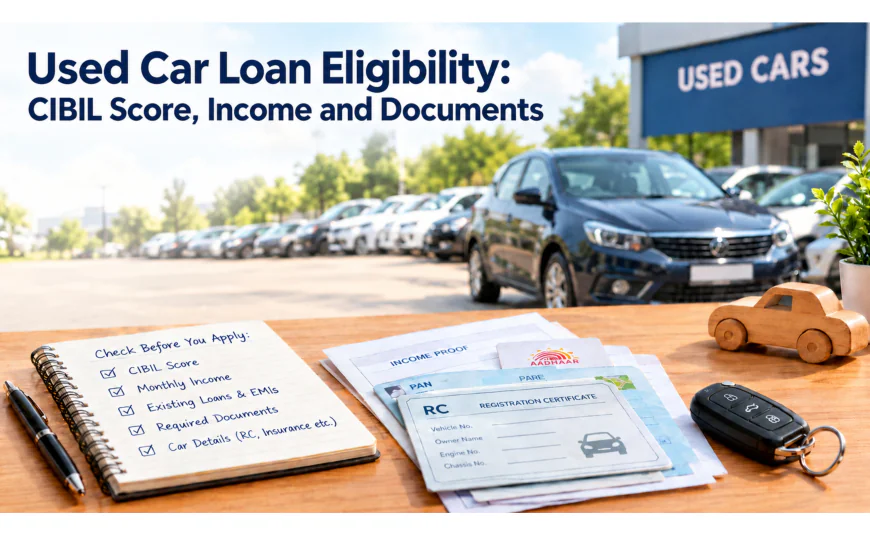
Buying a second-hand car is a good option if you want a car without spending too much money. But what if you cannot pay the full amount at once? A used car loan can help you buy the car by paying a fixed EMI every month. Before applying for a loan, you should know whether you are eligible.
Banks and finance companies usually check your CIBIL score, monthly income, existing loans and documents before making a decision. In this article, we will explain the basic requirements for a used car loan, which documents you need and how you can improve your chances of getting approval.
1. What Is Used Car Loan Eligibility?
Used car loan eligibility means the conditions you need to meet to get a loan for a second-hand car. Every bank or finance company has its own rules. Some focus more on your income and credit history, while others also consider the car's age and market value.
Before applying, check these important points:
-
Your CIBIL score and repayment history.
-
Your monthly salary or business income.
-
Your existing loans and EMIs.
-
Your employment or business stability.
-
The documents you can provide.
-
The age and condition of the car you want to buy.
Checking these details before applying can help you choose a suitable lender and avoid unnecessary delays.
2. What CIBIL Score Do You Need for a Used Car Loan?
Your CIBIL score gives lenders an idea of how you have managed loans and credit cards in the past. It usually ranges from 300 to 900. A good credit score can improve your chances of getting a loan on favourable terms. If your score is low, the lender may ask for additional information or offer different terms. Approval is not guaranteed at any particular score.
Here is a general guide:
|
CIBIL score |
What it generally indicates |
|
750 and above |
A strong credit profile |
|
700–749 |
A reasonably good credit profile |
|
650–699 |
The lender may review your application more carefully |
|
Below 650 |
Getting approval may be more difficult |
These are general guidelines, not fixed rules followed by every lender.
How Can You Improve Your CIBIL Score?
If your score is low, try to improve your credit habits before applying.
-
Pay your existing EMIs on time.
-
Avoid missing credit card payments.
-
Clear overdue amounts where possible.
-
Avoid applying for several loans within a short period.
-
Check your credit report for incorrect information.
You may not see an immediate improvement, but maintaining a good repayment record can help over time.
3. How Much Salary Do You Need for a Used Car Loan?
There is no single salary requirement for every used car loan. The amount you need to earn depends on the lender, the loan amount and your existing financial commitments. For example, a person earning ₹35,000 per month with no major existing EMIs may have a better repayment capacity than someone earning the same amount but already paying several loans.
Lenders may look at:
-
Your monthly take-home salary or business income.
-
Your current EMIs.
-
Your household expenses.
-
Your job or business stability.
-
The amount you want to borrow.
The main thing is to show that you can comfortably repay the loan without putting too much pressure on your monthly budget.
How Much EMI Can You Afford?
Before taking a loan, work out how much money you have left after your regular expenses. For example, suppose you earn ₹40,000 per month and already pay ₹8,000 towards other EMIs. You should consider your remaining income before deciding how much additional EMI you can afford.
Remember that owning a car also involves fuel, insurance, servicing and unexpected repairs. Choose an EMI that leaves enough money for these expenses.
4. Can Salaried and Self-Employed People Get a Used Car Loan?
Yes, both salaried and self-employed people can apply for a used car loan. However, the lender will check their income and financial stability before approving the application.
For Salaried People
If you work for a company, you may be asked to provide:
-
Recent salary slips.
-
Bank statements showing salary credits.
-
Employment details.
-
Existing loan information.
A regular income and a good repayment history may strengthen your application.
For Self-Employed People
If you run a business or work independently, the lender may ask for:
-
Bank statements.
-
Income tax returns, where required.
-
Business registration or proof of business activity, where applicable.
-
Financial statements or other income documents.
The purpose is to understand whether your income is sufficient and stable enough to repay the loan.
5. Which Documents Are Required for a Used Car Loan?
Keeping your documents ready can make the loan application process easier. The exact requirements vary from one lender to another.
Here are the documents you may need.
Identity Proof
You may need an accepted identity document, such as a PAN card, Aadhaar where accepted, passport or another approved document.
Address Proof
The lender may ask for proof of your current address. Check which documents are accepted before submitting your application.
Income Proof
Salaried applicants may need salary slips, bank statements or Form 16, depending on the lender's requirements.
Self-employed applicants may be asked for income tax returns, business documents or financial statements.
Bank Statements
Bank statements help the lender understand your income, spending habits and existing loan payments. You may need to provide statements for a specified period.
Used Car Documents
The lender may also ask for:
-
Registration Certificate (RC).
-
Details of the car you want to purchase.
-
Insurance information.
-
A quotation or sale-related documents.
-
Additional documents required for the vehicle or loan.
If the car already has a loan against it, extra paperwork may be necessary to settle the existing finance and complete the transaction.
Tip: Ask your bank or finance company for its complete document checklist before applying.
6. Does the Age of the Car Affect Loan Approval?
Yes. The age of the car can affect whether a lender is willing to finance it. Some lenders have restrictions on how old the vehicle can be when the loan starts or when the repayment period ends. They may also consider its condition, market value and resale potential.
Before selecting a used car, ask the lender:
-
What is the maximum permitted age of the car?
-
Does the car's model meet the lender's requirements?
-
How much loan can be approved against its value?
-
What repayment period is available?
Checking these details first can save you time if the car does not qualify for financing.
7. How Much Loan Can You Get for a Second-Hand Car?
The loan amount depends on your financial profile, the car's value and the lender's policy. For example, suppose you want to buy a used car priced at ₹5 lakh. The lender may agree to finance only a part of that amount. You would need to pay the remaining amount yourself as a down payment.
The approved amount may differ between lenders, even for the same car.
Before accepting a loan offer, check:
-
The total loan amount.
-
The interest rate.
-
The monthly EMI.
-
The processing fee and other charges.
-
The total amount you will repay.
-
The down payment required.
Do not assume that a lender will finance the full price of the car. Confirm the amount before finalising your purchase.
8. How Can You Improve Your Chances of Loan Approval?
You can take a few simple steps before submitting your application. Check your CIBIL score: Review your credit report and correct any errors you find. Choose a car within your budget: A more affordable car can mean a smaller loan and a more manageable EMI. Prepare your documents: Make sure your identity, income and vehicle details are accurate.
Manage existing loans: Where possible, reduce outstanding debt and avoid taking on unnecessary new credit. Compare different lenders: Look at interest rates, processing fees, eligibility conditions and repayment periods. Arrange your down payment: Saving some money towards the car can reduce the amount you need to borrow. These steps can strengthen your application, but the final decision will depend on the lender's assessment.
9. Why Can a Used Car Loan Application Be Rejected?
Sometimes, a loan application is rejected even when the applicant has a regular income. This may happen for several reasons.
Common reasons include:
-
A low CIBIL score or missed loan payments.
-
Income that does not meet the lender's requirements.
-
Too many existing EMIs.
-
Missing or incorrect documents.
-
Difficulty verifying employment or business income.
-
A car that does not meet the lender's age or valuation requirements.
If your application is rejected, ask the lender why. Understanding the reason can help you address the problem before applying again. Avoid submitting multiple applications without first checking what went wrong.
10. Used Car Loan Eligibility Checklist
Before applying for a loan, take a moment to check the following:
-
I have checked my CIBIL score.
-
I know how much EMI I can afford.
-
I have reviewed my existing loans.
-
My identity and address documents are ready.
-
My income documents are available.
-
I have checked the car's RC and other relevant details.
-
I have confirmed that the car meets the lender's requirements.
-
I have compared interest rates and processing fees.
-
I know how much down payment I need.
Completing this checklist can help you prepare for the application and make a more informed decision.
Final Verdict
Getting a used car loan becomes easier to plan when you understand the eligibility requirements beforehand. Your CIBIL score, monthly income, existing EMIs and financial documents all play a role in the lender's decision. Before choosing a car, check your credit profile, calculate a comfortable EMI and compare loan offers from different lenders.
Also, make sure the vehicle meets the lender's financing requirements. Our aim is to help buyers understand the used car buying process and make informed decisions. A little preparation before applying for a loan can help you choose a car that fits both your needs and your budget.