Unsecured Business Loans Market Forecast 2026–2034: Key Drivers and Challenges
7% during the forecast period from 2026 to 2034, propelled by the integration of credit options into business software, e-commerce platforms, and digital payment services.
 Eknath Girhepunje
The global unsecured business loans market is gaining momentum as small businesses, entrepreneurs, and established enterprises seek flexible financing to manage working capital, operating expenses, inventory purchases, and business development. Unsecured business loans allow eligible borrowers to access funds without pledging physical assets as collateral, making them a relevant financing option for businesses with limited fixed assets or immediate cash flow requirements. Digital lending platforms, alternative credit assessment methods, and data-driven underwriting are also reshaping how lenders evaluate applications and deliver financing.
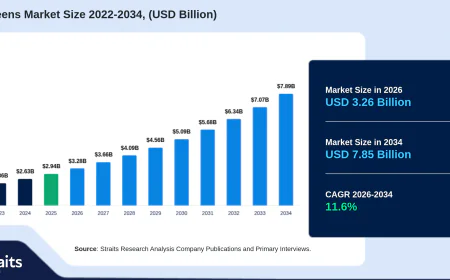
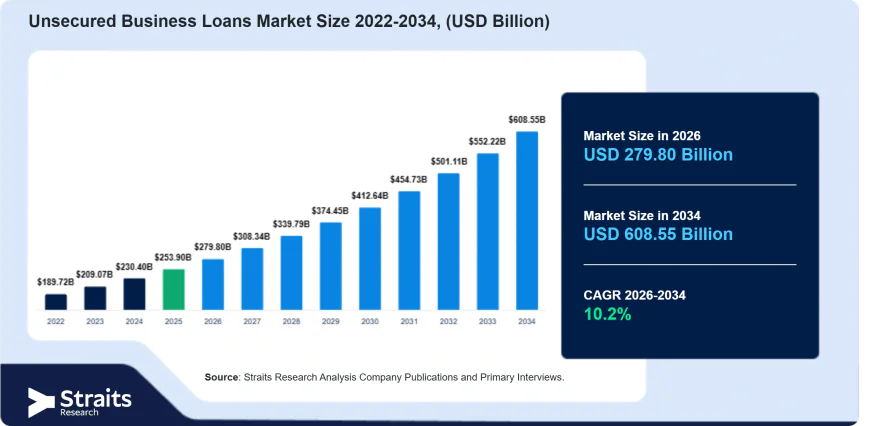
The global unsecured business loans market size was valued at USD 253.9 billion in 2025 and is projected to grow from USD 279.80 billion in 2026 to USD 608.55 billion by 2034, registering a CAGR of 10.2% during the forecast period from 2026 to 2034. North America dominated the unsecured business loans market with a share of 36.4% in 2025, supported by its established banking sector, digital lending infrastructure, and demand for financing among small and medium-sized businesses.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/unsecured-business-loans-market
Market Drivers
Demand for Collateral-Free Business Financing
The need for accessible financing supports the unsecured business loans market, particularly among small businesses that lack sufficient property, machinery, or other assets to pledge as collateral. These loans can help eligible borrowers cover payroll, purchase software, manage operating expenses, and fund short-term business requirements. For example, a digital marketing agency may use an unsecured loan to recruit employees or purchase technology without pledging office assets. This financing structure provides businesses with another borrowing option, while lenders evaluate applications through credit history, revenue, cash flow, and repayment capacity.
Working Capital Requirements and Seasonal Inventory Purchases
Seasonal trading patterns create financing requirements for businesses that must purchase inventory before receiving customer payments. Retailers and wholesalers may need funds to prepare for festive periods, promotional campaigns, and other periods of concentrated sales activity. An unsecured business loan can help an eligible retailer purchase seasonal products and manage supplier payments while waiting for sales revenue. These working capital needs support the use of short-term financing products and encourage lenders to develop loan structures suited to different business cash flow cycles.
Digital Lending and AI-Based Credit Assessment
Digital lending platforms and artificial intelligence-based credit assessment tools are changing how lenders evaluate business loan applications. Automated systems can analyze financial records and alternative business data to support creditworthiness assessments and underwriting decisions. In September 2026, an analysis by the Federal Reserve Bank of San Francisco examined how AI adoption affected bank lending and identified associations with changes in small business lending patterns. These developments highlight the role of data-driven lending tools in application assessment, although credit decisions still depend on lender policies and borrower risk profiles.
Market Challenges
Financial Literacy and Borrower Awareness
Limited financial literacy can restrict access to unsecured business loans when business owners have difficulty comparing interest rates, understanding repayment schedules, or calculating the total cost of borrowing. Inadequate financial planning may also lead borrowers to underestimate repayment obligations or select financing that does not match their cash flow. These concerns can discourage businesses from applying for formal credit or contribute to unsuitable borrowing decisions. Clear loan disclosures, financial education, and transparent repayment terms can help borrowers evaluate financing options more effectively.
Loan Approval and Underwriting Requirements
Lenders must assess business revenue, credit history, cash flow, existing debt, and repayment capacity when approving unsecured loans because these facilities do not rely on collateral as a primary source of recovery. The Federal Reserve’s 2026 Small Business Credit Survey, as cited in the market report, found that 42% of financing applicants received the full amount requested, while 22% received no financing. These findings illustrate the challenges some businesses face when seeking suitable credit. Lengthy assessments or unsuccessful applications can delay working capital access and affect business investment plans.
Credit Risk and Borrowing Costs
Unsecured lending exposes providers to credit risk because repayment generally depends on the borrower’s financial performance and willingness to repay rather than the recovery of pledged assets. Lenders may respond to this risk through stricter eligibility criteria, higher interest rates, loan limits, or additional income verification. For businesses with limited credit histories or irregular revenue, these conditions can reduce access to affordable financing. Managing default risk while maintaining competitive loan terms remains an important challenge for banks, fintech companies, and alternative lenders.
Market Segmentation
By Loan Type
The market is segmented into short-term working capital loans, medium-term term loans, business lines of credit, merchant cash advances, and other loan types. The short-term working capital loans segment dominated the loan type category with a share of 27.4% in 2025, owing to its role in helping businesses manage routine operating expenses, inventory purchases, and short-term cash flow requirements.
The embedded business credit segment is expected to register a CAGR of 14.3% during the forecast period from 2026 to 2034, fueled by the integration of financing options into digital business platforms, payment systems, and online commerce workflows. Embedded financing can give eligible businesses access to credit within the platforms they already use to manage operations and sales.
By Borrower Size
The market is segmented into micro enterprises, small enterprises, medium enterprises, and sole proprietors. The small enterprises segment dominated the borrower size category with a share of 34.6% in 2025, supported by financing requirements for operating costs, inventory management, and day-to-day business activities.
The micro enterprises segment is expected to register a CAGR of 11.5% during the forecast period from 2026 to 2034, driven by the need for accessible financing to cover working capital requirements and manage limited cash reserves. Digital application channels and alternative credit assessment methods may help lenders evaluate eligible businesses with limited traditional credit records.
By Distribution Channel
The market is segmented into bank direct lending, fintech digital lending platforms, peer-to-peer lending platforms, non-banking financial companies, and other channels. Bank direct lending dominated the distribution channel category with a share of 35.2% in 2025, owing to established banking relationships, familiar lending processes, and access to business financing services.
The embedded finance providers segment is estimated to register a CAGR of 14.7% during the forecast period from 2026 to 2034, propelled by the integration of credit options into business software, e-commerce platforms, and digital payment services. This model allows lenders to connect financing offers with business transactions and platform-based financial information.
By Interest Rate
The market is segmented into fixed interest rate loans and variable interest rate loans. The fixed interest rate loans segment is expected to register a CAGR of 9.5% during the forecast period from 2026 to 2034, supported by borrowers’ preference for predictable repayment obligations and greater certainty in financial planning.
The variable interest rate loans segment is expected to register a CAGR of 11.3% during the forecast period from 2026 to 2034, driven by borrowers seeking flexible financing structures that can respond to changing interest rate conditions. The suitability of these loans depends on borrowers’ tolerance for payment changes and their ability to manage potential cost fluctuations.
By End Industry
The market serves retail, professional services, and other industries. The retail segment dominated the end industry category with a share of 22.6% in 2025, owing to working capital requirements for inventory purchases, supplier payments, and seasonal operating expenses.
The logistics segment is estimated to register a CAGR of 11.7% during the forecast period from 2026 to 2034, fueled by financing requirements for fleet operations, fuel expenses, equipment maintenance, and transportation infrastructure. Flexible credit can help eligible logistics businesses manage operating expenses and short-term cash flow gaps.
Regional Insights
North America
North America dominated the unsecured business loans market with a share of 36.4% in 2025. The region benefits from an established commercial banking sector, a broad range of digital lending providers, and financing requirements among small businesses. In the U.S., the Consumer Financial Protection Bureau issued a final rule on May 1, 2026, revising small-business lending data requirements under the Equal Credit Opportunity Act and extending the compliance date to January 1, 2028. The changes could influence lender reporting processes and credit assessment practices, while individual loan approvals will continue to depend on borrower eligibility and lender underwriting criteria.
In Canada, the Small Business Financing Program provides a government-supported framework for eligible small-business lending, with official loan and claims data updated on July 20, 2026, according to the market report. Although the program is not limited to unsecured loans, its financing activity provides context for small-business credit availability and the broader commercial lending environment.
Asia Pacific
The Asia Pacific unsecured business loans market is expected to register a CAGR of 12.8% during the forecast period from 2026 to 2034, making it the fastest-growing regional market according to the report. Financing programs, digital lending services, and support for small businesses are shaping credit availability across the region. In Japan, the Small and Medium Enterprise Agency updated information about its Marukei financing program on April 8, 2026. The program provides eligible small businesses with financing without collateral or personal guarantees through the Japan Finance Corporation, subject to recommendations from chambers of commerce and other eligible support organizations.
In China, government departments announced an SME loan interest-subsidy policy in January 2026, providing an annual subsidy of 1.5 percentage points for eligible fixed-asset loans issued from January 1, 2026. Support can extend for up to two years, with an eligible loan ceiling of CNY 50 million per borrower. Although the policy does not specifically require loans to be unsecured, it may lower borrowing costs for eligible businesses. In India, the Ministry of Micro, Small and Medium Enterprises reported on March 14, 2026, that the Pradhan Mantri Mudra Yojana provides collateral-free loans to eligible entrepreneurs and small businesses through participating financial institutions, directly supporting the broader unsecured business lending ecosystem.
Europe
The Europe unsecured business loans market is expected to register a CAGR of 9.1% during the forecast period from 2026 to 2034. Financing initiatives and policy attention toward small and medium-sized enterprises are influencing the regional lending environment. In the U.K., the Financial Conduct Authority published its SME access-to-finance feedback statement on September 17, 2026, identifying challenges such as complex applications, limited awareness of financing options, and difficulty obtaining suitable products for businesses with limited collateral or intangible assets. These findings could inform measures aimed at improving access to unsecured business loans.
In Germany, the Federal Ministry of Finance, the federal government, and KfW reported on July 15, 2026, that the Deutschlandfonds had begun providing financing, with an additional EUR 1.5 billion planned over ten years for start-ups, scale-ups, and medium-sized businesses. The initiative could strengthen access to business financing and support lending capacity, although the announced funding is not exclusively allocated to unsecured loans.
Key Players Analysis
The major players in the unsecured business loans market include American Express Company, Bank of China Limited, Bank of America Corporation, JPMorgan Chase & Co., and Wells Fargo & Company.
- American Express Company
- Bank of China Limited
- Bank of America Corporation
- JPMorgan Chase & Co.
- Wells Fargo & Company
The market is highly fragmented, with commercial banks, non-banking financial companies, fintech lenders, digital payment providers, and alternative financing platforms serving businesses of different sizes. Established providers compete through lending capacity, interest rates, credit assessment capabilities, brand reputation, approval speed, customer relationships, and distribution networks. Specialized lenders and fintech companies differentiate themselves through digital applications, alternative credit scoring, flexible eligibility criteria, and financing products tailored to specific business needs.
Conclusion
The unsecured business loans market is projected to reach USD 608.55 billion by 2034, registering a CAGR of 10.2% during the forecast period from 2026 to 2034. Demand for collateral-free financing, working capital, and seasonal inventory funding supports the market, while AI-based credit assessment and embedded finance are reshaping lending processes. Short-term working capital loans and bank direct lending held leading positions in their respective segments in 2025. North America accounted for the largest regional share, while Asia Pacific is projected to record the fastest growth. Credit risk, borrower awareness, underwriting requirements, and financing costs remain important challenges. Continued development of digital lending infrastructure and financing partnerships may influence market access and competition through 2034.
About Us
Straits Research is a market intelligence and consulting firm that provides industry analysis, market forecasts, competitive assessments, and strategic insights across multiple sectors. The company supports organizations in understanding market dynamics, evaluating commercial opportunities, and making informed decisions through research-driven insights.
Contact Us
Website: https://straitsresearch.com/
Email: [email protected]
Phone: +1 646 905 0080 (U.S.)
Phone: +91 8087085354 (India)
Phone: +44 203 695 0070 (U.K.)