Military Drone Market Opportunities in Tactical Logistics and Resupply Operations
The 151–1,200-kg segment is expected to grow at a CAGR of 12.8% during the forecast period from 2026 to 2034, supported by its capacity to carry heavier mission equipment and specialized military payloads.
 Eknath Girhepunje
The global military drone market is becoming an important part of modern defense systems, supporting intelligence gathering, surveillance, reconnaissance, tactical logistics, and other military operations. Military drones, also known as unmanned aerial vehicles (UAVs), enable defense forces to monitor large areas, collect real-time information, and conduct missions in locations where conventional aircraft or ground operations may face limitations. Advances in autonomous flight, secure communications, sensor integration, and drone countermeasures are shaping military drone market trends and procurement priorities.
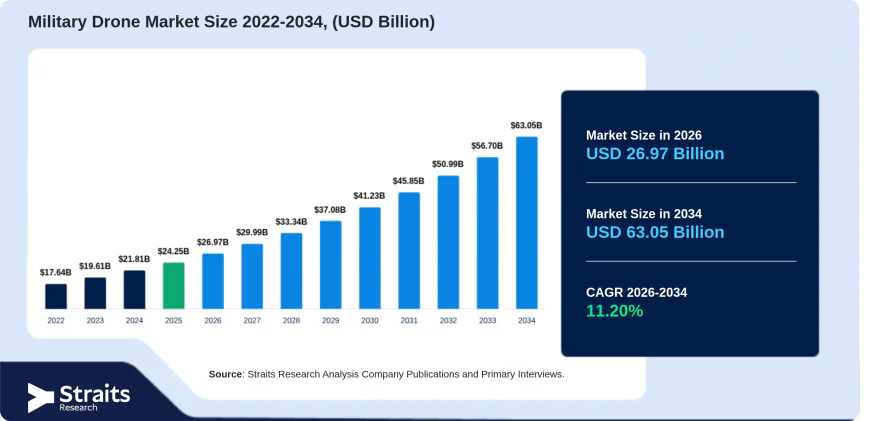
The global military drone market size was valued at USD 24.25 billion in 2025 and is projected to grow from USD 26.97 billion in 2026 to USD 63.05 billion by 2034, registering a CAGR of 11.20% during the forecast period from 2026 to 2034. North America dominated the military drone market with a share of 38.4% in 2025, supported by defense technology investment, established aerospace manufacturers, and demand for advanced unmanned systems.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/military-drone-market
Market Drivers
Tactical Logistics and Military Resupply Requirements
Military drone market growth is supported by the need to deliver essential supplies to remote or difficult-to-access military positions. Unmanned aerial systems can transport lightweight equipment, medical supplies, food, and communication components when ground transportation is limited or unsuitable. These capabilities can help military units maintain access to critical materials while reducing dependence on conventional transport in challenging environments. The demand for cargo drones encourages manufacturers to develop platforms with suitable payload capacity, reliable navigation, and secure delivery systems.
Demand for Intelligence, Surveillance, and Reconnaissance
Intelligence, surveillance, and reconnaissance (ISR) missions are a major application area for military drones because defense forces require timely information about terrain, infrastructure, and potential threats. Drones equipped with cameras, sensors, and communication systems can support battlefield monitoring and maritime surveillance over extended areas. Long-endurance platforms can also maintain observation for longer periods, reducing the need for frequent aircraft rotations. These operational requirements support procurement of drones with improved flight endurance, sensor integration, and dependable data transmission capabilities.
Secure Communications and Autonomous Flight Technologies
Reliable communications and autonomous flight systems are important to military drone operations, particularly in environments where signal interference and cybersecurity risks can affect mission performance. Encrypted data links help protect sensitive information and maintain communication between aircraft and control centers. Advances in onboard navigation, automated mission planning, and flight-control technologies also support the development of systems that can perform selected tasks with less direct intervention. These requirements encourage investment in resilient communication systems, cybersecurity features, and autonomous capabilities across military drone platforms.
Market Challenges
Cybersecurity and Electronic Warfare Risks
Cybersecurity threats can limit military drone deployment because unmanned systems depend on communication links, navigation data, onboard software, and control networks. Attempts to disrupt these systems may compromise mission information, interrupt command links, or reduce operational reliability. Defense agencies must therefore consider cybersecurity testing, secure communications, software protection, and system resilience when evaluating military drone purchases. These additional requirements can increase development and procurement costs while making system integration more complex.
GPS Spoofing and Signal Jamming
GPS spoofing and signal jamming can interfere with drone navigation, positioning, and communication. Electronic warfare systems may disrupt radio-frequency links or transmit misleading navigation signals, creating operational risks for unmanned aircraft. Addressing these vulnerabilities requires investment in resilient navigation technologies, alternative positioning methods, secure data links, and electronic-warfare testing. The need to protect drones against interference can increase system costs and create additional technical requirements for manufacturers and defense organizations.
Complex Procurement and System Integration
Military drone procurement involves technical evaluation, operational testing, cybersecurity assessments, and integration with existing defense systems. Different armed forces may require specific payload configurations, communication standards, flight capabilities, and compatibility with command-and-control infrastructure. These requirements can lengthen procurement cycles and increase development expenses, particularly for specialized platforms. Manufacturers must demonstrate reliability, operational suitability, and compatibility with military requirements to secure contracts and maintain long-term customer relationships.
Market Segmentation
By Type
Based on type, the military drone market is segmented into small, tactical, and strategic drones. The tactical segment accounted for 42.7% of the market in 2025, owing to its suitability for battlefield surveillance, target identification, and tactical reconnaissance missions. The small drone segment is expected to grow at a CAGR of 14.1% during the forecast period from 2026 to 2034, supported by its portability, operational flexibility, and suitability for short-range intelligence and surveillance tasks.
By Application
The military drone market is divided into intelligence, surveillance, and reconnaissance (ISR) and delivery applications. The ISR segment is projected to grow at a CAGR of 12.2% during the forecast period from 2026 to 2034, supported by requirements for situational awareness, threat monitoring, and battlefield intelligence. The delivery segment is expected to grow at a CAGR of 14.4% during the same period, driven by the use of drones to transport military supplies, equipment, and other essential materials.
By Payload
Based on payload capacity, the market includes drones carrying less than 150 kg, between 151 and 1,200 kg, and more than 1,200 kg. The less-than-150-kg segment accounted for a 39.3% share in 2025, reflecting its suitability for lightweight surveillance equipment, compact sensors, and mission-specific payloads. The 151–1,200-kg segment is expected to grow at a CAGR of 12.8% during the forecast period from 2026 to 2034, supported by its capacity to carry heavier mission equipment and specialized military payloads.
By Speed
The market is segmented into subsonic and supersonic drones. The subsonic segment is expected to grow at a CAGR of 12.5% during the forecast period from 2026 to 2034, supported by its suitability for sustained surveillance and reconnaissance missions. The supersonic segment is projected to grow at a CAGR of 15.1% during the same period, driven by military requirements for high-speed operations and rapid responses in time-sensitive missions.
By Wing Type
Based on wing type, the market includes fixed-wing, rotary-wing, and hybrid drones. The fixed-wing segment dominated the market with a share of 55.2% in 2025, owing to its suitability for long-endurance flights, wide-area surveillance, and extended-range reconnaissance. The rotary-wing segment is expected to grow at a CAGR of 13.4% during the forecast period from 2026 to 2034, supported by its ability to take off and land vertically and operate in confined spaces.
By Operation Mode
The military drone market includes remotely piloted, optionally piloted, and fully autonomous systems. Remotely piloted drones accounted for 63.8% of the market in 2025, supported by established remote-control technologies and direct human oversight during military missions. The fully autonomous segment is projected to grow at a CAGR of 16.5% during the forecast period from 2026 to 2034, driven by advances in onboard navigation, automated mission planning, and autonomous flight capabilities.
By Propulsion
Based on propulsion, the market is divided into fuel-powered and battery-powered drones. Fuel-powered drones are expected to grow at a CAGR of 11.5% during the forecast period from 2026 to 2034, supported by their suitability for longer missions and applications requiring sustained flight endurance. The battery-powered segment is projected to grow at a CAGR of 15.2% during the same period, propelled by battery technology improvements, quieter operation, and reduced reliance on conventional fuel systems.
Regional Insights
North America
North America dominated the military drone market with a share of 38.4% in 2025. The region benefits from established defense contractors, advanced aerospace capabilities, and procurement programs focused on surveillance, tactical operations, and autonomous systems. In the United States, the Army launched an unmanned aircraft systems marketplace in 2026 to help military units and government partners compare and order vetted drone technologies. Canada also launched a defense drone initiative focused on developing, testing, adapting, and producing uncrewed and autonomous systems for its armed forces and coast guard. These initiatives could support military drone procurement and domestic defense manufacturing.
Europe
The European military drone market is projected to grow at a CAGR of 12.4% during the forecast period from 2026 to 2034. Defense modernization, autonomous aircraft development, and demand for tactical unmanned systems contribute to regional market activity. The United Kingdom announced a military drone investment exceeding GBP 5 billion over four years, including plans for autonomous armed drones, surveillance drones, and collaborative combat aircraft. Germany has also entered procurement contracts for loitering-munition systems, with planned deployment supporting its defense requirements. These developments highlight the role of government procurement and domestic defense technology capabilities in the European market.
Asia Pacific
Asia Pacific is expected to be the fastest-growing regional market, with a projected CAGR of 14.9% during the forecast period from 2026 to 2034. Defense modernization and investment in unmanned systems support regional demand. Japan allocated approximately JPY 277.3 billion in its fiscal 2026 budget to strengthen unmanned defense capabilities, including ISR, targeting, and research and development. China reported the readiness of a drone-swarm operations system capable of coordinating multiple unmanned aircraft, while India's Defence Acquisition Council approved proposals that included a jet-based kamikaze drone system and an anti-UAV electronic warfare system. These developments reflect regional investment in unmanned platforms and counter-drone capabilities.
Key Players Analysis
The military drone market includes established defense contractors, aerospace manufacturers, unmanned aircraft developers, and specialized defense technology companies. Competition is shaped by flight endurance, payload capacity, surveillance performance, autonomous capabilities, cybersecurity, reliability, and integration with existing military platforms. The major players in this market include:
- Northrop Grumman Corporation
- General Atomics Aeronautical Systems, Inc.
- Israel Aerospace Industries Ltd.
- AeroVironment, Inc.
- Lockheed Martin Corporation
Established companies compete through advanced aircraft platforms, extensive defense relationships, research and development capabilities, and experience with large military contracts. Emerging and specialized manufacturers focus on autonomous flight, artificial intelligence, modular designs, cost-effective platforms, and specialized systems for reconnaissance and tactical operations.
Conclusion
The military drone market is projected to reach USD 63.05 billion by 2034, supported by demand for intelligence, surveillance, reconnaissance, tactical logistics, and autonomous defense technologies. North America held the largest regional share in 2025, while Asia Pacific is expected to record the fastest growth during the forecast period from 2026 to 2034. Cybersecurity threats, signal interference, and complex procurement requirements remain important challenges for industry participants. Continued investment in secure communications, autonomous flight, resilient navigation, and specialized unmanned systems will shape the market's future development.
About Us
Straits Research is a market research and intelligence company that provides market sizing, revenue forecasts, competitive assessments, and strategic insights across multiple industries. Its research helps businesses, investors, and decision-makers understand industry developments, assess competitive positioning, and make informed strategic decisions.
Contact Us
For further information about the military drone market, customized research, or detailed market forecasts, contact Straits Research.
Website: https://straitsresearch.com/
Email: [email protected]
India: +91 8087085354
U.S.: +1 646 905 0080
U.K.: +44 203 695 0070