Germany Electric Vehicle Battery Recycling Market: Closing the Loop on Europe's Electrification Journey
The Germany electric vehicle battery recycling market grew from USD 9.1 Million in 2025 to USD 11.6 Million in 2026. The market is projected to reach USD 57.0 Million by 2034, exhibiting a growth rate (CAGR) of 22.00% during 2026-2034.
 Yadwender Kumar
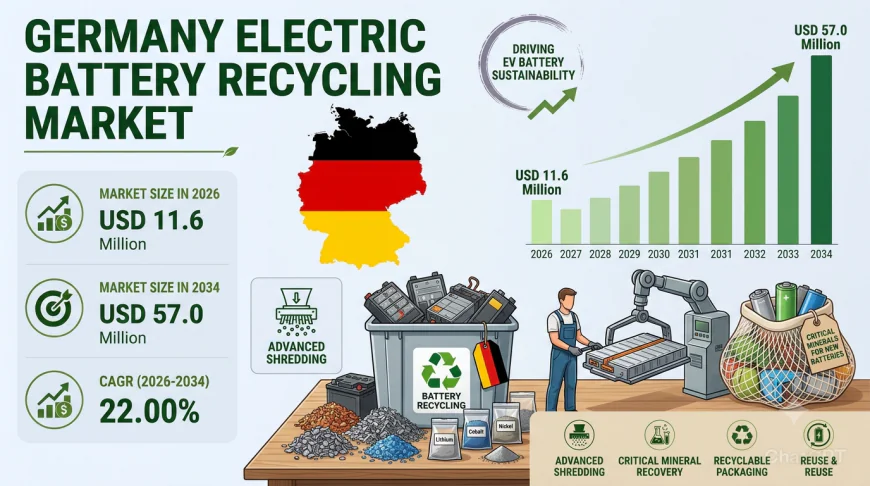
Germany's electric vehicle battery recycling landscape is navigating a period of remarkable transformation. For years, the nation's automotive sector focused on producing the vehicles of the future, but the question of what happens to batteries at end-of-life remained a secondary concern. That has changed with remarkable speed. The electric revolution has arrived with force, and with it comes an urgent need to manage the growing wave of retired batteries. Manufacturers are investing in closed-loop processes, recyclers are scaling operations, and regulators are setting binding targets that leave no room for delay. The Germany electric vehicle battery recycling market is at the epicentre of this shift. Valued at USD 9.1 Million in 2025, the market grew to USD 11.6 Million in 2026 and is projected to reach USD 57.0 Million by 2034, growing at a compound annual rate of 22.00 per cent from 2026 to 2034. These figures reflect an industry entering a new era of circular economy maturity.
What's Driving Growth of Germany's Electric Vehicle Battery Recycling Market?
Stringent EU regulations are mandating higher recycling rates. The German government is imposing tough policies and regulations aimed at driving sustainability and lowering the environmental footprint of the EV sector. Annex XII of the EU Batteries Regulation requires recyclers to meet ambitious recycling efficiency targets by 31 December 2025 — 80 per cent for nickel-cadmium batteries, 75 per cent for lead-acid batteries, 65 per cent for lithium-based batteries, and 50 per cent for other types. By 31 December 2030, the goals will be raised to 80 per cent for lead-acid batteries and 70 per cent for lithium-based batteries. These binding targets are making end-to-end recycling programmes a legal necessity rather than a voluntary choice.
Rapidly expanding EV penetration is creating substantial future waste streams. With more people and companies turning to EVs because of environmental concerns and government incentives, the demand for recycling used batteries is increasing rapidly. This surge is putting pressure on recycling infrastructure to accommodate the volume and complexity of modern batteries. Recyclers and manufacturers are constantly striving to enhance technologies to recover valuable materials such as cobalt, lithium, and nickel, which are essential for manufacturing new batteries. The growth of the EV market is contributing directly to the expansion of the battery recycling market.
Advances in battery recycling technologies are improving efficiency and cost competitiveness. Firms are now working on sophisticated recycling technologies that enhance the effectiveness and efficiency of the process. These include advancements in direct recycling, which enables more material recovery with less energy use. The application of artificial intelligence and automation is also gaining popularity in sorting and processing batteries, enhancing precision. Development of closed-loop recycling systems is picking up pace, allowing for the reuse of key raw materials in battery production without new extraction. As these technologies mature, the cost of recycling is decreasing and recovery rates are rising, making the process more competitive.
Request Sample For PDF Report: https://www.imarcgroup.com/germany-electric-vehicle-battery-recycling-market/requestsample
Three Trends Reshaping the Industry
Automakers are building in-house recycling capacity to close the battery loop.
Mercedes-Benz opened Europe's first battery recycling plant with an integrated mechanical-hydrometallurgical process in Kuppenheim, southern Germany, in October 2024, making it the first car manufacturer worldwide to close the battery recycling loop with its own in-house facility. The plant represents a fundamental shift in how automakers view end-of-life batteries — not as waste to be outsourced, but as a strategic resource to be recovered and reintegrated into production.
The Kuppenheim facility combines mechanical processing with hydrometallurgical refining, achieving a recovery rate of more than 96 per cent for valuable materials including lithium, nickel, and cobalt. This integrated approach allows Mercedes-Benz to maintain control over the entire lifecycle of its batteries, from production through use to recycling and back into new battery cells.
Why it matters: In-house recycling fundamentally changes how automakers must structure their supply chains and sustainability strategies.
Business implication: Manufacturers that fail to invest in recycling capacity risk rising raw material costs and regulatory non-compliance as recycled content requirements tighten.
Future impact: The trend toward closed-loop manufacturing will accelerate as more automakers follow Mercedes-Benz's lead, creating a more resilient and sustainable battery supply chain across Europe.
Specialised recyclers are securing exclusive agreements with premium manufacturers.
Li-Cycle Holdings Corp. announced a new exclusive recycling agreement in January 2025 with a high-performance, luxury electric vehicle manufacturer for battery recycling operations at its Germany Spoke facility. This unique contract involves a luxury vehicle OEM known for high performance and centres on providing Li-Cycle's Germany Spoke with feedstock sourced from Germany.
The agreement reflects a broader trend of specialised recyclers forming strategic partnerships with automakers to secure consistent feedstock streams. As the volume of end-of-life batteries grows, access to high-quality feedstock becomes a competitive advantage. Recyclers that can demonstrate reliable, high-recovery processes are positioning themselves as essential partners in the automotive supply chain.
Why it matters: Exclusive agreements between recyclers and automakers create stable feedstock flows and reduce market uncertainty.
Business implication: Recyclers must invest in advanced recovery technologies and demonstrate compliance with EU regulations to attract premium OEM partnerships.
Future impact: The recycling market will become increasingly consolidated, with a handful of specialised players dominating the landscape and smaller operators struggling to compete.
Hydrometallurgical processes are emerging as the preferred recycling method.
The Germany EV battery recycling market is segmented by process into hydrometallurgical, pyro-metallurgical, and others. Hydrometallurgical recycling is gaining prominence because it offers higher recovery rates for critical materials such as lithium, nickel, and cobalt, while consuming less energy than pyro-metallurgical approaches. The process involves dissolving battery components in chemical solutions to separate and purify valuable metals.
Mercedes-Benz's Kuppenheim plant exemplifies this trend, combining mechanical processing with hydrometallurgical refining to achieve recovery rates exceeding 96 per cent. As regulations tighten and recycled content requirements increase, hydrometallurgical processes are becoming the standard for high-value battery recycling.
Why it matters: The choice of recycling process directly affects recovery rates, energy consumption, and economic viability.
Business implication: Recyclers must invest in hydrometallurgical capabilities to meet EU recovery targets and secure premium feedstock agreements.
Future impact: Hydrometallurgical recycling will become the dominant process for lithium-ion batteries, while pyro-metallurgical methods will be reserved for specific applications and mixed battery streams.
What the Market Numbers Actually Tell Us
A market expanding from USD 9.1 million to USD 57.0 million over nine years suggests significantly greater commercial activity across recyclers, automakers, battery manufacturers, and technology providers. The 22.00 per cent compound annual growth rate signals robust, sustained expansion driven by regulatory mandates, EV fleet growth, and technological advancement.
The lithium-ion segment dominates the type category, reflecting the prevalence of lithium-ion batteries in modern EVs. Passenger cars represent the largest vehicle type segment, consistent with the passenger vehicle dominance in the broader EV market. Electric cars form the primary application segment, followed by electric buses and energy storage systems. Western Germany leads regional demand, reflecting the concentration of automotive manufacturing and recycling infrastructure in the region.
The dual reality of persistent regulatory pressure alongside the emergence of recycling as a strategic industry creates a complex but opportunity-rich environment. While the market remains small in absolute terms compared to the broader EV sector, its growth trajectory is clear and its strategic importance is undeniable.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of technology, regulation, and supply chain integration. The development of closed-loop recycling systems is creating new business models where recovered materials flow directly back into battery production. Artificial intelligence and automation are improving sorting and processing efficiency, reducing costs and increasing recovery rates.
Germany's strong automotive sector provides a unique advantage, with established manufacturers, suppliers, and research institutions collaborating on next-generation recycling technologies. The country's commitment to greenhouse gas neutrality by 2045 and its stringent environmental standards are driving investment in green technologies and sustainable processes.
For companies that can navigate the evolving regulatory environment, invest in advanced recycling technologies, and secure strategic partnerships with automakers, the pathway to sustained growth in Germany's electric vehicle battery recycling market is increasingly clear. The sector's ability to scale operations while maintaining high recovery rates and environmental standards will determine which players emerge as leaders in Europe's circular battery economy.
Recent Industry Developments
Li-Cycle Signs Exclusive Recycling Agreement with Luxury EV Manufacturer (January 2025) — Li-Cycle Holdings Corp. announced a new exclusive recycling agreement with a high-performance, luxury electric vehicle manufacturer for battery recycling operations at its Germany Spoke facility. The contract centres on providing Li-Cycle's Germany Spoke with feedstock sourced from Germany, reinforcing the company's position in the European recycling market.
Mercedes-Benz Opens Europe's First Integrated Battery Recycling Plant (October 2024) — Mercedes-Benz opened Europe's first battery recycling plant with an integrated mechanical-hydrometallurgical process in Kuppenheim, southern Germany, making it the first car manufacturer worldwide to close the battery recycling loop with its own in-house facility. The plant achieves recovery rates exceeding 96 per cent for valuable materials.
EU Batteries Regulation Sets Binding Recycling Efficiency Targets (December 2025) — Annex XII of the EU Batteries Regulation requires recyclers to meet ambitious recycling efficiency targets by 31 December 2025 — 80 per cent for nickel-cadmium batteries, 75 per cent for lead-acid batteries, 65 per cent for lithium-based batteries, and 50 per cent for other types. By 31 December 2030, the goals will be raised to 80 per cent for lead-acid batteries and 70 per cent for lithium-based batteries.
Germany Accelerates EV Adoption, Driving Future Recycling Demand (2025) — Germany's EV fleet continues to expand rapidly, driven by government incentives and consumer demand for sustainable mobility. This growth is creating substantial future waste streams that will require efficient and sustainable recycling solutions, positioning the battery recycling market for sustained expansion.