KYC Explained: Why Verifying Your Customers Protects Your Business
Learn what KYC is, why verifying your customers matters, and how strong identity checks reduce fraud, support compliance and protect your business reputation.
 Alea Consulting
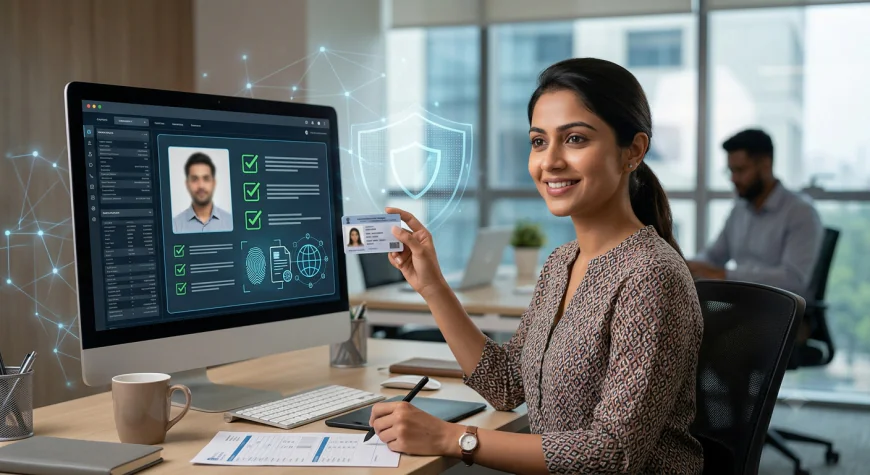
Every business that handles money, contracts, or sensitive data faces the same question: do you really know who you are dealing with? In an era of digital onboarding, cross-border transactions, and rising financial crime, that question has become a core compliance requirement. This guide explains what customer verification involves, why it matters, and how to build a process that is both secure and efficient.
What Is Customer Verification and Why Does It Matter?
Know Your Customer is the process businesses use to confirm the identity of the people and entities they work with, understand their activities, and assess the risks they may pose. Originally a banking requirement, it now applies to fintech firms, insurers, payment providers, real estate agencies, and many other regulated sectors.
The purpose is simple. Criminals use legitimate businesses to launder money, finance terrorism, commit fraud, and evade sanctions. A strong verification process makes it far harder for them to succeed, and it shields your company from legal penalties, financial loss, and reputational damage.
The Cost of Getting It Wrong
Regulators worldwide have issued heavy fines for weak onboarding controls. Beyond penalties, a single compliance failure can lead to lost banking relationships, frozen accounts, and a collapse in customer trust. Prevention is almost always cheaper than remediation.
The Core Components of an Effective Verification Process
A reliable framework generally rests on three pillars. Each one builds on the last, creating layered protection rather than a single checkpoint.
1. Customer Identification
The first step is collecting and validating basic information. For individuals, this typically includes a government-issued ID, proof of address, and date of birth. For companies, it means registration documents, the ownership structure, and details of directors and authorised signatories.
2. Customer Due Diligence
Once identity is confirmed, you evaluate risk. This involves screening against sanctions lists, politically exposed persons (PEP) databases, and adverse media sources. You also need to understand the nature of the relationship: what the customer does, where their funds come from, and what transactions you should expect.
3. Ongoing Monitoring
Verification does not end at onboarding. Customer circumstances change, and so do risk profiles. Continuous transaction monitoring, periodic reviews, and trigger-based checks help you spot unusual behaviour early.
Individuals vs. Businesses: Different Checks for Different Risks
Verifying a private individual is relatively straightforward. Verifying a corporate client is not. Complex structures, layered shareholdings, and offshore entities can hide the real people in control. That is why identifying the ultimate beneficial owner (UBO) is a central part of business onboarding.
Many professionals use the phrase Know Your Client in this context, especially in law, accounting, and advisory services, where relationships are built on trust and long-term engagement. The principle is identical: understand who you serve before and while you serve them.
Going Beyond the Basics: Deeper Due Diligence
Standard checks are sufficient for low-risk customers, but some situations call for a closer look. High-value transactions, clients in high-risk jurisdictions, complex ownership structures, or politically exposed individuals all warrant enhanced scrutiny.
This is where integrity due diligence becomes valuable. It examines a counterparty's reputation, track record, business conduct, and potential links to corruption or misconduct, going beyond what documents alone can reveal. For mergers, partnerships, and major vendor relationships, it can uncover red flags that a routine check would miss.
When to Apply Enhanced Measures
Consider stepping up your review when you encounter:
-
Unclear or overly complicated ownership structures
-
Customers from countries with weak anti-money laundering controls
-
Unexplained sources of wealth or funds
-
Reluctance to provide documentation
-
Transactions inconsistent with the customer's stated profile
Common Challenges Businesses Face
Even well-intentioned companies struggle with verification. Manual document handling slows onboarding and frustrates customers. Fragmented data across departments leads to gaps. Regulations differ between markets and change frequently, making it hard for teams to stay current.
There is also the balance between security and experience. Customers expect fast, frictionless sign-up, yet compliance demands thoroughness. The most successful organisations treat these as complementary goals rather than competing ones.
Best Practices for a Stronger Compliance Framework
-
Adopt a risk-based approach. Apply stricter checks only where risk warrants them, so low-risk customers are not burdened unnecessarily.
-
Automate where possible. Digital ID verification, biometric matching, and automated screening reduce errors and speed up onboarding.
-
Keep records organised. Maintain clear, accessible documentation to support audits and regulatory inquiries.
-
Train your team. Staff should recognise red flags and know how to escalate concerns.
-
Review regularly. Update policies as regulations, technologies, and threats evolve.
How Alea Supports Smarter Compliance
Navigating verification requirements across multiple jurisdictions can be demanding. Alea helps businesses understand regulatory expectations, strengthen their onboarding workflows, and manage risk with greater confidence. By combining regional expertise with practical, tailored guidance, Alea enables organisations to meet their obligations while keeping the customer experience smooth.
Final Thoughts
Customer verification is no longer a box-ticking exercise. It is a strategic safeguard that protects your finances, your reputation, and your relationships. By building a risk-based, well-documented, and continuously monitored process, you reduce exposure to financial crime and create a foundation of trust with the people you serve.