Commercial Fleet Electrification Strengthens EV Charging Infrastructure Demand
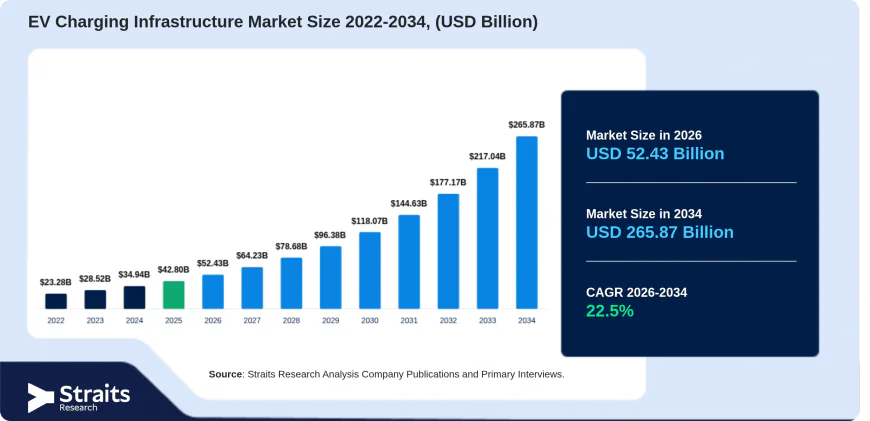
The global ev charging infrastructure market size was valued at USD 42.8 billion in 2025 and is projected to grow from USD 52.43 billion in 2026 to USD 265.87 billion by 2034, registering a CAGR of 22.5% during the forecast period (2026–2034).
 Aditi Jdv
EV Charging Infrastructure Market
The global EV charging infrastructure market size was valued at USD 42.8 billion in 2025 and is projected to grow from USD 52.43 billion in 2026 to USD 265.87 billion by 2034, registering a CAGR of 22.5% during the forecast period (2026–2034). The market is experiencing significant growth as electric vehicle adoption increases across passenger cars, commercial vehicles, and public transportation. Governments, automotive manufacturers, and private infrastructure providers are investing in charging networks to support the transition toward electric mobility. The development of fast-charging technologies, expansion of public charging facilities, and integration of renewable energy are further strengthening the industry's growth prospects.
EV charging infrastructure includes the equipment, software, and supporting systems required to charge electric vehicles. These systems include charging stations, connectors, power management solutions, payment platforms, and network management software. The growing need for accessible charging facilities across residential, commercial, and highway locations is encouraging infrastructure investments. Additionally, improvements in battery technology and the introduction of electric vehicle models with longer driving ranges are increasing the importance of reliable and widely available charging networks.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/ev-charging-infrastructure-market
EV Charging Infrastructure Market Drivers
Rising Electric Vehicle Adoption and Government Support
The increasing adoption of electric vehicles is a major factor driving the EV charging infrastructure market. Growing environmental awareness, fuel cost considerations, and government initiatives promoting zero-emission transportation are encouraging consumers and businesses to shift toward electric mobility. As the number of electric passenger cars, buses, and commercial vehicles increases, the need for accessible charging facilities is becoming more important.
Governments across major economies are introducing financial incentives, emission regulations, and infrastructure development programs to accelerate electric vehicle adoption. These initiatives are encouraging private companies, utilities, and charging network operators to invest in residential and public charging facilities.
Growing Investments in Fast-Charging and Smart Charging Technologies
Technological advancements in fast-charging systems are supporting the development of efficient charging networks. DC fast chargers reduce charging time and improve convenience for drivers, particularly along highways and major transportation routes. Smart charging technologies also allow operators to monitor electricity consumption, manage charging schedules, and optimize energy distribution.
Furthermore, the integration of renewable energy sources and battery storage systems is improving charging station efficiency. These developments are encouraging infrastructure providers to introduce advanced charging solutions for residential, commercial, and fleet applications.
EV Charging Infrastructure Market Challenges
High Installation Costs and Grid Capacity Constraints
The high initial investment required to establish EV charging stations remains a major challenge. Charging equipment, electrical connections, land acquisition, installation, and maintenance contribute to overall infrastructure costs. High-power charging stations require additional investments in transformers, substations, and distribution networks, which can increase project expenses.
Limited grid capacity in certain locations also restricts the deployment of high-power charging facilities. Infrastructure providers may need to upgrade existing electrical systems before installing fast-charging stations, increasing project timelines and operational costs.
Interoperability Issues and Regulatory Complexities
Differences in charging connectors, communication protocols, payment systems, and network management platforms create interoperability challenges. EV users may experience difficulties accessing charging facilities operated by different service providers. These inconsistencies can affect charging convenience and network utilization.
Additionally, lengthy permitting procedures, utility connection approvals, and varying regional regulations can delay infrastructure projects. Charging network operators must coordinate with multiple authorities and utilities, increasing the complexity of infrastructure deployment.
EV Charging Infrastructure Market Segmentation
The EV charging infrastructure market is segmented by charger type, connector type, installation type, charging level, and end user.
By Charger Type
The market is categorized into AC charging, DC fast charging, and wireless charging.
-
DC Fast Charging: The DC fast charging segment dominated the market with a share of 61.8% in 2025. Its ability to deliver high charging power within shorter periods makes it suitable for public charging stations, highways, and commercial transportation. Increasing demand for convenient charging facilities is supporting its leading position.
-
AC Charging: AC charging systems are widely used in residential properties, workplaces, and commercial parking facilities. Their relatively lower installation costs and suitability for longer parking durations support widespread adoption.
-
Wireless Charging: The wireless charging segment is projected to grow at a CAGR of 29.3% during the forecast period. Advancements in inductive charging technologies and increasing interest in cable-free charging solutions are supporting its growth.
By Connector Type
The market includes CCS (Combined Charging System), CHAdeMO, GB/T, NACS (North American Charging Standard), and others.
-
CCS (Combined Charging System): This segment accounted for 49.7% of the market share in 2025. Its compatibility with AC and DC charging and widespread adoption across public charging networks support its dominance.
-
NACS (North American Charging Standard): This segment is expected to grow at a CAGR of 31.5% during the forecast period. Increasing adoption by automotive manufacturers and charging network operators is supporting the expansion of compatible charging facilities.
-
CHAdeMO and GB/T: These connector standards support EV charging across different regional markets. Their adoption is influenced by local automotive manufacturing, charging infrastructure requirements, and established technical standards.
-
Others: Other connector technologies contribute to the market by supporting specialized charging requirements and emerging vehicle platforms.
By Installation Type
The market is divided into residential, commercial, and public installations.
-
Public: The public segment accounted for 56.2% of the market share in 2025. Investments in highway charging corridors, urban charging hubs, and publicly accessible charging facilities support its leading position.
-
Commercial: The commercial segment is anticipated to grow at a CAGR of 27.8% during the forecast period. Increasing installation of charging stations at workplaces, shopping centers, hotels, and fleet depots is supporting its growth.
-
Residential: Residential charging infrastructure is gaining importance as private EV ownership increases. Home charging facilities provide convenience and allow vehicle owners to charge their vehicles during extended parking periods.
By Charging Level
The market is segmented into Level 1, Level 2, and Level 3 (DC Fast Charging).
-
Level 2: This segment dominated the market with a share of 47.5% in 2025. Its balance between charging speed, installation costs, and suitability for residential and commercial applications supports its adoption.
-
Level 3 (DC Fast Charging): This segment is expected to grow at a CAGR of 30.4% during the forecast period. Increasing demand for rapid charging facilities across highways and commercial transportation networks is supporting its growth.
-
Level 1: Level 1 charging systems are primarily used in residential settings where vehicles can remain connected for extended periods.
By End User
The market is categorized into private EV owners, commercial fleet operators, charge point operators, and others.
-
Private EV Owners: This segment accounted for 54.3% of the market share in 2025, supported by increasing electric passenger vehicle ownership and demand for residential charging facilities.
-
Commercial Fleet Operators: This segment is expected to grow at a CAGR of 28.9% during the forecast period. The electrification of delivery vehicles, buses, and logistics fleets is increasing the need for dedicated charging depots.
-
Charge Point Operators: These operators manage charging networks and provide charging services to individual and commercial customers.
-
Others: Other end users include organizations and institutions investing in dedicated charging infrastructure for their transportation requirements.
EV Charging Infrastructure Market Regional Insights
Asia-Pacific dominated the EV charging infrastructure market with a share of 55.6% in 2025. The region benefits from high electric vehicle adoption, extensive charging network deployment, and strong government support for clean transportation. China represents a major contributor due to its large electric vehicle fleet and established public charging ecosystem. India, Japan, and South Korea are also investing in charging networks to support electric mobility.
Europe is expected to be the fastest-growing regional market, registering a CAGR of 28.4% during the forecast period. Stringent emission regulations, increasing electric vehicle adoption, and investments in public fast-charging corridors are supporting regional growth. Germany, France, and the U.K. are important markets due to their expanding charging networks and transportation electrification initiatives.
North America is experiencing increasing investments in public charging stations, residential charging systems, and commercial fleet infrastructure. The U.S. and Canada are strengthening charging networks through government initiatives, private-sector participation, and investments in advanced charging technologies.
Latin America, the Middle East, and Africa are gradually developing their EV charging ecosystems. In Latin America, Brazil, Mexico, and other emerging economies are investing in electric mobility and charging facilities. Meanwhile, the Middle East is focusing on sustainable transportation initiatives and smart city infrastructure. South Africa and other African markets are exploring charging network development to support the gradual adoption of electric vehicles.
EV Charging Infrastructure Market Key Players Analysis
The global EV charging infrastructure market is moderately fragmented, with competition among electrical equipment manufacturers, charging network operators, energy companies, and technology providers. Leading companies are focusing on fast-charging technologies, smart charging software, network connectivity, and advanced energy management solutions. Strategic partnerships, product launches, and infrastructure investments are important approaches used by companies to strengthen their competitive positions.
The major companies operating in the global EV charging infrastructure market include:
-
ABB
-
Siemens AG
-
Schneider Electric SE
-
ChargePoint Holdings, Inc.
-
Tesla, Inc.
-
Blink Charging Co.
-
EVBox
-
Wallbox N.V.
-
Tritium DCFC Limited
-
Delta Electronics, Inc.
-
Star Charge
-
Alpitronic GmbH
-
Webasto Group
-
Leviton Manufacturing Co., Inc.
-
bp pulse
-
Efacec Power Solutions
-
SK Signet
-
Autel Energy
These companies are investing in high-power charging equipment, commercial fleet solutions, and integrated charging management platforms. Their focus on technological improvements, charging network accessibility, and energy efficiency is expected to influence competitive positioning across the industry.
Conclusion
The global EV charging infrastructure market is expected to experience substantial growth during the forecast period, supported by increasing electric vehicle adoption, government initiatives, and investments in charging networks. The dominance of DC fast charging, CCS connectors, public installations, and private EV owners highlights the importance of accessible and efficient charging solutions. Meanwhile, wireless charging, commercial installations, and fleet electrification are creating additional growth opportunities.
Asia-Pacific's leading market position and Europe's projected growth reflect the increasing importance of regional infrastructure investments. However, high installation costs, grid limitations, interoperability issues, and regulatory complexities remain important challenges. Companies focusing on fast-charging technologies, smart energy management, and commercial charging solutions are well-positioned to benefit from the industry's development.
About Us
Straits Research is a leading market research and intelligence organization specializing in research, analytics, and advisory services. The company provides comprehensive market reports, industry insights, and strategic business intelligence across multiple industries, helping organizations identify growth opportunities and make informed business decisions.
Contact Us
Email: [email protected]
Tel: +1 646 905 0080 (U.S.)
Tel: +44 203 695 0070 (U.K.)