GCC Renewable Energy Market Size, Share, Growth, and Forecast 2026-2034
The GCC renewable energy market size reached 18.2 GW in 2025. Looking forward, IMARC Group estimates the market to reach 45.8 GW by 2034, exhibiting a CAGR of 10.49% from 2026-2034.
 jackleen jackleen
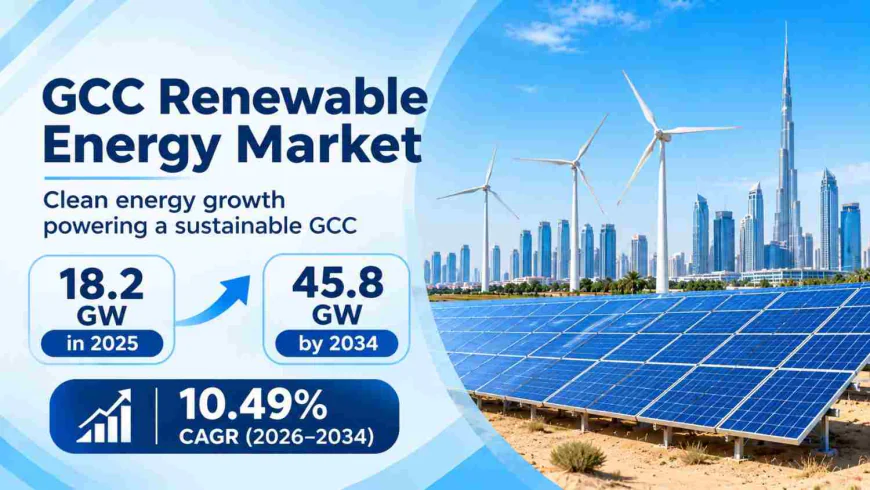
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the GCC Renewable Energy Market. The GCC renewable energy market size reached 18.2 GW in 2025 and is projected to reach 45.8 GW by 2034, exhibiting a CAGR of 10.49% during 2026-2034, with the UAE currently leading at a 45% share. The market is primarily driven by large-scale green hydrogen projects, the ongoing integration of smart grids, continual advancements in energy storage, government-led collaborations, financial incentives, the deployment of renewable energy in industrial sectors, public-private partnerships and a growing focus on decarbonization.
The GCC is turning its solar and wind advantage into a power system for the post-hydrocarbon era, anchored by Saudi Vision 2030, the UAE Energy Strategy and Net Zero 2050 and national visions across the region. Solar dominates the mix, backed by some of the lowest-cost tenders in the world, while battery storage, smart grids and green hydrogen are widening what renewable power can do, from round-the-clock supply to powering steel, petrochemicals and exports. Developers such as ACWA Power and Masdar, state-backed funds such as PIF's Badeel, and a wave of commercial and industrial solar companies are raising record financing, with Masdar and EWEC reaching financial close in July 2026 on a USD 6.1 billion project that combines 5.2 GW of solar with 19 GWh of battery storage. At the same time, the picture is uneven: published estimates of installed capacity vary widely across sources, announced gigawatts are not the same as committed investment, and some giga-project timelines have been reprioritized, while grid integration, storage and skilled workforce needs remain challenges. Combined with green finance and strategic international partnerships, these forces are shaping a durable, long-term growth path across Saudi Arabia, the UAE, Qatar, Kuwait, Oman, and Bahrain.
GCC Renewable Energy Market at a Glance:
- Market Size (2025): 18.2 GW
- Market Forecast (2034): 45.8 GW
- Growth Rate (2026-2034): CAGR of 10.49%
- Base Year: 2025 | Historical Period: 2020-2025 | Forecast Period: 2026-2034
- Leading Type Segment: Solar Power, the largest segment, driven by high solar radiation, cost-competitive photovoltaic technology, and government-backed large-scale installations
- Leading Country Market: UAE, commanding a 45% share in 2025, according to the report, supported by strategic investments, abundant resources, and ambitious national initiatives
How AI is Reshaping the Future of the GCC Renewable Energy Market
- DEWA's AI-Native Smart Grid: Dubai Electricity and Water Authority announced in December 2024 an AED 7 billion (USD 1.91 billion) smart grid program running to 2035, which delivers electricity losses of 2% and water losses of 4.6% and supports automated grid restoration and real-time monitoring of solar and wind power, and its Distribution Network Smart Centre processes more than 15 million data points a day using AI, big data and machine learning.
- Software-Controlled Solar Tracking: A study published at Bahrain Polytechnic in March 2024, cited in the report, found that a moving photovoltaic panel controlled by GPS and software produced 33% more energy annually than a fixed panel, and 54.7% more in June when cooling demand peaks.
- Storage and Dispatchable Renewable Power: Masdar and the Emirates Water and Electricity Company reached financial close in July 2026 on a USD 6.1 billion round-the-clock renewable project in Abu Dhabi, combining 5.2 GW of solar PV with 19 GWh of battery storage, a scale of storage that depends on software-managed dispatch to turn intermittent sunshine into firm supply.
Grab a sample PDF of this report: https://www.imarcgroup.com/gcc-renewable-energy-market/requestsample
GCC Renewable Energy Market Trends and Drivers:
Demand for renewable energy across the GCC is being underpinned by the integration of smart grids and energy storage. The GCC is investing heavily in smart grid technologies and advanced storage systems that improve efficiency and reliability, with DEWA's smart grid program targeting dynamic energy management and real-time monitoring of solar and wind power. Coupled with large-scale battery storage, these advancements address intermittency and support renewable goals, and Saudi Arabia's national battery storage target of 48 GWh by 2030 shows how storage is becoming central to the build-out.
The region's structural differentiator is scale and finance. MENA attracted a record USD 22 billion of renewable investment in 2025 according to GreentechLead, and ACWA Power, PIF's Badeel and Aramco subsidiary SAPCO reached financial close on seven projects totaling 15 GW and USD 8.2 billion, including five solar projects of 12 GW and two wind projects of 3 GW. Saudi Arabia's Vision 2030 targets 50% of power from renewables by 2030, and estimates of installed capacity differ widely by source, from about 12 GW at the end of 2025 to 18.8 GW reported for August 2026 against a goal of 20 GW by year-end, so the pace of installation remains a key watch point.
A third driver is industrial decarbonization and green hydrogen. The GCC is decarbonizing energy-intensive industries such as petrochemicals, aluminum and steel, with renewable-powered industrial clusters such as Saudi Arabia's Industrial Renewable Energy Initiative, and the NEOM Green Hydrogen Project, which will combine 4 GW of renewable energy to produce 600 tonnes of hydrogen a day, was described by Air Products in February 2025 as approaching 80% completion with green ammonia production expected to begin at the end of 2026, a dynamic that is set to intensify over the coming decade.
Government Schemes and National Energy Programs Driving Demand:
- Saudi Vision 2030 and the National Renewable Energy Program: Saudi Arabia aims to source 50% of its power from renewable energy by 2030, equal to about 130 GW including 58.7 GW of solar and 40 GW of wind, with tenders run by the Saudi Power Procurement Company and a 2026 pipeline that includes Round 7 with an indicated target of about 14 GW of awards across solar and wind.
- UAE Energy Strategy 2050 and Net Zero 2050: The UAE Energy Strategy 2050 aims for a 50% clean energy mix by mid-century across solar, wind and nuclear power, the Mohammed bin Rashid Al Maktoum Solar Park is set to reach 5 GW by 2030, and Masdar targets a 100 GW portfolio by 2030 and raised USD 1 billion in a green bond in July 2024 that was 4.6 times oversubscribed.
- Kuwait's Renewable and Hydrogen Masterplan: On 18 July 2024, KBR and Kuwait Oil Company agreed to create a masterplan for 17 GW of renewable energy and 25 GW of green hydrogen by 2050, including phased wind, solar and storage integration, feasibility studies and workforce training.
- Industrial Renewable Energy and Green Hydrogen Programs: Saudi Arabia's Industrial Renewable Energy Initiative and projects such as NEOM Green Hydrogen, together with the UAE's hydrogen ambitions, are fostering renewable-powered industrial clusters and export hubs, backed by public-private partnerships.
- Green Finance and International Partnerships: Green bonds, sustainable loans and partnerships support the build-out, with ACCIONA securing EUR 300 million of sustainable financing in October 2024 for GCC renewable energy, efficiency and water projects, and the EU-GCC Cooperation on Green Transition launched in April 2024 promoting knowledge sharing and technology transfer.
GCC Renewable Energy Market Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Type:
- Hydropower
- Wind Power
- Solar Power
- Bioenergy
- Geothermal Energy
- Others
Solar power dominates the market, given the region's high solar radiation, which makes it one of the best regions in the world for solar potential, supported by declining photovoltaic costs, large-scale installations such as the Mohammed bin Rashid Al Maktoum Solar Park, energy storage integration and concentrated solar power systems, while wind, bioenergy and other sources add diversity, as in waste-to-energy projects in Abu Dhabi and wind farms such as Dumat Al Jandal in Saudi Arabia.
Breakup By Application:
- Residential
- Commercial
- Industrial
Residential adoption is gaining momentum through rooftop solar, net metering policies, subsidies and home storage, commercial establishments such as malls, offices and hotels use solar rooftops and on-site generation to cut operating costs and meet sustainability goals, and the industrial sector relies on gigascale solar and wind farms and green hydrogen to decarbonize petrochemicals, manufacturing and steel.
Breakup By Country:
- Saudi Arabia
- UAE
- Qatar
- Kuwait
- Oman
- Bahrain
The UAE leads the market with a 45% share in 2025, according to the report, on the back of strategic investments, abundant resources and ambitious national initiatives, with Dubai's solar park, Abu Dhabi's Masdar and large storage projects. Saudi Arabia is scaling rapidly with vast solar and wind resources, PIF backing and public-private partnerships, targeting 130 GW by 2030, while Qatar, Kuwait, Oman and Bahrain advance through national programs, including Kuwait's 2050 renewable and hydrogen masterplan.
Competitive Landscape:
The GCC renewable energy market is very competitive, driven by significant investments, supportive government policies and a strong focus on sustainability, with continual technological advancements, cost reduction and strategic partnerships shaping the competitive dynamics. The report provides a comprehensive analysis of the competitive landscape, with detailed profiles of all major companies, including:
- MACE Group
- Enerwhere Sustainable Energy DMCC
- Akuo Energy SAS
- Yellow Door Energy Limited
- Masdar (Abu Dhabi Future Energy Co.)
- Canadian Solar Inc.
- Siraj Power Contracting LLC
- ACWA POWER BARKA SAOG
- ACWA Power
- EDF Renewables
This is a partial list of the key players, and the complete list is provided in the report. Utility-scale developers such as Masdar and ACWA Power lead gigawatt-scale projects, commercial and industrial specialists such as Enerwhere and Yellow Door Energy serve businesses, global players such as Canadian Solar, Akuo and EDF Renewables bring technology and financing, and MACE Group manages large developments such as the renewable-powered King Salman International Airport project.
Market Concentration Analysis:
- The GCC renewable energy market is concentrated at the utility scale around a few state-backed developers, with ACWA Power reporting a Saudi solar and wind portfolio of more than 34 GW across 21 projects and PIF's Badeel and its partners sponsoring projects totaling 28.6 GW, according to GreentechLead, alongside Masdar, which targets a 100 GW portfolio by 2030, reflecting the capital intensity and government anchoring of utility-scale procurement.
- Fragmentation increases among commercial and industrial solar providers, EPC contractors, equipment suppliers and storage integrators, where companies such as Enerwhere, Yellow Door Energy, Siraj Power Contracting, Canadian Solar and others compete for rooftop, on-site and mid-scale projects, creating a structure where state-backed champions dominate gigawatt-scale tenders while specialists serve businesses and niche applications.
- Financing and partnerships are shaping the competitive balance, exemplified by the USD 8.2 billion financial close for 15 GW by ACWA Power, Badeel and SAPCO, the USD 6.1 billion Masdar and EWEC solar-plus-storage project, and green financing such as Masdar's USD 1 billion green bond and ACCIONA's EUR 300 million sustainable loan.
What Does The Full Report Cover?
- Historical, current, and forecast market size for the GCC renewable energy market from 2020 to 2034
- Market breakup by type, application, and country
- Country-level analysis covering Saudi Arabia, UAE, Qatar, Kuwait, Oman, and Bahrain
- Key growth drivers, challenges, and opportunities shaping the market
- Porter's Five Forces analysis and value chain assessment
- Competitive landscape, market structure, and player positioning
- Detailed profiles of major renewable energy companies in the GCC
Recent News and Developments in the GCC Renewable Energy Market
- August 2026: Saudi Arabia's Ministry of Energy was reported to have put installed renewable capacity at 18.8 GW, about 1.2 GW short of its goal of 20 GW by the end of 2026, according to MEES as cited by a secondary source, while other trackers show lower figures.
- July 2026: Masdar and the Emirates Water and Electricity Company reached financial close on a USD 6.1 billion round-the-clock renewable project in Abu Dhabi combining 5.2 GW of solar PV with 19 GWh of battery energy storage.
- June 2026: Air Products announced that it is finalizing a marketing and distribution agreement with Yara for renewable ammonia from the NEOM Green Hydrogen Project in Saudi Arabia.
- 2025: ACWA Power, PIF's Badeel and Aramco subsidiary SAPCO reached financial close on seven projects representing 15 GW and USD 8.2 billion of investment, including five solar projects totaling 12 GW and two wind projects totaling 3 GW.
- February 2025: Air Products said the NEOM green hydrogen project was approaching 80% completion, with green ammonia production expected to start at the end of 2026.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- How big is the GCC renewable energy market and what is its growth outlook through 2034?
- What are the key growth drivers, challenges, and opportunities in the GCC renewable energy market?
- Which type, application, and country hold the largest share of the market?
- How are smart grids, energy storage, and green hydrogen shaping the market?
- How are government strategies, incentives, and public-private partnerships influencing deployment?
- Who are the key players in the GCC renewable energy market, and how is the competitive landscape evolving?
- What role are industrial decarbonization and green finance playing in the future of GCC renewable energy?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104