UK Autonomous Vehicles Market Size, Share, Trends, Growth & Forecast Report 2026-2034
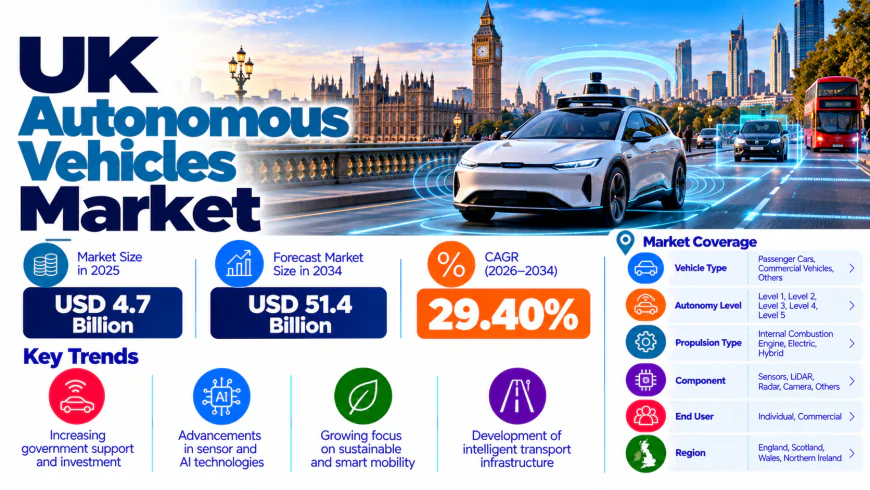
The UK autonomous vehicles market size reached USD 4.7 Billion in 2025 and is expected to reach USD 51.4 Billion by 2034, at a CAGR of 29.40%.
 Arlo Bennett
Market Overview
The UK autonomous vehicles market size reached USD 4.7 Billion in 2025 and is projected to reach USD 51.4 Billion by 2034, growing at a compound annual growth rate (CAGR) of 29.40% from 2026 to 2034. The market is driven by advances in artificial intelligence and machine learning, government support for innovation, and a legal framework for testing and deployment through the Automated Vehicles Act. Demand for smart mobility, goals to reduce traffic congestion and emissions, and strong research and development investment are further supporting market expansion.
UK Autonomous Vehicles Market Summary
- The UK autonomous vehicles market encompasses the hardware, software, and services used to build and operate self-driving vehicles at higher levels of automation, for transportation and logistics and for military and defense uses.
- Autonomous vehicles are valued for improving road safety, supporting smart mobility, reducing congestion and emissions, and enabling new passenger and freight services.
- The ecosystem includes AI and software developers, sensor and hardware suppliers, vehicle manufacturers, mobility platforms, transport authorities, regulators, research institutions, and passengers.
- Major segments identified in the market include component (hardware, software, and services), level of automation (Level 3, Level 4, and Level 5), application (transportation and logistics, and military and defense), and region.
- The Automated Vehicles Act became law on 20 May 2024, requiring self-driving vehicles to meet at least the safety level of careful, competent human drivers, along with rigorous pre-deployment checks.
- The market is benefiting from deep learning, high-resolution LiDAR, radar, computer vision, and edge AI, along with smart road infrastructure and connected traffic management.
- The page cites an industry worth up to £42 billion and 38,000 additional skilled jobs by 2035.
- In September 2026, Wayve and Uber launched supervised autonomous rides in London, described as the first autonomous trips available in the United Kingdom.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/uk-autonomous-vehicles-market
Porter’s Five Forces Analysis
- Competitive Rivalry: High, with UK start-ups, global technology companies, and automakers competing on AI capability, safety record, and partnerships. Business implication: Companies must differentiate through safety evidence, technology performance, and strong commercial partnerships.
- Supplier Power (Sensors, Chips, and Data): High. Advanced sensors, computing hardware, and mapping or training data come from a limited number of suppliers, giving them leverage over developers. Business implication: Developers should diversify hardware suppliers and invest in their own AI and software capabilities.
- Buyer Power (Mobility Platforms and Fleet Operators): High. Large platforms such as ride-hailing companies and fleet operators control access to riders and can choose between competing technology partners. Business implication: Developers should build flexible partnerships and demonstrate clear economic and safety benefits.
- Threat of Substitutes: Moderate. Conventional taxis, buses, and driver-assist features can substitute for fully autonomous services, and public trust and cybersecurity concerns could slow adoption. Business implication: Gradual rollout with safety drivers and transparent public engagement can build confidence.
- Threat of New Entrants: Moderate. High capital requirements, regulatory approval, and safety assessments limit entry, but well-funded global players are expanding into the UK. Business implication: New entrants should partner with established operators and focus on specific use cases such as logistics, buses, and shuttles.
Market Growth Drivers
Advances in AI and Sensing Technology
Deep learning, neural networks, high-resolution LiDAR, radar, computer vision, and predictive analytics are improving how vehicles perceive and respond to their surroundings. Edge AI supports faster decisions on the vehicle itself. These advances are making higher levels of automation more practical and commercially viable.
Government Support and a Legal Framework
The Automated Vehicles Act gives the UK a framework for testing and deploying self-driving vehicles, and the government is developing further regulations. Government pilots and public-private partnerships support innovation and provide real-world evidence. Favorable regulation helps attract investment and positions the UK as a hub for advanced vehicle technologies.
Demand for Smart Mobility and Safety
Cities and operators are looking for ways to reduce congestion and emissions and to improve road safety. The page links human error to 88% of road collisions, and automation is expected to reduce it. Smart road infrastructure, connected traffic management, and real-time data networks are being expanded to support these goals.
UK Autonomous Vehicles Market Segmentation
Component Insights:
- Hardware
- Software
- Services
Level of Automation Insights:
- Level 3
- Level 4
- Level 5
Application Insights:
- Transportation and Logistics
- Military and Defense
Regional Insights:
- London
- South East
- North West
- East of England
- South West
- Scotland
- West Midlands
- Yorkshire and The Humber
- East Midlands
- Others
Competitive Landscape
The UK autonomous vehicles market features AI and software developers, automakers, mobility platforms, and specialist vehicle makers. Competition centers on AI performance, safety validation, regulatory approval, and the ability to partner with platforms and fleet operators. Global technology companies are also moving into the UK, increasing competition with domestic developers.
Regional Analysis
- London & South East: The leading market for passenger services, with Wayve and Uber’s supervised rides now live across London and Waymo planning its own launch, supported by high population density and strong investor and operator presence.
- East of England: A pilot region for autonomous buses, with the Greater Cambridge Partnership’s self-driving bus “Connector” project in Cambridge.
- North West, Yorkshire and The Humber & East Midlands: Regions with strong automotive and logistics activity that offer potential for autonomous freight, depots, and shuttle applications.
- West Midlands & South West: Important automotive and engineering regions that support testing, component supply, and vehicle development.
- Scotland: A distinct market with its own transport policies and long-distance and rural routes where autonomous services could be tested.
Recent Industry Developments
September 2026: Uber introduced the UK's first public-facing robotaxi service in London using 15 Ford Mustang Mach-E electric vehicles equipped with autonomous driving technology developed by British company Wayve. The vehicles initially operated with human safety drivers, who could intervene when necessary. Passengers booking standard Uber journeys could choose whether to accept a robotaxi when offered. The launch represented an important step towards commercial autonomous passenger services, although fully driverless operation remained subject to further regulatory approvals.
August 2026: Plans for fully driverless robotaxis in London faced delays as regulatory guidance and vehicle certification requirements remained outstanding. Transport for London had not yet issued the necessary operator guidance, and vehicles had not completed the required approval process for driverless services. Companies including Uber, Wayve, Waymo, and Baidu were preparing or testing autonomous mobility services, highlighting both the commercial potential of the technology and the importance of establishing clear safety and operational requirements.
July 2026: The UK government published its response to a consultation on protecting marketing terms for automated vehicles. The initiative addressed the risk of manufacturers and businesses describing vehicles as self-driving when they only offer driver-assistance features. Clear terminology is important to ensure that motorists understand their responsibilities and do not mistakenly assume that a vehicle can operate without human supervision. The proposed approach forms part of the wider regulatory framework established by the Automated Vehicles Act 2024.
Key Aspects Required for the UK Autonomous Vehicles Market
- Market Performance: USD 4.7 Billion in 2025, with a projected trajectory to USD 51.4 Billion by 2034.
- Market Outlook: A 29.40% CAGR through 2034 indicates very rapid growth across components, automation levels, and applications.
- Growth Drivers: Advances in AI and machine learning, government support and a legal framework, demand for smart mobility, goals to reduce congestion and emissions, research and development investment, and partnerships between technology firms and automakers.
- Competitive Landscape: A mix of AI developers, automakers, mobility platforms, and specialist vehicle makers, with global technology companies entering the UK.
- Challenges: Concerns about public trust and cybersecurity, which public consultations and awareness campaigns aim to address, and the need for further regulation before fully driverless operation.
- Industry Trends: The Automated Vehicles Act and its safety standard, advances in deep learning and sensing, smart road infrastructure and connected traffic management, and public-private and academic collaboration.
- Strategic Recommendations: Build partnerships with mobility platforms and fleet operators; demonstrate safety through supervised pilots and transparent evidence; target logistics, buses, and shuttle applications; invest in AI, sensing, and cybersecurity; and use the UK’s regulatory framework to attract international investment.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide it as part of customization.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=31341&flag=C
Report Format, Delivery, and Customization Details
- Report Format Mode: PDF and Excel (editable version in PPT/Word format available on special request)
- Report Delivery Mode: Online delivery via email
- Report Customization Mode: Yes, via email/call (10% free customization for a single user license, 15% for a five user license, and 20% for a corporate user license)
- Analyst Support: 10–12 weeks for a single user license
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request for Sample Report: Yes