Data Center Server Market Size, Share, Trends, Growth Factors and Forecast 2026-2034
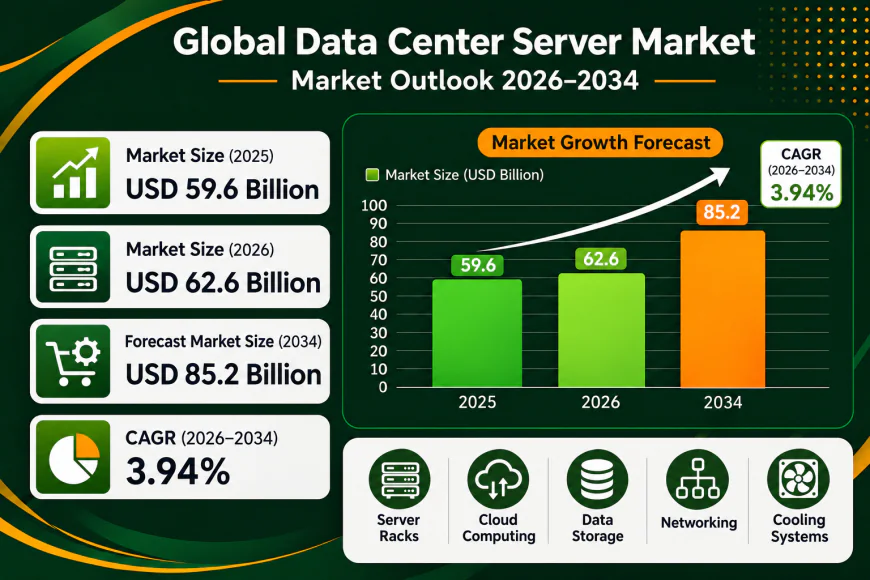
The global data center server market grew from USD 59.6 Billion in 2025 to USD 62.6 Billion in 2026 and is projected to reach USD 85.2 Billion by 2034, expanding at a CAGR of 3.94% during 2026-2034.
 marketinsights
IMARC Group has recently released a new research study titled "Data Center Server Market Size, Share, Trends and Forecast by Product, Application, and Region, 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
Data Center Server Market Size & Share 2026-2034
The global data center server market grew from USD 59.6 Billion in 2025 to USD 62.6 Billion in 2026 and is projected to reach USD 85.2 Billion by 2034, expanding at a CAGR of 3.94% during 2026-2034. In 2026, the market continues to gain momentum, shaped by accelerating AI and machine learning workload deployments by hyperscalers and enterprises, rapid cloud-native application proliferation, and escalating global digital transformation programs.
Rack servers dominated the product mix at 46.5% in 2025, while commercial servers led the application segment at 64.3%. North America held the largest regional share at 38.7% in 2025, reflecting its concentration of hyperscalers and sustained enterprise IT investment. These dynamics are expected to strengthen the global data center server market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 59.6 Billion
- Market Size (2026): USD 62.6 Billion
- Projected Market Size (2034): USD 85.2 Billion
- Growth Rate: CAGR of 3.94% (2026-2034)
Explore Opportunities in the Global Data Center Server Market: Download the IMARC Sample Report: https://www.imarcgroup.com/data-center-server-market/requestsample
Key Growth Drivers and Trends in the Data Center Server Market
Growth in the global data center server market is being driven primarily by the explosion of AI and machine learning workloads. According to Dell’s Oro Group, worldwide data center capital expenditures increased 57% in 2025, with the top four US cloud service providers expanding capex by 76%, driven almost entirely by AI infrastructure investment that requires GPU-dense rack and blade server deployments at unprecedented scale. Gartner estimates that worldwide datacenter systems spending rose 46.8% to USD 489.5 Billion in 2025, reflecting broad enterprise adoption of hybrid cloud, real-time analytics, and AI-powered automation.
One of the leading global data center server market trends is the shift from general-purpose compute to AI-optimized server architectures featuring NVIDIA Blackwell, AMD Instinct MI300X, and Intel Gaudi3 accelerators. According to IDC, revenue from servers with embedded GPUs grew 49.4% year-over-year in Q3 2025 and accounted for over half of total server market revenue. At the same time, a hyperscale expansion supercycle is creating durable, multi-year server demand, with JLL projecting nearly 100 GW of new data center capacity to be added globally between 2026 and 2030.
Another key factor supporting data center server market growth is the spread of edge computing and liquid cooling. Real-time AI inference, autonomous vehicles, smart manufacturing, and 5G-connected IoT systems are pushing servers beyond centralized hyperscale campuses, favoring micro servers and compact rack configurations. Meanwhile, modern AI racks drawing 100 kW or more per rack require direct liquid cooling, making liquid cooling-ready architectures a standard design requirement and creating a large server replacement opportunity.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=1131&flag=C
Global Data Center Server Industry Segmentation Insights
Breakup by Product:
- Rack Servers: The leading product segment at 46.5% in 2025, valued for compute density, GPU compatibility, and use across hyperscale and enterprise deployments.
- Blade Servers: Accounted for 24.8% in 2025, offering resource consolidation for virtualized enterprise environments.
- Micro Servers: Accounted for 15.6% in 2025 and the fastest-growing product segment at about 5.1% CAGR, driven by edge computing and distributed AI inference.
- Tower Servers: Stand-alone servers used in smaller deployments and edge environments.
Breakup by Application:
- Commercial Servers: The leading application at 64.3% in 2025, driven by hyperscale cloud operators, financial services, e-commerce, and SaaS providers.
- Industrial Servers: Accounted for 35.7% in 2025, serving manufacturing automation, process control, energy grid management, and smart city applications.
Breakup by Region:
- North America: The largest region at 38.7% in 2025, supported by hyperscaler concentration and enterprise IT modernization.
- Europe: Accounted for 24.5% in 2025, driven by sovereign cloud mandates, EU AI Act compliance, and Industry 4.0 digitalization.
- Asia Pacific: Accounted for 22.8% in 2025, supported by China’s hyperscale buildout, India’s digital infrastructure program, and ASEAN cloud adoption.
- Latin America: Accounted for 6.9% in 2025, with growth tied to AI data center platforms, nearshoring, and colocation hub development.
- Middle East and Africa: Accounted for 7.1% in 2025 and the fastest-growing region at about 4.5% CAGR, driven by GCC smart infrastructure investment and sovereign AI cloud strategies.
Key Challenges and Growth Opportunities in the Global Data Center Server Market
The global data center server market faces component supply chain constraints, as AI-driven DRAM and high-bandwidth memory shortages led server OEMs such as Dell, Lenovo, and HPE to announce price increases of 10-20% in late 2025 and early 2026. Power infrastructure limitations, with grid-connection wait times exceeding four years in primary data center markets, delay new facility commissioning, while US export controls on advanced semiconductors are fragmenting the global server supply chain. Firmware-level cybersecurity risks also add development cost and complexity.
The market offers considerable growth opportunities driven by edge computing expansion, with global active data center IT capacity expected to grow sixfold from 24 GW in 2025 to 147 GW by 2035, and by liquid cooling-ready server architectures that support next-generation GPU-dense deployments. India, supported by a USD 15 billion digital infrastructure investment program for 2026-2030, and Latin America, with large AI data center platforms under development, are also emerging as growth markets.
Competitive Landscape
The global data center server market is moderately concentrated, with established technology OEMs competing across rack, blade, micro, and tower server segments. Dell Technologies led AI-optimized server revenue in 2025 with an 8.3% revenue share in Q3 2025, according to IDC, and no single company holds more than 10% of total annual market revenue. Key players include Hewlett Packard Enterprise Development LP, Dell, Inc., Cisco Systems, Inc., Lenovo, Super Micro Computer, Inc., Huawei Technologies Co., Ltd., Fujitsu Ltd., and others. The IMARC report covers market structure, key player positioning, top winning strategies, a competitive dashboard, and a company evaluation quadrant, along with detailed profiles of all major companies.
Recent Developments in the Global Data Center Server Market
- March 2026: Super Micro Computer launched seven AI data platform solutions in partnership with NVIDIA and ecosystem partners, reinforcing its GPU-dense rack server positioning and expanding its range for inference at the edge.
- February 2026: Lenovo reorganized its data center (Infrastructure Solutions Group) business to improve profitability as strong AI demand drives rapid growth, reporting record quarterly revenue with all major divisions achieving double-digit gains.
- January 2026: RT-One and Hitachi Energy signed an agreement to develop electrification infrastructure for Latin America’s largest AI data center platform in Brazil.
- December 2025: Hewlett Packard Enterprise expanded its collaboration with NVIDIA to accelerate AI adoption across government and enterprise sectors with secure AI factory solutions. HPE also introduced the ProLiant Compute XD685 with direct-liquid cooling for Blackwell Ultra GPU configurations.
- October 2025: ABB and NVIDIA announced a collaboration to develop gigawatt-scale AI data centers with advanced 800 VDC power architectures optimized for high-density liquid-cooled server deployments.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: [email protected]
United States: +1-201-971-6302