Plywood Market Size Projected to Reach USD 77.6 Billion by 2034 with a CAGR of 4.31%
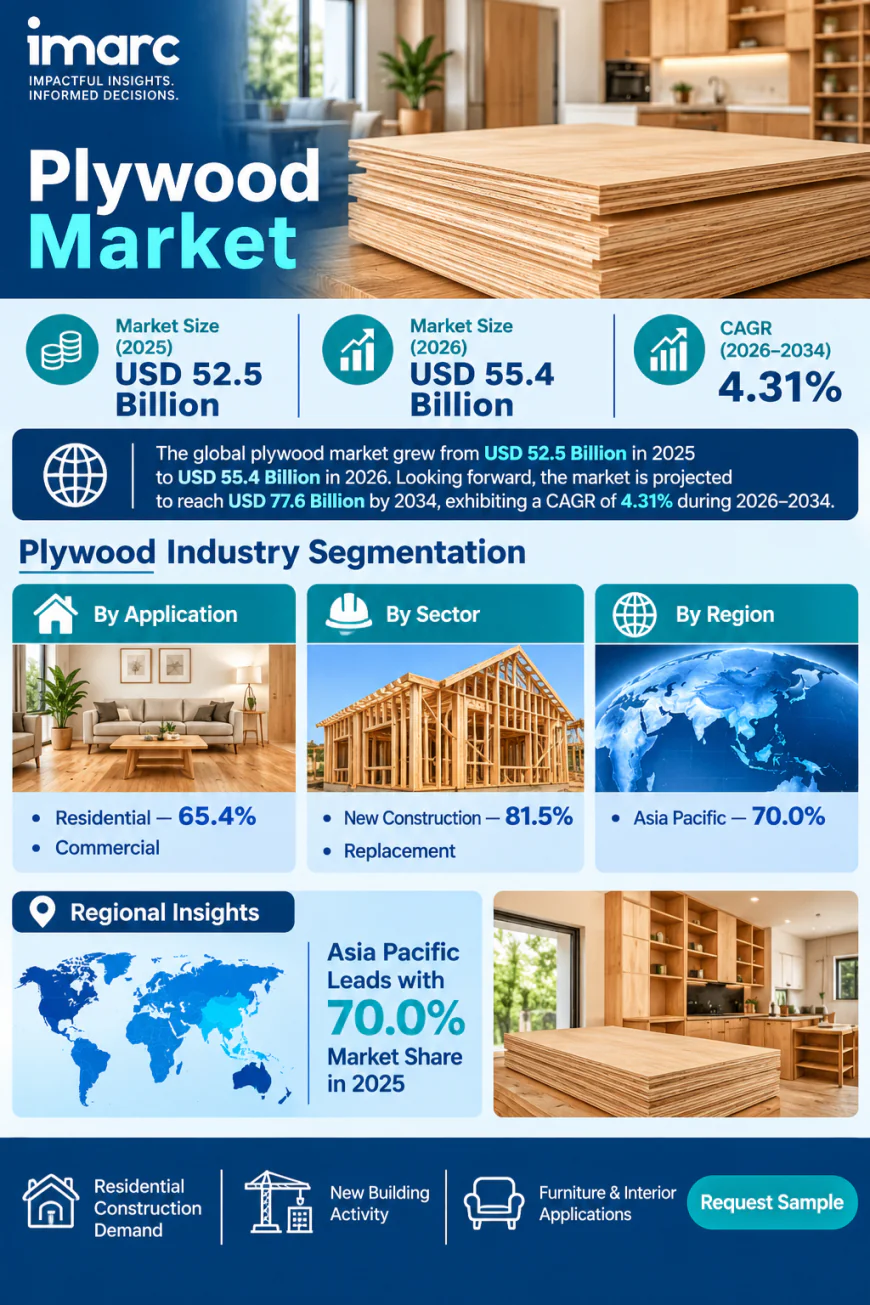
The global plywood market size increased from USD 52.5 Billion in 2025 to USD 55.4 Billion in 2026 and is expected to reach USD 77.6 Billion by 2034 at a CAGR of 4.31% during 2026-2034.
 michael matthew
IMARC Group has recently released a new research study titled “Plywood Market Report by Residential and Commercial Application, New Construction and Replacement Sector, and Region, 2026-2034,” offers a detailed analysis of the market drivers, segmentation, growth opportunities, trends and competitive landscape to understand the current and future market scenarios.
Plywood Market Size, Growth, and Forecast (2026-2034)
The plywood market size reached USD 52.5 Billion in 2025 and rose to USD 55.4 Billion in 2026. The market is projected to reach USD 77.6 Billion by 2034, growing at a CAGR of 4.31% during 2026-2034. Asia Pacific dominated the plywood market with a share of over 70.0% in 2025.
Accelerating urbanization, rising residential and commercial construction, growing government spending on affordable housing, and increasing preference for durable, sustainable engineered wood products are the primary factors driving the plywood market. Plywood is an engineered wood panel made by bonding thin layers of veneer, valued for its cost efficiency, dimensional stability, and ease of fabrication.
Across the plywood industry, plywood is widely used for flooring, roofing, and wall sheathing, as well as concrete formwork, furniture, and interior paneling. Demand from these uses supports the plywood sheathing market and reflects the material’s importance in both new buildings and renovation activity worldwide.
Explore Growth Opportunities in the Plywood Market - Grab Your Sample Report for Evaluation: https://www.imarcgroup.com/plywood-market/requestsample
Key Trends Driving the Plywood Market
-
Technological advancements in manufacturing processes: Modern plywood mills are adopting automation, digital precision cutting, and real-time quality monitoring. These systems have shown the ability to reduce variable production costs by around 14% and raise output by 13% to 28% without physical capacity expansion, strengthening competitiveness across the plywood industry.
-
Sustainability and eco-friendly innovation: Green building standards and tightening regulations are pushing manufacturers toward FSC-certified timber and low-emission adhesives. Demand for fire-resistant, moisture-resistant, and formaldehyde-free variants is also rising, moving procurement beyond commodity panels toward performance-grade engineered products.
-
Rising demand from furniture, interiors, and modular construction: Growth in furniture manufacturing and interior fit-outs continues to lift plywood use, while prefabricated and modular construction creates sustained demand for structural panels. These applications support the plywood sheathing market, as plywood’s structural integrity and fabrication ease suit factory-built units.
Plywood Market Report Segmentation:
The plywood market report provides a detailed segmentation analysis to help businesses identify key growth segments and evolving industry dynamics. The market is categorized based on residential and commercial application, new construction and replacement sector, and region, offering comprehensive insights across the plywood market.
Application Insights:
-
Residential: The residential segment dominates with a 65.4% share in 2025, driven by urbanization, affordable housing demand, and plywood’s use in flooring, wall sheathing, and roofing, which anchors the plywood sheathing market.
-
Commercial: The commercial segment is supported by office, retail, and hospitality construction and fit-outs that specify plywood for partitions, ceilings, and interior installations.
New Construction and Replacement Sector Insights:
-
New Construction: New construction leads with an 81.5% share in 2025, reflecting plywood’s role in structural sheathing, concrete formwork, roofing, and wall cladding across large residential and infrastructure projects.
-
Replacement: The replacement sector is supported by renovation and refurbishment activity, particularly in mature markets where home improvement spending remains steady.
Regional Insights:
-
Asia Pacific: Asia Pacific holds the largest share at 70.0% in 2025, anchored by China’s production and consumption base, India’s housing programs, and export-oriented wood processing in Vietnam and Indonesia.
-
North America: North America accounts for 12.4% of the plywood market, led by the United States, the largest single-country market for construction-grade plywood.
-
Europe: Europe holds a 9.8% share and is shaped by sustainability regulation and strong demand for premium birch and specialty plywood.
-
Latin America: Latin America represents 4.5% of the market and is supported by urbanization and growing residential construction.
-
Middle East and Africa: The Middle East and Africa holds a 3.3% share and is the fastest-growing region at a CAGR of about 5.6%, driven by large-scale construction and commercial projects.
Plywood Market: Recent News and Developments
-
January 2026: The U.S. Department of Commerce issued affirmative preliminary countervailing duty determinations on hardwood and decorative plywood from China, Indonesia, and Vietnam, with preliminary rates of 81.34% on imports from China. Structural plywood is outside the scope of these investigations.
-
August 2026: The U.S. International Trade Commission issued a unanimous affirmative final determination that the domestic hardwood and decorative plywood industry has been materially injured by dumped and subsidized imports from China, Indonesia, and Vietnam, clearing the way for final duties.
Challenges Impacting the Plywood Market
Plywood production depends on timber logs and petrochemical-based adhesives, whose prices are volatile due to weather, logging restrictions, and crude oil fluctuations. This instability affects production costs and margins across the plywood industry.
Stringent deforestation and sustainability regulations raise compliance costs, particularly for smaller manufacturers, while substitutes such as MDF, OSB, and particleboard compete in price-sensitive furniture and construction segments, including parts of the plywood sheathing market.
Investment Opportunities in the Plywood Market
The plywood market presents compelling investment opportunities supported by its projected growth from USD 55.4 Billion in 2026 to USD 77.6 Billion by 2034. Sustainable and engineered plywood aligned with green building certification represents an addressable opportunity of over USD 10 Billion by 2034.
Fire-resistant, waterproof, and marine-grade variants, together with fast-growing demand in India, Vietnam, Indonesia, and the Middle East, are creating further openings. Companies that combine certified sourcing, low-emission technology, and efficient manufacturing can build strong competitive positions in this expanding market.
Outlook of the Plywood Market (2026-2034)
The outlook for the plywood market is positive, supported by urbanization, infrastructure investment, and rising demand for engineered wood products. The market is projected to grow from USD 52.5 Billion in 2025 to USD 77.6 Billion by 2034 at a CAGR of 4.31%.
Product innovation, sustainability, and gradual consolidation among large integrated producers will be the defining trends shaping the plywood industry and the plywood sheathing market through 2034.
Key Players in the Plywood Market
The plywood market is moderately consolidated, with leading players including Georgia-Pacific LLC, PotlatchDeltic Corporation, Weyerhaeuser Company, Boise Cascade Company, UPM-Kymmene Oyj, SVEZA Group, Metsä Wood, Latvijas Finieris AS, and Austral Plywoods Pty Ltd., competing alongside many regional producers.
- Georgia-Pacific LLC: A wholly owned subsidiary of Koch Industries and one of the largest plywood and engineered wood producers, Georgia-Pacific is known for its Plytanium brand. In February 2025, it invested USD 14 Million to upgrade its Prosperity, South Carolina plywood mill, modernizing the boiler to improve fuel efficiency.
- Weyerhaeuser Company: One of the largest private owners of timberlands in the United States, with about 10.5 million acres, Weyerhaeuser integrates forestry with wood products manufacturing, offering structural plywood, OSB, engineered lumber, and laminated veneer lumber for residential and commercial construction.
Frequently Asked Questions (FAQs): Plywood Market
-
What is the current plywood market size? The plywood market size reached USD 52.5 Billion in 2025 and rose to USD 55.4 Billion in 2026, and is projected to reach USD 77.6 Billion by 2034, growing at a CAGR of 4.31% during 2026-2034.
-
What is plywood? Plywood is an engineered wood panel made by bonding thin layers of veneer together. It is widely used across the plywood industry for flooring, roofing, wall sheathing, concrete formwork, furniture, and interior paneling.
-
What are the key drivers of the plywood market? Key drivers include rapid urbanization, rising residential and commercial construction, government spending on affordable housing and infrastructure, growing furniture and interior design demand, and increasing adoption of eco-certified engineered wood products.
-
Which region and segments lead the plywood sheathing market and the wider plywood market? Asia Pacific leads with a 70.0% share in 2025. By application, residential leads with 65.4%, and by sector, new construction leads with 81.5%, supported by demand for flooring, roofing, and wall sheathing.
-
Who are the key players in the plywood market? Key players in the plywood market include Georgia-Pacific LLC, PotlatchDeltic Corporation, Weyerhaeuser Company, Boise Cascade Company, UPM-Kymmene Oyj, SVEZA Group, Metsä Wood, Latvijas Finieris AS, and Austral Plywoods Pty Ltd., among others.
Author IMARC Group
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provide a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us
IMARC Group,
134 N 4th St. Brooklyn, NY 11249, USA,
Email: [email protected],
United States: +1-201971-6302