Artillery Ammunition Market Trends Highlight Increasing Global Defense Investments
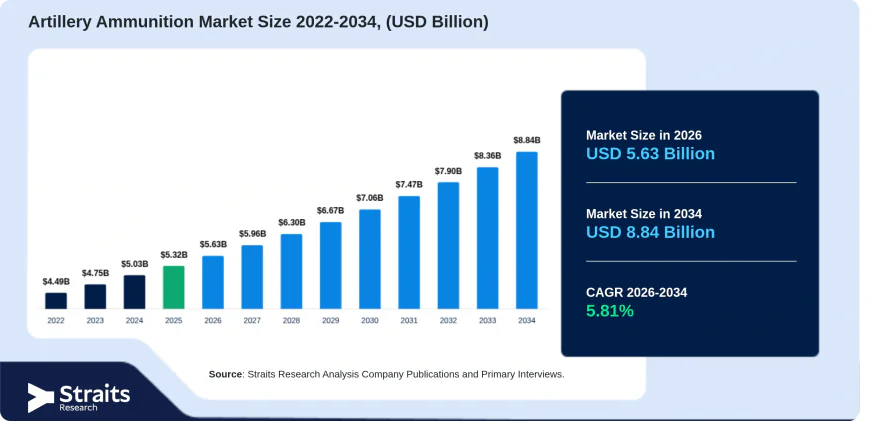
The global artillery ammunition market size was valued at USD 5.32 billion in 2025 and is projected to grow from USD 5.63 billion in 2026 to USD 8.84 billion by 2034, registering a CAGR of 5.81% during the forecast period from 2026 to 2034.
 Aditi Jdv
Artillery Ammunition Market
The global artillery ammunition market size was valued at USD 5.32 billion in 2025 and is projected to grow from USD 5.63 billion in 2026 to USD 8.84 billion by 2034, registering a CAGR of 5.81% during the forecast period (2026–2034). The market is witnessing steady growth due to increasing defense expenditure, military modernization programs, and rising investments in national security infrastructure. Governments across several countries are strengthening their defense capabilities and prioritizing ammunition stock replenishment to maintain military readiness.
The growing focus on domestic defense manufacturing, procurement modernization, and long-term military preparedness is supporting industry development. In addition, geopolitical uncertainties and changes in defense procurement strategies are encouraging governments to strengthen their ammunition supply chains and production capabilities.
For detailed market insights, growth forecasts, and competitive analysis, visit:https://straitsresearch.com/report/artillery-ammunition-market
Market Drivers
Rising Defense Expenditure and Military Modernization Drive Market Growth
Increasing defense expenditure is a major factor supporting the growth of the artillery ammunition market. Governments are allocating larger budgets to strengthen national security, modernize military equipment, and improve defense preparedness. Several countries are investing in upgrading existing artillery systems and maintaining sufficient ammunition inventories to support long-term defense requirements.
Military modernization programs are also encouraging procurement of advanced ammunition technologies. Defense organizations are focusing on improving the reliability, accuracy, and compatibility of ammunition with modern military platforms. These investments are supporting manufacturers and creating opportunities for long-term supply contracts.
Increasing Geopolitical Tensions and Ammunition Stockpile Replenishment
Geopolitical uncertainties and regional security concerns are encouraging governments to strengthen their defense supply chains. Countries are prioritizing ammunition stockpile replenishment to maintain military readiness and reduce dependence on external suppliers.
The growing focus on domestic defense production is further supporting market development. Governments are encouraging local manufacturers to expand production capabilities and establish reliable supply networks. These initiatives are creating opportunities for established defense contractors and specialized ammunition manufacturers.
Market Challenges
High Manufacturing and Research and Development Costs
High manufacturing costs remain a significant challenge for the artillery ammunition market. Production requires specialized industrial facilities, advanced manufacturing equipment, strict quality control, and compliance with defense procurement standards. These requirements increase capital expenditure and operational costs for manufacturers.
The development of technologically advanced ammunition also requires substantial research and development investments. Smaller manufacturers may face difficulties competing with established defense companies that have greater financial resources and manufacturing capabilities.
Supply Chain Constraints and Regulatory Requirements
The market depends on specialized materials, components, and industrial manufacturing capabilities. Disruptions in the availability of raw materials and production inputs can affect manufacturing schedules and delivery commitments. Limited production capacity may also create challenges when governments place large procurement orders.
Additionally, international defense trade regulations, export controls, and licensing requirements can complicate cross-border transactions. Manufacturers must maintain compliance with national and international regulations while managing complex procurement procedures.
Market Segmentation
The global artillery ammunition market is segmented by type, caliber, technology, and application.
By Type
The market is categorized into high-explosive (HE), armor-piercing (AP), cluster munitions, smoke/illumination/incendiary, and precision-guided munitions (PGMs).
The high-explosive segment dominated the market, accounting for more than 40% of total revenue. Its leading position is supported by its established role in conventional artillery inventories and widespread inclusion in defense procurement programs. Armor-piercing, smoke, illumination, and other specialized ammunition categories also contribute to the market.
By Caliber
The market includes small artillery calibers (below 105 mm), medium artillery calibers (105–155 mm), and large artillery calibers (above 155 mm).
The medium artillery calibers segment dominated the market, accounting for more than 45% of the share. Its leading position reflects widespread adoption across established artillery platforms and continued procurement by defense organizations.
The large artillery calibers segment is expected to register the fastest growth, with a CAGR of 6.43% during 2026–2034. Increasing investments in modern artillery platforms and specialized defense capabilities are supporting demand for this category.
By Technology
The market is divided into conventional munitions, precision-guided munitions, smart munitions, and extended-range munitions.
Conventional munitions represent an established category due to their widespread presence in existing defense inventories. However, precision-guided munitions are expected to register the fastest growth, with a CAGR of 6.37% during the forecast period. Increasing defense investments in advanced targeting technologies and improved accuracy are supporting interest in this segment.
By Application
The market includes field artillery, coastal artillery, air defense, and naval artillery.
Field artillery dominated the market, accounting for approximately 45% of the share. Its leading position is supported by continued investment in land-based defense infrastructure and the modernization of existing military equipment.
Naval artillery is expected to register the fastest growth, with a CAGR of 6.67% during 2026–2034. Increasing attention to maritime security, naval fleet modernization, and coastal defense infrastructure is supporting this segment.
Regional Insights
North America
North America dominated the global artillery ammunition market with a 34.6% share in 2025. The region benefits from substantial defense budgets, established defense manufacturers, and continuous military modernization programs. The United States represents a major contributor due to investments in domestic ammunition manufacturing, defense procurement, and military infrastructure. Canada also supports regional development through defense modernization initiatives.
Europe
Europe represents an important market due to increasing defense investments, ammunition stockpile replenishment, and efforts to strengthen domestic manufacturing capabilities. Countries such as Germany, France, and the United Kingdom are investing in defense infrastructure and production capacity. Regional cooperation and procurement initiatives are also supporting demand for ammunition products.
Asia-Pacific
Asia-Pacific is expected to register the fastest regional growth, with a CAGR of 6.53% during 2026–2034. Increasing defense expenditure, military modernization, and regional security concerns are supporting market development. China, India, Japan, and South Korea are important contributors, with investments in domestic defense manufacturing and military infrastructure strengthening regional demand.
Key Players Analysis
The global artillery ammunition market is characterized by established defense manufacturers focusing on production capacity, technological innovation, strategic partnerships, and long-term government contracts. Companies are strengthening their manufacturing capabilities and investing in research and development to address changing defense procurement requirements.
Key players operating in the artillery ammunition market include:
-
Rheinmetall AG
-
BAE Systems plc
-
General Dynamics Corporation
-
Northrop Grumman Corporation
-
Thales Group
-
Nammo AS
-
Hanwha Aerospace
-
Elbit Systems Ltd.
-
Leonardo S.p.A.
-
Saab AB
These companies maintain competitive positions through established defense manufacturing operations, product portfolio development, and partnerships with government defense organizations.
Conclusion
The global artillery ammunition market is expected to experience steady growth through 2034, supported by increasing defense expenditure, military modernization, and ammunition stockpile replenishment. North America remains a leading regional market, while Asia-Pacific is expected to record the fastest growth. Technological advancements, domestic manufacturing investments, and expanding defense procurement programs are creating opportunities for market participants. However, high production costs, supply chain constraints, and regulatory requirements remain important challenges. Continued investments in defense infrastructure are expected to support market expansion during the forecast period.
About Us
Straits Research is a leading market research and intelligence organization specializing in research, analytics, and advisory services. The company provides comprehensive market reports, industry insights, and strategic business intelligence across multiple industries, helping organizations identify growth opportunities and make informed business decisions.
Contact Us
Email: [email protected]
Tel: +1 646 905 0080 (U.S.)
Tel: +44 203 695 0070 (U.K.)