XBRL Filing Companies in India: Who Needs to File?
Learn which XBRL Filing Companies in India need to file financial statements in XBRL format and understand applicability, exemptions and validation.
 webtelinsights
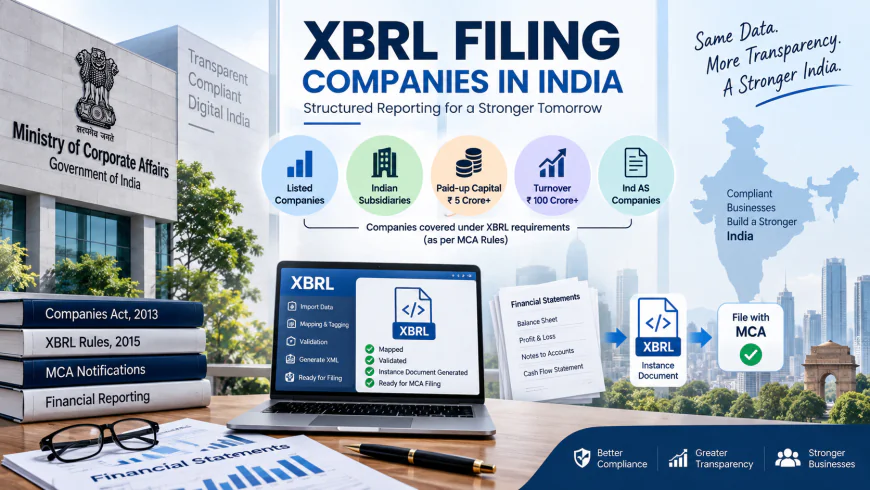
XBRL filing is a structured way of reporting financial information to the Ministry of Corporate Affairs (MCA). It converts financial data into a machine-readable format using standardized XBRL concepts and tags. However, XBRL filing is not applicable to every company in India. Specific classes of companies are required to file their financial statements in XBRL format under the applicable MCA rules.
Understanding which companies fall under these requirements is important before starting the filing process. Businesses can also use an XBRL Filing Software solution to help with activities such as data mapping, tagging, validation and XBRL instance-document preparation.
Which Companies Need XBRL Filing in India?
Under Rule 3 of the Companies (Filing of Documents and Forms in Extensible Business Reporting Language) Rules, 2015, as amended, certain classes of companies are required to file their financial statements and other applicable documents in e-form AOC-4 XBRL.
The main categories include:
| Company category | XBRL applicability |
|---|---|
| Listed companies | Companies listed with stock exchanges in India |
| Indian subsidiaries | Indian subsidiaries of companies covered under the applicable listed-company provision |
| Paid-up capital | Companies having paid-up capital of ₹5 crore or more |
| Turnover | Companies having turnover of ₹100 crore or more |
| Ind AS companies | Companies required to prepare financial statements under the applicable Ind AS Rules |
The exact applicability should be checked against the current rules and the company's individual circumstances rather than relying only on its size or industry.
What Does XBRL Filing Involve?
XBRL filing involves more than simply converting a financial statement into an XML file. Financial information has to be associated with the appropriate concepts in the applicable XBRL taxonomy.
The preparation process generally includes:
- Collecting the company's financial information and supporting documents.
- Selecting the applicable XBRL taxonomy.
- Mapping financial information with appropriate XBRL concepts.
- Tagging relevant financial statements and disclosures.
- Creating the XBRL instance document.
- Validating the instance document.
- Attaching the validated document to the applicable MCA form.
MCA's filing manual states that the validated and pre-scrutinized XBRL instance document is attached to Form AOC-4 XBRL. Separate instance documents are required for consolidated financial statements where applicable.
Are All Companies Required to File XBRL?
No. The XBRL rules contain specific exemptions.
The 2017 amendment to the XBRL Rules states that non-banking financial companies, housing finance companies, and companies engaged in the banking and insurance sectors are exempted from filing financial statements under those rules.
This means a company should not determine XBRL applicability solely from its paid-up capital or turnover. Its business category, accounting requirements and other applicable conditions should also be considered.
Why Is XBRL Validation Important?
Validation is an important stage of the XBRL preparation process. It helps identify technical problems in the instance document before submission.
Depending on the applicable taxonomy and filing requirements, validation can involve checking items such as:
- Incorrect or incomplete tags
- Invalid data formats
- Missing required information
- Calculation inconsistencies
- Incorrect contexts or reporting periods
- Other taxonomy or business-rule errors
MCA released XBRL Validation Tool V5.1 for C&I and IND-AS taxonomies in July 2025 and advised stakeholders to use the new version while filing AOC-4 XBRL. MCA also released V5.1 for the Costing Taxonomy for CRA-4 filings.
How Can a Company Check Its XBRL Applicability?
A company can begin by checking whether it falls into any of the categories specified under the applicable XBRL rules. Its paid-up capital, turnover, listing status, relationship with another covered company and Ind AS applicability can all be relevant.
The company should then identify the appropriate taxonomy and filing form. If XBRL filing applies, the financial information needs to be prepared and tagged according to the applicable requirements before the instance document is validated.
It is also important to check the latest MCA notifications and validation-tool updates because technical filing requirements can change over time.
What Should Companies Look for in XBRL Software?
Companies and professionals handling XBRL preparation may look for software that supports:
- XBRL taxonomy mapping
- Financial statement tagging
- Data import
- XML instance-document generation
- Validation checks
- Error identification
- Previous-year data handling
- Updates for changes in applicable filing requirements
The software itself does not determine whether a company is legally required to file XBRL. Applicability comes from the relevant regulatory requirements.
Frequently Asked Questions
Which companies need XBRL filing in India?
Companies covered under the applicable XBRL rules include listed companies and their Indian subsidiaries, companies meeting specified paid-up capital or turnover thresholds, and companies required to prepare financial statements under applicable Ind AS Rules, subject to exemptions.
Is XBRL filing mandatory for every private company?
No. A private company becomes subject to XBRL filing only if it falls within a category covered by the applicable rules.
What is AOC-4 XBRL?
AOC-4 XBRL is the MCA form used for filing applicable financial statements and related information in XBRL format.
Do companies have to validate XBRL documents?
Yes, applicable XBRL instance documents need to go through the required validation and pre-scrutiny process before submission.
Conclusion
XBRL filing in India applies to specific classes of companies rather than every business. Listed companies, certain companies meeting capital or turnover thresholds, and applicable Ind AS companies can fall within the requirements, while specified sectors and entities may be exempt. Companies should verify their applicability against the current MCA rules and prepare their XBRL documents using the relevant taxonomy and validation process.