UK Meat Market Growth Analysis & Forecast Report 2026-2034
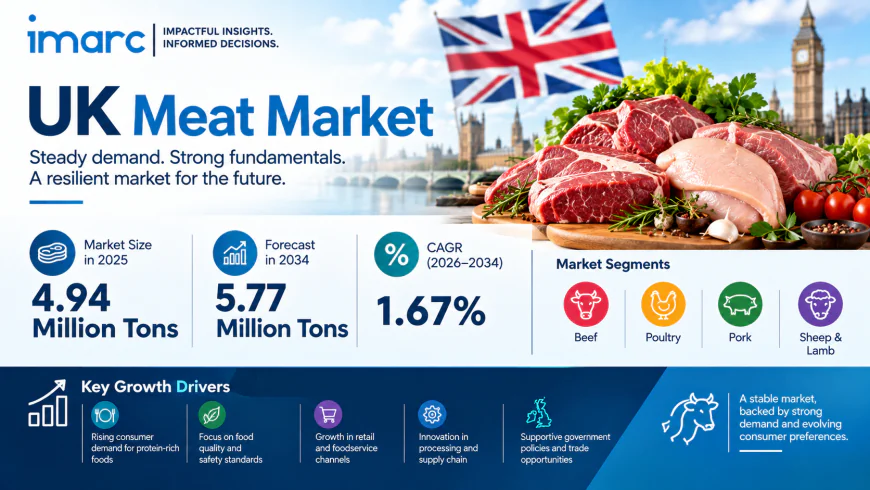
The UK meat market size reached 4.94 Million Tons in 2025. Looking forward, IMARC Group expects the market to reach 5.77 Million Tons by 2034, exhibiting a growth rate (CAGR) of 1.67% during 2026-2034.
 Arlo Bennett
Market Overview
The UK meat market size reached 4.94 Million Tons in 2025 and is projected to reach 5.77 Million Tons by 2034, growing at a compound annual growth rate (CAGR) of 1.67% from 2026 to 2034. The market is driven by sustained domestic consumption of animal protein, growing demand for high-quality and locally sourced meat products, expanding retail and foodservice channels, and increasing consumer emphasis on food safety, traceability, and animal welfare standards.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/uk-meat-market/requestsample
UK Meat Market Summary
-
The UK meat market encompasses a range of products, including poultry, beef, pork, lamb and mutton, and others, available in fresh, chilled, frozen, and processed formats, serving residential and commercial end users through supermarkets and hypermarkets, specialty stores, online channels, and foodservice outlets.
-
These products are valued for their role in providing essential protein and nutrition, supporting culinary diversity, and serving as a cornerstone of British food culture and retail consumption patterns.
-
The ecosystem includes livestock farmers, abattoirs, meat processors, wholesalers, retailers, foodservice operators, and regulatory bodies including the Food Standards Agency (FSA) and Red Tractor assurance schemes.
-
Major segments identified in the market include product type (poultry, beef, pork, lamb and mutton, others), packaging type, distribution channel (supermarkets and hypermarkets, specialty stores, online, foodservice, others), and region (London, South East, North West, East of England, South West, Scotland, West Midlands, Yorkshire and The Humber, East Midlands, Others).
-
The market is benefiting from growing demand for locally sourced and premium meat products, expansion of online grocery and direct-to-consumer channels, rising interest in processed and convenience meat formats, and increasing focus on sustainability and animal welfare credentials.
-
The UK remains a significant producer and consumer of meat, supported by established farming infrastructure, strong retail networks, and well-developed food safety and traceability systems.
Porter's Five Forces Analysis
-
Competitive Rivalry: High, with major retailers, branded processors, own-label suppliers, and specialist butchers competing on price, quality, provenance, and sustainability credentials. Business implication: Companies must differentiate through quality assurance, traceability, and brand trust.
-
Supplier Power (Livestock Farmers and Processors): Moderate. Livestock farmers and primary processors have some leverage, particularly in premium and specialty segments, but the presence of multiple suppliers and the buying power of large retailers moderates this power. Business implication: Processors should maintain diverse supplier relationships and invest in long-term farmer partnerships.
-
Buyer Power (Retailers and Consumers): High. Major supermarkets and foodservice operators exert significant pricing pressure, while consumers have extensive choice across product types, formats, and price points. Business implication: Producers must focus on cost efficiency, quality consistency, and value-added offerings.
-
Threat of Substitutes: Moderate. Plant-based proteins, meat alternatives, and other protein sources compete for share of plate, particularly among younger and health-conscious consumers, but meat remains a core dietary staple. Business implication: The industry should emphasize nutritional benefits, taste, and provenance.
-
Threat of New Entrants: Moderate. Higher barriers for established players (regulatory compliance, cold chain infrastructure, retail listings), but lower barriers for niche and premium entrants leveraging direct-to-consumer channels. Business implication: Established players should build defensible positions through brand equity, scale, and supply chain integration.
Market Growth Drivers
Sustained Domestic Consumption of Animal Protein
Sustained domestic consumption of animal protein remains a fundamental driver of the UK meat market. Meat continues to form a central component of British diets, with poultry, beef, pork, and lamb maintaining strong demand across household and foodservice channels. Despite growing interest in plant-based alternatives, meat retains a dominant position in meal planning and restaurant menus, supported by its nutritional profile, versatility, and cultural significance. Retail demand remains resilient across value and premium tiers, with consumers prioritizing quality and provenance in their purchasing decisions.
Growing Demand for Locally Sourced and Premium Products
Growing demand for locally sourced and premium meat products is driving market value growth in the UK. Consumers are increasingly seeking products with clear provenance, high animal welfare standards, and support for British farming. Red Tractor assurance and other certification schemes provide consumers with confidence in quality, safety, and traceability. Premium categories including dry-aged beef, free-range poultry, and heritage breed pork are expanding, supported by specialist retailers, farm shops, and direct-to-consumer channels. This trend supports higher value per unit and encourages investment in quality differentiation across the supply chain.
Expansion of Retail and Foodservice Channels
Expansion of retail and foodservice channels is supporting volume and value growth in the UK meat market. Supermarkets and hypermarkets remain the dominant distribution channel, offering extensive product ranges across fresh, chilled, frozen, and processed formats. Online grocery platforms and direct-to-consumer meat boxes are growing rapidly, providing consumers with greater convenience and access to premium and specialty products. Foodservice operators, including restaurants, pubs, and quick-service outlets, represent a significant demand segment, with meat featuring prominently across menus. The recovery of hospitality and foodservice activity following the pandemic has supported volume recovery across the market.
Focus on Sustainability and Animal Welfare
Focus on sustainability and animal welfare is shaping product development and consumer preferences in the UK meat market. Consumers are increasingly aware of the environmental impact of meat production and are seeking products with lower carbon footprints, responsible sourcing, and high welfare standards. Producers are responding through investment in regenerative farming practices, renewable energy, packaging reduction, and transparent supply chain reporting. Certification schemes and retailer commitments to higher welfare standards are reinforcing this trend, supporting premium positioning and long-term market resilience.
UK Meat Market Segmentation
Product Type Insights:
-
Poultry
-
Beef
-
Pork
-
Lamb and Mutton
-
Others
Distribution Channel Insights:
-
Supermarkets and Hypermarkets
-
Specialty Stores
-
Online
-
Foodservice
-
Others
Regional Insights:
-
London
-
South East
-
North West
-
East of England
-
South West
-
Scotland
-
West Midlands
-
Yorkshire and The Humber
-
East Midlands
-
Others
Competitive Landscape
The UK meat market features a competitive landscape encompassing major retailers, branded processors, own-label suppliers, and specialist butchers. Market participants differentiate through product quality, provenance, sustainability credentials, and value. Major supermarkets dominate retail distribution, leveraging own-label ranges and supply chain scale, while branded processors compete on product innovation and brand trust. The competitive analysis includes market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, with detailed profiles of all major companies provided in the report.
Key players mentioned in the report's context include:
-
Major UK retailers including Tesco, Sainsbury's, Asda, and Morrisons dominate meat distribution through extensive own-label ranges and supply chain integration.
-
Leading processors and branded suppliers including Cranswick plc, ABP Food Group, 2 Sisters Food Group, and Moy Park play significant roles in meat processing and supply.
-
Specialist and premium producers are expanding through direct-to-consumer channels and farm shop networks, supported by growing demand for locally sourced and high-welfare products.
Regional Analysis
-
London: The dominant region driven by high population density, diverse consumer base, and strong demand for premium and specialty meat products. The region benefits from a concentration of foodservice outlets, specialty retailers, and direct-to-consumer channels.
-
South East: A significant market driven by affluent consumer base, strong demand for premium and locally sourced products, and high penetration of online grocery channels.
-
North West: A growing market driven by urban centers including Manchester and Liverpool, strong retail infrastructure, and growing demand for convenience and processed meat products.
-
East of England: A growing market driven by agricultural production, strong retail presence, and growing demand for locally sourced products.
-
South West: A growing market driven by strong agricultural heritage, growing demand for premium and specialty products, and expanding direct-to-consumer channels.
-
Scotland: A significant market driven by premium beef and lamb production, strong export credentials, and growing demand for locally sourced products.
-
West Midlands: A growing market driven by urbanization, strong retail infrastructure, and growing demand for convenience meat products.
-
Yorkshire and The Humber: A growing market driven by agricultural production, strong retail presence, and growing demand for value-oriented products.
-
East Midlands: A growing market driven by agricultural production, growing retail presence, and increasing demand for locally sourced products.
-
Others: Remaining UK regions with varying meat demand dynamics based on local demographics and retail infrastructure.
Recent Industry Developments
September 2026: UK red-meat retail volumes declined 1.6% year-on-year in the 12 weeks to 6 September. Beef volumes fell 1.0%, while lamb declined 9.2% and pig meat 1.4%. Higher prices continued affecting demand, although beef steaks and processed beef products recorded stronger sales during the period.
September 2026: UK red-meat exports reached £1.1 billion in the first half of 2026, increasing 15% year-on-year, while export volumes rose 8% to almost 293,000 tonnes. Strong overseas demand helped support domestic livestock prices despite challenging international trading conditions and continued cost pressures across the meat supply chain.
September 2026: UK beef production increased 4.6% year-on-year to 72,000 tonnes in August, while prime-cattle slaughterings rose 3.1% to 160,000 head. Pigmeat production also increased 3.8% to 79,000 tonnes, whereas mutton and lamb production declined 4.0% to 20,000 tonnes.
August 2026: UK supermarket meat prices remained broadly stable, with the average price across 30 fresh British beef, lamb, pork and chicken cuts increasing just 0.08% during August. Lamb remained the exception, rising 6.9% year-on-year, while beef, pork and chicken prices declined 2.75%, 4.66% and 5.78%, respectively.
June 2026: England’s cattle population fell 1.5% to 4.8 million animals in June 2026, with the beef breeding herd declining 1.8% to 559,000. Sheep numbers also decreased 2.0% to 13 million, while pig numbers increased 3.4% to 3.8 million, highlighting changing livestock supply conditions.
Key Aspects Required for the UK Meat Market
-
Market Performance: 4.94 Million Tons in 2025, with a projected trajectory to 5.77 Million Tons by 2034.
-
Market Outlook: A 1.67% CAGR through 2034 indicates steady growth across product types, distribution channels, and regions, driven by sustained domestic consumption, premiumisation, channel expansion, and sustainability focus.
-
Growth Drivers: Sustained domestic consumption of animal protein; growing demand for locally sourced and premium products; expansion of retail and foodservice channels; focus on sustainability and animal welfare; and increasing demand for convenience and processed meat formats.
-
Competitive Landscape: A highly competitive market with major retailers, branded processors, own-label suppliers, and specialist butchers. Differentiation occurs through product quality, provenance, sustainability credentials, and value.
-
Value Chain Analysis: From livestock farming and primary processing through distribution and retail to end-use in household and foodservice consumption, with sustainability and traceability trends shaping market dynamics.
-
Industry Trends: Premiumisation and provenance focus; growth of online and direct-to-consumer channels; expansion of processed and convenience formats; increasing focus on sustainability and animal welfare; and growing competition from plant-based alternatives.
-
Strategic Recommendations: Invest in quality assurance and traceability; expand premium and locally sourced product ranges; develop online and direct-to-consumer channels; focus on sustainability and animal welfare credentials; and strengthen foodservice partnerships.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=24977&flag=C
Report Format, Delivery, and Customization Details
-
Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
-
Report Delivery Mode: Online Delivery, Physical Delivery
-
Report Delivery Time: The report is delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
-
Report Confirmation Mode: Yes, via email
-
Report Customization Mode: Yes, via Email / Call
-
Report Table of Content: Yes
-
Report List of Figures: Yes
-
Report Methodology Mode: Yes
-
Request For Sample Report: Yes