Artificial Intelligence Market Size, Growth Analysis, Industry Trends & Forecast 2034
Artificial intelligence market size increased from USD 143.0 Billion in 2025 to USD 184.7 Billion in 2026 and is projected to reach USD 949.0 Billion by 2034 at a CAGR of 22.70% during 2026-2034.
 ashish kumar
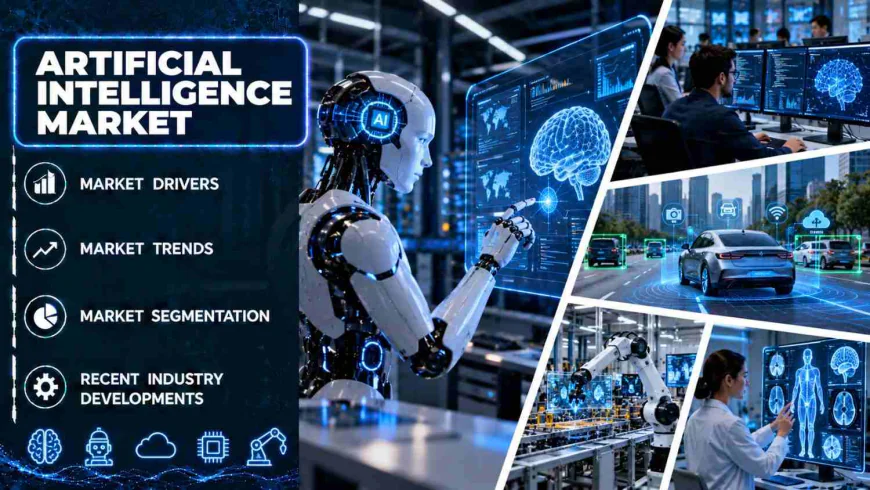
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the artificial intelligence market. The global artificial intelligence market grew from USD 143.0 Billion in 2025 to USD 184.7 Billion in 2026 and is projected to reach USD 949.0 Billion by 2034, growing at a CAGR of 22.70% during 2026-2034, driven by explosive growth in data generation from social media, IoT devices, and online transactions, rapid advances in computing power and deep learning algorithms, rising enterprise demand for AI-driven automation, and strong government and private investment in AI infrastructure worldwide.
The market is experiencing powerful momentum as artificial intelligence moves from experimental pilots to core business infrastructure across industries. According to the Stanford AI Index, 88% of organizations now report using AI, and 70% use generative AI in at least one business function. Private AI investment rose 127.5% in the latest annual reading, with generative AI accounting for nearly half of it. Hyperscalers are committing capital at an unprecedented scale: Microsoft alone has guided to roughly USD 190 Billion of capital expenditure for the year, largely directed at AI data centers. Governments are reinforcing this shift through national compute programs, sovereign AI initiatives, and science-focused AI missions.
How AI is Reshaping the Future of the Artificial Intelligence Market
- Accelerated Computing Is Becoming the Industry’s Backbone: NVIDIA reported quarterly revenue of USD 68 Billion in February 2026, up 73% year over year, with Data Center revenue reaching USD 62 Billion, up 75%. AI model training and inference are now the primary driver of semiconductor demand, pulling hardware, networking, and cloud services into a single compounding growth loop.
- Enterprise AI Is Moving Into Regulated and Hybrid Environments: In July 2026, Microsoft expanded its partnership with Mistral to bring enterprise AI to regulated industries, integrating Mistral’s latest models into Microsoft Foundry, Copilot Studio, Azure, and Azure Local. This enables deployment across cloud, hybrid, and disconnected environments, opening banking, healthcare, and public sector workloads that were previously restricted by data residency rules.
- AI Is Now Accelerating Scientific Discovery Itself: The United States Genesis Mission, announced with more than USD 5 Billion in federal commitments, selected 278 projects from more than 5,000 applications in July 2026. Led by the Department of Energy with more than 15 federal agencies contributing, the program applies AI to areas such as nuclear energy, materials, and healthcare research, showing how the technology is becoming a tool for building new knowledge rather than only automating existing work.
Grab a sample PDF of this report: https://www.imarcgroup.com/artifical-intelligence-market/requestsample
Artificial Intelligence Market Trends and Drivers:
The global artificial intelligence market is witnessing rapid expansion, fueled by the convergence of data abundance, falling cost per unit of compute, and enterprises’ urgent need to convert operational data into automated decisions. Data generation from social platforms, connected devices, and digital transactions has created the raw material that machine learning models require, while advances in deep learning architectures and specialized processors have made training and deploying those models commercially practical. Adoption is now broad rather than niche, with the Stanford AI Index showing 88% of organizations using AI and generative AI reaching 53% consumer adoption within three years, a faster diffusion curve than the personal computer or the internet. Infrastructure spending confirms the commitment: combined capital expenditure plans of Microsoft, Alphabet, Meta, and Amazon reached an estimated USD 725 Billion for the year, up 77% from the prior year’s USD 410 Billion, with Alphabet guiding up to USD 190 Billion and Meta more than USD 145 Billion.
Government and public investment is the second structural pillar of market growth, creating sovereign demand for compute, models, and talent across regions. In India, the IndiaAI Mission, launched in March 2024 with an outlay of more than Rs 10,300 Crore, has expanded national compute capacity to 38,000 GPUs and offers high-end GPU access to startups, researchers, and academic institutions at Rs 65 per hour, supported by the AIKosh national dataset platform and the BharatGen multilingual foundation model. In Europe, the InvestAI initiative aims to mobilize EUR 200 Billion in AI investment, including a EUR 20 Billion European fund for up to four AI gigafactories, each designed to host around 100,000 of the latest-generation AI chips. In China, the core AI industry surpassed 900 billion yuan, growing 24% year on year, and is expected to exceed 1.2 trillion yuan, supported by the State Council’s AI Plus initiative to embed AI across the economy. In the United States, the Stargate infrastructure program has planned nearly 7 gigawatts of capacity across new sites in Texas, New Mexico, and Ohio, tied to more than USD 400 Billion of investment over three years.
Regulation and trust are emerging as a defining driver that shapes how and where AI is deployed. The EU AI Act sets penalties of up to EUR 35 Million or 7% of worldwide annual turnover for prohibited AI practices and up to EUR 15 Million or 3% for most other operator obligations, pushing enterprises toward governed, auditable, and explainable systems. The Stanford AI Index also recorded 362 documented AI-related incidents in the latest annual count, up from 233 the year before, while only 31% of US respondents trust their government to regulate AI effectively. These pressures are creating parallel demand for AI governance tooling, secure on-premise deployment, and compliance-ready platforms, which expands the addressable market for software and services alongside hardware.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=2078&flag=E
Artificial Intelligence Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Type:
- Narrow/Weak AI
- General/Strong AI
Narrow or weak AI accounts for the largest type segment with a share of 92.8%, as task-specific systems for language, vision, prediction, and recommendation are already delivering measurable returns across industries, while general or strong AI remains largely developmental at 7.2% share.
Breakup By Offering:
- Hardware
- Software
- Services
Software leads the offering segment with a 36.7% share, followed by services at 34.5% and hardware at 28.8%, reflecting strong enterprise uptake of AI platforms, models, and applications alongside growing demand for integration, consulting, and managed AI services.
Breakup By Technology:
- Machine Learning
- Natural Language Processing
- Context-Aware Computing
- Computer Vision
- Others
Machine learning represents the leading technology segment, underpinning predictive analytics, recommendation engines, fraud detection, and generative models, and serving as the foundation on which natural language processing and computer vision capabilities are built.
Breakup By System:
- Intelligence Systems
- Decision Support Processing
- Hybrid Systems
- Fuzzy Systems
Intelligence systems hold the leading position among system types, supported by their ability to learn from data, adapt to changing conditions, and automate complex cognitive tasks across enterprise workflows.
Breakup By End-Use Industry:
- Healthcare
- Manufacturing
- Automotive
- Agriculture
- Retail
- Security
- Human Resources
- Marketing
- Financial Services
- Transportation and Logistics
- Others
Manufacturing is the leading end-use industry, driven by AI-enabled predictive maintenance, computer vision quality inspection, robotics, and supply chain optimization that cut downtime and defect rates on production lines.
Breakup By Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
North America dominates the global artificial intelligence market with a 30.6% share, supported by the concentration of hyperscalers, leading chip designers, frontier AI laboratories, and deep venture capital funding. Asia Pacific follows closely at 29.4%, with Europe at 25.3%, Latin America at 8.1%, and the Middle East and Africa at 6.6%, as national AI programs in China, India, Japan, and South Korea rapidly expand regional compute and talent capacity.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the artificial intelligence market with detailed profiles of all major companies, including:
- Microsoft
- Amazon Web Services, Inc.
- IBM Corporation
- NVIDIA Corporation
- Intel Corporation
- Oracle
What Does The Full Report Cover?
If you are tracking the artificial intelligence market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group’s report gives you everything in one place:
- Complete market sizing with revenue forecasts covering the full projection period
- Quantified growth driver, restraint, and opportunity analysis, including compute costs, talent shortages, data privacy, and regulatory fragmentation
- Sub-segment breakdowns by type, offering, technology, system, and end-use industry with individual share data
- Country-level data for the United States, Canada, Germany, France, the United Kingdom, Italy, Spain, Russia, China, Japan, India, South Korea, Australia, Indonesia, Brazil, and Mexico
- Competitive profiles of leading companies, with market concentration analysis and strategic landscape assessment
- Porter’s Five Forces, value chain analysis, and pricing intelligence
- Latest innovation trends covering generative AI, sovereign AI infrastructure, enterprise copilots, and AI governance tooling shaping competition across key regional markets
Recent News and Developments in Artificial Intelligence Market
- July 2026: Microsoft expanded its partnership with Mistral to support enterprise AI in regulated industries. Mistral’s latest models are integrated into Microsoft Foundry, Copilot Studio, Azure, and Azure Local, enabling deployment across cloud, hybrid, and disconnected environments.
- July 2026: The United States announced more than USD 5 Billion in federal commitments under the Genesis Mission, selecting 278 AI-for-science projects from more than 5,000 applications. The largest single award is USD 60 Million for a three-year nuclear energy project called Prometheus.
- April 2026: Combined 2026 capital expenditure plans of Microsoft, Alphabet, Meta, and Amazon reached an estimated USD 725 Billion, up 77% from USD 410 Billion. Microsoft guided to USD 190 Billion, Alphabet up to USD 190 Billion, and Meta more than USD 145 Billion.
- February 2026: NVIDIA reported record quarterly revenue of USD 68 Billion, up 73% year over year, with Data Center revenue of USD 62 Billion, up 75%, and guided to about USD 78 Billion for the following quarter.
- December 2025: The Government of India reported that the IndiaAI Mission has deployed more than Rs 10,300 Crore, expanded compute to 38,000 GPUs, and offers GPU access at Rs 65 per hour to startups, researchers, and academia.
- September 2025: OpenAI, Oracle, and SoftBank announced five new Stargate data center sites across Texas, New Mexico, Ohio, and the Midwest, lifting planned capacity to nearly 7 gigawatts, with more than USD 400 Billion of investment planned over three years.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current global artificial intelligence market size and what is its projected value?
- Which type of AI holds the largest share in the global artificial intelligence market?
- Which offering segment (hardware, software, or services) leads global demand?
- Which region dominates the global artificial intelligence market and why?
- How are compute costs, talent shortages, data privacy rules, and fragmented regulation affecting market growth?
- Who are the top companies in the global artificial intelligence market and what are their competitive strategies?
- What are the top investment and market entry opportunities across industries such as manufacturing, healthcare, financial services, and automotive?
About Us
IMARC Group is a global management consulting firm that helps the world’s most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104