Saudi Arabia Building Materials Market Size, Growth, Trends & Forecast Report 2026-2034
The Saudi Arabia building materials market grew from USD 185.4 Billion in 2025 to USD 187.7 Billion in 2026 and is projected to reach USD 207.0 Billion by 2034, growing at a CAGR of 1.24% during 2026-2034.
 Imarc shubham
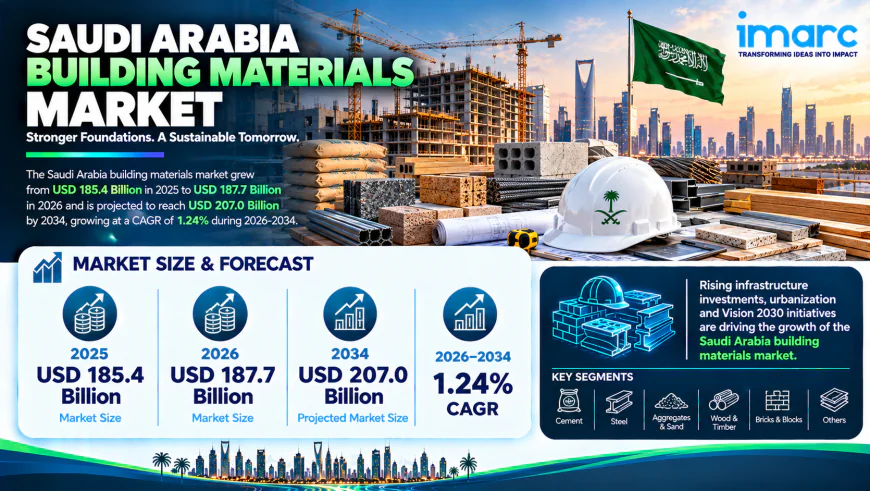
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Saudi Arabia building materials market. The Saudi Arabia building materials market size increased from USD 185.4 Billion in 2025 to USD 187.7 Billion in 2026 and is projected to reach USD 207.0 Billion by 2034, exhibiting a CAGR of 1.24% during 2026-2034, driven by sustained Vision 2030 giga-project construction activity, the National Housing Program, and PIF-backed investment in domestic building materials distribution infrastructure.
The market is holding a mature, policy-anchored growth trajectory as the Kingdom's simultaneous giga-project portfolio, National Housing Program, and PIF-backed distribution consolidation keep demand concentrated rather than cyclical. Cement remains the structural backbone of every build type, aggregates supply the volumetric bulk of concrete and road-base work, and a fast-growing specialty tier covering steel, glass, insulation, and cladding is expanding faster than commodity materials as construction quality standards rise. Riyadh and the Northern and Central region anchor the heaviest concentration of concurrent capital expenditure, while PIF's stake in Masdar for Building Materials signals a deliberate push to centralize and digitize a historically fragmented distribution landscape.
Saudi Arabia Building Materials Market at a Glance:
- Market Size (2025): USD 185.4 Billion
- Market Size (2026): USD 187.7 Billion
- Forecast Market Size (2034): USD 207.0 Billion
- CAGR (2026-2034): 1.24%
- Leading Type (2025): Cement, 36.8% share
- Leading Application (2025): Residential, 43.6% share
- Dominant Region (2025): Northern and Central Region, 38.5% share
How AI is Reshaping the Future of the Saudi Arabia Building Materials Market
- AI-Powered BIM Integration and Digital Procurement: Saudi developers and contractors are adopting BIM-integrated digital procurement platforms, such as the Elm-ROSHN ANMA marketplace, that connect manufacturers, distributors, and project teams, improving material scheduling accuracy, cutting wastage, and compressing lead times across giga-project and residential construction sites nationwide.
- Predictive Demand Forecasting and Smart Manufacturing: Cement and steel producers are deploying AI-driven production planning tools that model giga-project phasing and seasonal residential demand, helping manufacturers calibrate output, manage inventory across distribution networks, and avoid the over-capacity risk created by shifting mega-project construction timelines.
- AI-Assisted Carbon Optimization in Cement Production: Producers are applying machine-learning process controls to clinker production and supplementary cementitious material blending, lowering embodied carbon per tonne of cement while meeting Saudi Green Building Code requirements and supporting the Kingdom's push toward certified low-carbon construction materials.
Grab a sample PDF of this report: https://www.imarcgroup.com/saudi-arabia-building-materials-market/requestsample
Saudi Arabia Building Materials Market Trends and Drivers:
Vision 2030 giga-project construction is the single largest demand engine behind Saudi Arabia's building materials market, with contract awards climbing 20% to USD 196 Billion in 2025 as transportation, commercial, residential, and industrial construction collectively absorb the largest share of new activity. Cement, holding 36.8% of the type mix in 2025, continues to anchor every structural application from residential foundations to giga-project infrastructure, growing at a 1.4% CAGR as domestic production capacity and NEOM-linked supply contracts sustain throughput. Aggregates, the volumetrically largest category at 32.4% share, supply the sand, gravel, and crushed stone that make up the bulk of concrete and road-base construction, while a faster-growing specialty tier spanning steel, glass, insulation, cladding, and finishing materials is expanding as construction quality standards rise across commercial and giga-project builds through 2034.
Residential construction is the market's most consistent demand source, commanding 43.6% of application share in 2025 and growing at a 1.35% CAGR as the National Housing Program lifts Saudi homeownership past 65.4%, surpassing its original 2025 target. Roshn and other PIF-backed residential communities, alongside the Sakani affordable-housing initiative, are generating sustained large-scale consumption of cement, aggregates, bricks, and finishing materials, while organic population growth adds a steady baseline of smaller-scale residential building activity. Commercial construction follows at 34.2% share, covering offices, retail centres, hotels, and entertainment venues tied to Vision 2030 tourism and knowledge-economy programs, and industrial construction holds 22.2% share, driven by manufacturing facilities, logistics warehousing, data centre development, and petrochemical expansion projects that require heavier structural steel and specialty material inputs across the Kingdom's diversifying industrial base.
Distribution infrastructure is consolidating around a single national champion, with PIF acquiring a 30% stake in Masdar for Building Materials in February 2025 to reinforce domestic supply chains and accelerate digital transformation across a historically fragmented distributor landscape. The Northern and Central region leads regional demand at 38.5% share, anchored by Riyadh's concentration of Vision 2030 administrative programs and PIF residential developments, followed by the Western region at 30.7% on tourism, hospitality, and residential activity, the Eastern region at 19.4% on industrial and energy-sector construction, and the Southern region at 11.4% as the fastest-emerging market on infrastructure expansion. Layered on top, Saudi Arabia's Green Building Code and Green Initiative commitments are steering specification toward low-carbon cement and certified sustainable materials, creating a premium product tier for producers investing in green technology ahead of regulatory requirements.
Ask an analyst for customized report: https://www.imarcgroup.com/request?type=report&id=34690&flag=E
Government Schemes and Vision 2030 Initiatives Driving Demand:
- National Housing Program and Sakani Initiative: Saudi Arabia's Housing Program has lifted homeownership from 47% in 2016 to over 65.4%, surpassing its 2025 target, with the Sakani affordable-housing initiative and large-scale modular residential communities continuing to generate sustained building materials demand nationwide.
- Vision 2030 Giga-Project Capital Deployment: Giga-project contract awards rose 20% to USD 196 Billion in 2025, with transportation, commercial, residential, and industrial construction collectively representing the largest categories, positioning Saudi Arabia as the primary driver of global building materials supply chain planning.
- PIF Strategic Investment in Masdar: PIF's acquisition of a 30% stake in Masdar for Building Materials Company in February 2025 signals government intent to reinforce domestic supply chains, develop a national distribution network, and accelerate digital transformation across the construction materials sector.
- Saudi Green Building Code and Green Initiative: Saudi Arabia recorded the highest regional sustainability score of 76.31 points while certifying over 1.03 million square meters of sustainable building space, progressively steering material specifications toward low-carbon cement and certified green building products.
Saudi Arabia Building Materials Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Type:
- Aggregates
- Cement
- Bricks
- Others
Cement commands the largest type share at 36.8% in 2025, reflecting its foundational role in all construction applications and Saudi Arabia's position among the top countries in cement production capacity, and is growing at a 1.4% CAGR through 2034 as domestic and giga-project demand continue to sustain throughput.
Breakup By Application:
- Residential
- Commercial
- Industrial
Residential leads the application segment at 43.6% share in 2025, driven by the National Housing Program, Roshn and other PIF-backed residential communities, and organic population-driven housing demand, and is growing at a 1.35% CAGR through 2034 as homeownership targets continue to expand.
Breakup By Region:
- Northern and Central Region
- Western Region
- Eastern Region
- Southern Region
The Northern and Central Region dominates the Saudi Arabia building materials market with a 38.5% share in 2025, anchored by Riyadh's concentration of Vision 2030 administrative and residential programs. The Western Region follows at 30.7%, leveraging residential, commercial, tourism, and hospitality development, while the Eastern Region's 19.4% share reflects industrial, energy, and logistics construction activity around Dammam, and the Southern Region's 11.4% share is emerging on infrastructure expansion and regional urbanization initiatives.
Competitive Landscape:
The report provides a comprehensive analysis of the competitive landscape in the Saudi Arabia building materials market with detailed profiles of all major companies, including:
- Saudi Cement
- Masdar
- Zamil Group Holding Company
- HOLCIM
- Al Jouf Cement Company
Market Concentration Analysis:
- Moderate Concentration: Domestic cement producers collectively dominate the largest single material segment, while the structural steel rebar market benefits from integrated petrochemical feedstock advantage.
- Distribution Consolidation: PIF's investment in Masdar is progressively centralizing distribution market share around a single national network champion, replacing the fragmented regional distributor landscape that previously characterized the sector.
- Fragmented Specialty Tier: Advanced and specialty building materials segments remain considerably more fragmented, with international brands and specialty importers competing alongside domestic producers for technically demanding project specifications.
What Does The Full Report Cover?
If you are tracking the Saudi Arabia building materials market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
- Complete market sizing in value terms with forecasts covering the full 2026-2034 projection period
- Quantified growth driver analysis with impact scoring across type, application, and regional markets
- Sub-segment breakdowns for aggregates, cement, bricks, and other material types, all three application categories, and all four regions of the Kingdom, each with individual share data
- Regional data across the Northern and Central, Western, Eastern, and Southern regions of Saudi Arabia
- Competitive profiles of leading domestic and international building materials producers with strategic landscape assessment
- Value chain analysis, market concentration assessment, and investment and growth opportunity mapping
- Latest technology trends covering BIM-integrated procurement, 3D printing and additive construction, carbon-negative materials, and Vision 2030-driven infrastructure opportunities shaping market competition across the Kingdom
Recent News and Developments in Saudi Arabia Building Materials Market
- August 2026: Masdar opened a fully integrated construction and building materials facility in Madinah, supplying steel, timber, insulation, plumbing, electrical products, hardware, chemicals, and fasteners, reflecting a growing trend toward one-stop building material supply solutions across the Kingdom.
- September 2026: Elm and ROSHN Group partnered to launch ANMA, an integrated B2B digital platform connecting developers, contractors, manufacturers, and suppliers to improve procurement efficiency and strengthen supply-chain integration across the Saudi construction sector.
- January 2025: Saudi Arabia launched the NovusCrete Consortium, an initiative focused on advancing sustainable concrete production and reducing carbon emissions, supporting the adoption of lower-carbon building materials across the construction sector.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current Saudi Arabia building materials market size and what is its projected value?
- Which type segment holds the largest share in the Saudi Arabia building materials market?
- What are the key drivers of Saudi Arabia building materials market growth?
- Which region dominates the Saudi Arabia building materials market and why?
- How is Vision 2030, the National Housing Program, and PIF investment reshaping distribution infrastructure and competitive strategy in the Saudi Arabia building materials industry?
- Who are the top companies in the Saudi Arabia building materials market and what are their competitive strategies?
- What are the investment and market entry opportunities across specialty materials manufacturing, digital distribution, and green building materials in Saudi Arabia?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104