Rigid Plastic Packaging Market Size to Reach USD 372.0 Billion by 2034, Growing at 3.90% CAGR
The global rigid plastic packaging market size was valued at USD 260.8 Billion in 2025. Looking forward, IMARC Group estimates the market to reach USD 372.0 Billion by 2034.
 Robertmarketresearcher
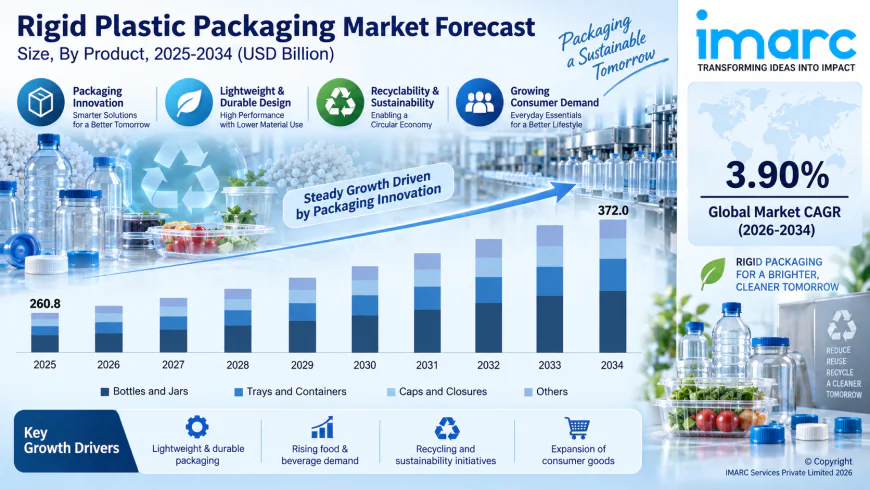
According to a research report by IMARC Group, the global rigid plastic packaging market size reached USD 260.8 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 372.0 Billion by 2034, exhibiting a growth rate (CAGR) of 3.90% during 2026-2034. Asia Pacific currently leads the regional landscape, accounting for over 39.7% of the market share in 2025. The market is primarily driven by the rising focus among key players on product safety and extended shelf life, increasing preference for sustainable packaging solutions, growing demand for durable and lightweight packaging, and continued advancements in plastic manufacturing technologies.
Rigid Plastic Packaging Market Report: Key Highlights
-
Market Size & Growth: The global rigid plastic packaging market reached USD 260.8 Billion in 2025 and is projected to reach USD 372.0 Billion by 2034, registering a CAGR of 3.90% during 2026–2034, according to IMARC Group.
-
Regional Leadership: Asia Pacific represents the largest regional market, accounting for over 39.7% of the market share in 2025, supported by sustainability initiatives, rising demand for durable packaging, and expanding end-use industries.
-
By Product: The market is segmented into bottles and jars, trays and containers, caps and closures, and others, with bottles and jars representing the largest segment at around 40.5% of the market in 2025.
-
By Material: The market covers polyethylene (PET), polypropylene (PP), high density polypropylene (HDPE), and others, with polypropylene accounting for around 24.7% of the market share in 2025.
-
By Production Process: The market is divided into extrusion, injection molding, blow molding, thermoforming, and others, with extrusion holding the leading share.
-
By End Use Industry: The market spans food and beverages, personal care and cosmetics, household, healthcare, and others, with food and beverages accounting for around 35.7% of the market share in 2025.
-
Key Market Drivers: Rising demand for durable and lightweight packaging, expansion of e-commerce and global trade, growing focus on product safety and extended shelf life, and advancements in plastic manufacturing technologies.
-
Key Market Trends: Increasing adoption of sustainable packaging solutions, growing demand for convenient packaging formats, integration of smart packaging technologies, and rising use of recycled and bio-based plastics.
-
Key Market Challenges: The growing need to balance packaging performance and sustainability requirements, alongside increasing regulatory and environmental pressures related to plastic waste.
-
Emerging Opportunities: Advanced recycling, post-consumer recycled plastics, biodegradable materials, smart packaging, lightweighting, and technological advancements in manufacturing processes.
Request for a Sample Report for Detailed Evaluation: https://www.imarcgroup.com/rigid-plastic-packaging-market/requestsample
What Is Driving Rigid Plastic Packaging Market Growth in 2026?
Introduction of Sustainable Packaging Solutions
The rising consumer environmental consciousness is encouraging manufacturers to adopt recyclable and biodegradable materials, which is propelling the rigid plastic packaging market. Government bodies and industry players are increasingly emphasizing the minimization of plastic waste, thereby promoting the usage of materials with a lower environmental impact.
Prominent companies are also incorporating recycled content into rigid plastic packaging by utilizing industrial scrap and post-consumer recycled (PCR) plastics. These initiatives are helping reduce reliance on virgin materials and divert plastic waste from landfills. In February 2024, Amcor signed a deal with Cadbury Australia, a subsidiary of Mondelēz International, to supply approximately 1,000 tons of post-consumer recycled plastic to wrap the company's core chocolate product range. Such initiatives are supporting the transition toward more sustainable packaging solutions.
Increasing Demand for Convenience
The growing preference for packaging that preserves product quality while providing portability is supporting the demand for rigid plastic packaging. Rigid plastic offers durability and versatility, making it suitable for a wide range of products and consumer applications.
Resealable closures, including screw caps and flip-tops, are widely used on rigid plastic containers for products such as condiments, beverages, and personal care items. These closures help preserve product freshness and prevent spills, thereby contributing to convenience and extended shelf life. In April 2024, Guillin Group's Fresh Produce business unit launched innovative rPET, carton, and hybrid solutions designed to offer consumer convenience without compromising product quality.
The growing popularity of on-the-go packaging formats is further stimulating market demand across food and beverages, personal care, and other consumer-oriented applications.
Introduction of Smart Packaging
Rigid plastic packaging is playing an important role in the development and implementation of smart packaging solutions. Smart packaging technologies can enable interactive consumer experiences through features such as augmented reality (AR) and personalized content accessible through smartphone applications.
Such technologies can improve consumer engagement and support brand loyalty. According to a recent survey cited in the report, 74% of consumers mentioned product quality as inspiring loyalty, while 66% valued value for money and 56% considered customer service important. Rising investments in research and development activities are consequently supporting innovation in smart and technologically advanced packaging solutions.
Expansion of E-Commerce and Global Trade
The rapid expansion of e-commerce and global trade is boosting demand for rigid plastic packaging that can provide safe and secure product delivery. Durable and lightweight packaging solutions help protect products during transportation while supporting efficient handling and shipping.
According to IMARC Group, the global e-commerce market size reached USD 26.8 Trillion in 2024 and is forecasted to reach USD 214.5 Trillion by 2033, exhibiting a CAGR of 25.83% during 2025-2033. The continued expansion of online commerce is therefore creating additional demand for impact-resistant, lightweight, and reliable packaging formats across multiple industries.
Advancements in Plastic Manufacturing Technologies
Advancements in manufacturing technologies, including injection molding and thermoforming, are enhancing design flexibility, production efficiency, and packaging performance. These technologies enable manufacturers to produce customized packaging designs while optimizing material usage and production processes.
Continuous innovation in manufacturing processes is allowing companies to develop packaging solutions with improved functionality, durability, and visual appeal. Such developments are supporting the expansion of rigid plastic packaging applications across food and beverages, healthcare, personal care, household products, and other industries.
Rigid Plastic Packaging Market Segmentation Analysis
By Product
-
Bottles and Jars
-
Trays and Containers
-
Caps and Closures
-
Others
Bottles and jars represent the largest product segment, accounting for around 40.5% of the market in 2025. The rising focus among key players on branding and product differentiation is supporting the growth of this segment. Bottles and jars provide product protection, visibility, and easy dispensing, thereby improving consumer convenience and helping maintain product freshness.
Manufacturers are also prioritizing efficient packaging solutions to meet evolving consumer and industry requirements. In January 2022, Ring Container Technologies launched a customizable PET solution designed to maintain carbonation in beverages. Similarly, Vetroplas offers a range of packaging solutions specializing in premium glass and plastic bottles and jars, with a focus on quality and sustainability.
By Material
-
Polyethylene (PET)
-
Polypropylene (PP)
-
High Density Polypropylene (HDPE)
-
Others
Polypropylene (PP) leads the market by material, accounting for around 24.7% of the market share in 2025. PP is gaining widespread popularity due to properties such as chemical resistance, high stiffness, and low density. These characteristics make it suitable for manufacturing durable and lightweight rigid plastic packaging solutions.
Innovations in manufacturing processes are further supporting opportunities within this segment. In February 2024, Ravago and Repsol inaugurated a factory in Tangier dedicated to producing polypropylene compounds, a material widely used in the automotive sector. In March 2024, GEKA, one of Medmix's beauty brands, introduced a post-consumer-recycled polypropylene material suitable for primary cosmetic packaging.
By Production Process
-
Extrusion
-
Injection Molding
-
Blow Molding
-
Thermoforming
-
Others
Extrusion accounts for the majority of the market share. The process plays an important role in driving innovation and production efficiency by enabling the manufacturing of various packaging components, including containers, bottles, and caps, with precision and consistency.
Extrusion also allows manufacturers to incorporate features such as handles and closures, create intricate designs, and optimize wall thickness to balance cost-effectiveness and durability. Continuous collaborations and acquisitions in the extrusion equipment industry are supporting technological development. In October 2023, Davis-Standard, LLC acquired the Extrusion Technology Group (ETG) from entities controlled by Dutch investor Nimbus.
By End Use Industry
-
Food and Beverages
-
Personal Care and Cosmetics
-
Household
-
Healthcare
-
Others
Food and beverages represent the leading end-use industry, accounting for around 35.7% of the market share in 2025. The escalating demand for functional and durable packaging solutions across the food and beverage sector is supporting market growth.
Prominent industry players are increasingly using sustainable packaging materials to address environmental concerns. In November 2023, Nestlé invested in Impact Recycling's facility to support hard-to-recycle plastic management and advance environmental initiatives. In April 2024, a study by Tetra Pak highlighted a shift within the food and beverage industry toward greater prioritization of sustainable practices.
The wide presence of companies catering to the growing trend of on-the-go consumption is also expected to support demand for rigid plastic packaging in this segment.
By Region
-
North America
-
United States
-
Canada
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Indonesia
-
Others
-
-
Europe
-
Germany
-
France
-
United Kingdom
-
Italy
-
Spain
-
Russia
-
Others
-
-
Latin America
-
Brazil
-
Mexico
-
Others
-
-
Middle East and Africa
Asia Pacific accounted for the largest market share of over 39.7% in 2025. Government bodies across the region are implementing regulations and initiatives to promote a circular economy, which is supporting the adoption of sustainable rigid plastic packaging.
In February 2022, government bodies in India notified new Extended Producer Responsibility (EPR) guidelines under the Plastic Waste Management Rules. These guidelines placed statutory responsibilities on manufacturers to recycle, collect, and reuse used plastic packaging and incorporate recycled content into new plastic packaging. Such initiatives are supporting improved packaging sustainability and encouraging manufacturers to explore advanced recycling solutions.
North America, Europe, Latin America, and the Middle East and Africa also represent important regional markets, supported by demand across food and beverages, healthcare, personal care, e-commerce, and other end-use industries.
Key Regional Insight: Asia Pacific's Strategic Position
Asia Pacific's leading position in the global rigid plastic packaging market is supported by rising demand for lightweight and durable packaging solutions across food and beverages, personal care, pharmaceuticals, and other industries. Manufacturers are increasingly adopting rigid plastic packaging because of its ability to provide product protection, extended shelf life, and cost-effective transportation.
The region's growing e-commerce industry is also creating demand for packaging that can ensure safe product delivery. At the same time, governments and industry participants are increasing their focus on sustainability, recycling, reusable plastics, and biodegradable materials. Continued investment in advanced recycling partnerships and packaging technologies is expected to support the region's market position through 2034.
Key Regional Takeaways
United States Rigid Plastic Packaging Market Analysis
The United States accounts for over 80% of the rigid plastic packaging market in North America. The market is being supported by increasing demand for lightweight, durable, and cost-effective packaging across food and beverages, healthcare, personal care, and other industries.
Manufacturers are increasingly adopting lightweight materials that provide durability while addressing consumer demand for sustainable and environmentally friendly packaging. Regulatory pressures and environmental concerns are further encouraging the use of recycled and alternative materials.
The food and beverage sector is witnessing growing demand for packaging capable of supporting long shelf life, freshness, and convenience, particularly for ready-to-eat and grab-and-go products. Healthcare and pharmaceutical companies are also adopting rigid plastic containers due to their tamper-evident characteristics and suitability for medical products and devices.
Technological advancements in packaging manufacturing are enabling customized designs and improved functionality, supporting branding and product differentiation strategies. In addition, e-commerce expansion is increasing demand for impact-resistant and lightweight packaging solutions that can help reduce shipping costs and product damage during transportation.
Companies are also investing in post-consumer recycled plastics and bio-based alternatives to address sustainability objectives and changing consumer expectations.
Asia Pacific Rigid Plastic Packaging Market Analysis
The Asia Pacific rigid plastic packaging market is being driven by increasing demand for lightweight and durable packaging solutions across food and beverages, personal care, pharmaceuticals, and other industries. Manufacturers are shifting toward rigid plastic packaging because of its ability to offer product protection, prolonged shelf life, and cost-effective transportation.
The food and beverage sector is rapidly adopting rigid plastic packaging for products such as ready-to-eat meals, dairy products, and carbonated beverages, aligning with the growing preference for convenience foods. Rigid plastic containers also offer a premium appearance, which is supporting their adoption across personal care and cosmetics markets in rapidly urbanizing areas.
Pharmaceutical companies are increasingly using rigid plastic packaging to meet regulatory requirements and maintain product integrity. Meanwhile, the expansion of e-commerce in densely populated markets such as China and India is increasing the need for packaging capable of ensuring safe product delivery.
Sustainability is also becoming increasingly important, with companies incorporating reusable plastics, recycled materials, and biodegradable packaging solutions into their operations.
Europe Rigid Plastic Packaging Market Analysis
The European rigid plastic packaging market is witnessing growth amid increasing demand for sustainable packaging solutions and stringent environmental regulations. Manufacturers are increasingly adopting recyclable and bio-based rigid plastic materials to address packaging waste requirements and changing consumer preferences.
The food and beverage industry represents an important application area, with rigid plastic containers gaining prominence because of their durability, lightweight characteristics, and ability to preserve product freshness. Companies are also investing in advanced manufacturing technologies, including injection molding and thermoforming, to improve production efficiency and develop new packaging designs.
The expansion of e-commerce across Europe is further supporting demand for robust and lightweight packaging, particularly for personal care and household products where secure transportation is important. The pharmaceutical and healthcare sectors are also using rigid plastic packaging to maintain product integrity and meet safety requirements.
Digital printing technologies are additionally enabling customized and visually attractive packaging, supporting brand recognition and consumer engagement.
Latin America Rigid Plastic Packaging Market Analysis
The Latin American rigid plastic packaging market is being supported by increasing adoption of sustainable and recyclable materials as governments and industries intensify efforts to address environmental concerns. The growing preference for convenience in the food and beverage industry is also encouraging the adoption of efficient packaging solutions.
Technological developments such as lightweighting and enhanced barrier properties are helping improve packaging efficiency and product shelf life. At the same time, e-commerce penetration is creating greater demand for durable and protective packaging solutions capable of safely transporting products to consumers.
The expansion of personal care and pharmaceutical industries is further supporting demand for rigid plastic packaging due to its tamper-evident characteristics and aesthetic flexibility. Manufacturers are also developing diversified packaging designs to address growing demand in cosmetics and beauty markets.
Partnerships with local suppliers are helping companies improve cost efficiency and simplify supply chains amid fluctuations in resin prices and regional trade complexities.
Middle East and Africa Rigid Plastic Packaging Market Analysis
The demand for rigid plastic packaging is increasing across the Middle East and Africa, driven by the expansion of food and beverages, personal care, healthcare, and pharmaceutical industries. The need to enhance product shelf life in hot climatic conditions is supporting the use of rigid plastic packaging with suitable barrier properties.
Manufacturers are increasingly focusing on innovative, recyclable, and sustainable plastics to address environmental regulations and growing consumer demand for eco-friendly packaging. The expansion of e-commerce is also increasing demand for rigid plastic packaging suitable for the safe transportation and storage of products.
Businesses are adopting attractive and customized packaging designs to strengthen brand differentiation. Pharmaceutical packaging is also witnessing continued demand, with companies incorporating features such as tamper-evident and child-resistant packaging to enhance product safety.
Growing urban populations and increasing disposable incomes are further supporting demand across various end-use industries, while developments in manufacturing technologies are improving cost-effectiveness and production efficiency.
Competitive Landscape in the Rigid Plastic Packaging Industry
Key players in the global rigid plastic packaging market are focusing on product innovation, sustainability initiatives, advanced manufacturing technologies, and strategic collaborations to strengthen their market positions. Companies are investing in recycled and bio-based plastics to align with environmental regulations and increasing consumer demand for sustainable packaging.
Collaborations and partnerships with companies in the food, beverage, healthcare, and other industries are enabling the development of customized packaging solutions. Expansion into emerging markets and the establishment of regional production facilities are also helping improve supply chain efficiency and address rising demand.
Additionally, companies are adopting digital technologies, including IoT-enabled smart packaging, to enhance product traceability and consumer engagement. These developments are contributing to continued innovation and competitiveness across the global rigid plastic packaging industry.
Key Rigid Plastic Packaging Market Players Include:
-
ALPLA
-
Altium Packaging LLC
-
Amcor plc
-
Berry Global Inc.
-
DS Smith plc
-
Graham Packaging Company
-
Pactiv Evergreen Inc.
-
Plastipak Holdings Inc.
-
Saudi Basic Industries Corporation (Saudi Arabian Oil Company)
-
Silgan Holdings Inc.
-
Sonoco Products Company
-
Winpak Ltd.
Note: The above represents a partial list of companies covered in the report. The complete competitive landscape is provided in the full report.
Recent Developments:
-
In February 2024, Amcor signed a deal with Cadbury Australia, a subsidiary of Mondelēz International, to supply approximately 1,000 tons of post-consumer recycled (PCR) plastic for wrapping the company's core chocolate product range. The initiative is aimed at helping Cadbury reduce its reliance on virgin plastic for packaging.
-
In March 2024, AYR-based Emmer Ltd launched a new 17.5-liter rigid plastic packaging container. The company has been designing and manufacturing bespoke containers since 2009, with the latest product comprising an off-the-shelf plastic bucket and lid measuring 333 x 330 mm.
-
In April 2024, Amcor launched a polyethylene terephthalate (PET) bottle for carbonated soft drinks made from 100% post-consumer recycled (PCR) content. The one-liter CSD bottle expanded Amcor Rigid Packaging's portfolio of packaging solutions incorporating recycled content.
-
In July 2024, Versalis, Eni's chemical company, and Forever Plast, an Italian post-consumer plastic recycling company, introduced REFENCE, a range of recycled polymers for food-contact packaging. The range is available for polystyrene applications including yogurt pots, meat and fish trays, and other rigid and expanded packaging.
Market Drivers, Challenges & Opportunities
Major Market Drivers:
-
Growing Demand for Durable and Lightweight Packaging: Increasing demand across food and beverages, healthcare, personal care, and other industries is supporting the adoption of rigid plastic packaging.
-
Expansion of E-Commerce: Rising online commerce is increasing the need for durable packaging capable of protecting products during transportation and delivery.
-
Focus on Product Safety and Shelf Life: Rigid plastic packaging provides product protection and supports freshness and extended shelf life across multiple applications.
-
Advancements in Manufacturing Technologies: Developments in extrusion, injection molding, blow molding, and thermoforming are improving production efficiency and design flexibility.
-
Growing Sustainability Focus: Increasing consumer and regulatory emphasis on recycling and environmentally responsible packaging is encouraging the development of recycled and bio-based rigid plastics.
Key Challenges:
-
Plastic Waste and Environmental Concerns: Increasing regulatory and consumer attention toward plastic waste is creating pressure on manufacturers to develop more sustainable packaging solutions.
-
Balancing Performance and Sustainability: Manufacturers need to maintain durability, functionality, product protection, and shelf life while increasing recycled and alternative material content.
-
Changing Regulatory Requirements: Evolving environmental regulations across different markets add complexity to packaging design, material selection, and production.
Emerging Opportunities:
-
Recycled and Bio-Based Plastics: Growing demand for sustainable packaging is creating opportunities for companies developing recycled, biodegradable, and bio-based rigid plastic materials.
-
Smart Packaging: Integration of digital technologies, including IoT and interactive features, is creating opportunities for enhanced traceability and consumer engagement.
-
Advanced Recycling: Increasing investment in recycling infrastructure and partnerships is creating opportunities for improved management and reuse of plastic packaging.
-
E-Commerce Packaging: Continued growth in online commerce is generating demand for lightweight, durable, and impact-resistant packaging solutions.
-
Innovative Manufacturing Technologies: Advances in extrusion, injection molding, blow molding, and thermoforming are creating opportunities for improved efficiency, customization, and packaging performance.
Rigid Plastic Packaging Market FAQs
1. What is the current size of the rigid plastic packaging market?
The global rigid plastic packaging market reached USD 260.8 Billion in 2025 and is expected to grow at a CAGR of 3.90% during 2026-2034, reaching USD 372.0 Billion by 2034.
2. What is driving the growth of the rigid plastic packaging market?
The market is driven by increasing demand for durable and lightweight packaging, expansion of e-commerce and global trade, rising focus on product safety and extended shelf life, advancements in plastic manufacturing technologies, and growing preference for sustainable packaging solutions.
3. Which region dominates the rigid plastic packaging market?
Asia Pacific leads the global rigid plastic packaging market, accounting for over 39.7% of the market share in 2025. The regional market is supported by rising demand across food and beverages, personal care, pharmaceuticals, and other industries, alongside growing sustainability initiatives and e-commerce activity.
4. Which segment holds the largest share in the rigid plastic packaging market?
Bottles and jars represent the largest product segment, accounting for around 40.5% of the market in 2025. Polypropylene leads by material with around 24.7%, extrusion is the leading production process, and food and beverages represent the largest end-use industry with around 35.7% of the market share.
5. What are the key trends in the rigid plastic packaging market?
Key trends include the increasing introduction of sustainable packaging solutions, growing use of recycled and bio-based plastics, rising demand for convenient packaging, introduction of smart packaging technologies, expansion of e-commerce, and continued advancements in plastic manufacturing processes.
Conclusion: Rigid Plastic Packaging Market Outlook to 2034
The global rigid plastic packaging market is set for steady growth through 2034, supported by increasing demand for durable and lightweight packaging across food and beverages, healthcare, personal care, household, and other industries. The expansion of e-commerce, growing focus on product safety and extended shelf life, and advancements in manufacturing technologies are further supporting market development.
At the same time, the increasing emphasis on sustainability is encouraging manufacturers to adopt recycled, recyclable, biodegradable, and bio-based materials. The development of smart packaging technologies and advanced recycling solutions is also creating new opportunities across the industry.
With Asia Pacific maintaining its position as the leading regional market and North America, Europe, Latin America, and the Middle East and Africa offering further growth avenues, the outlook through 2034 remains positive. Companies investing in sustainable materials, advanced manufacturing processes, smart packaging technologies, and innovative recycling solutions will continue to play an important role as the rigid plastic packaging industry evolves alongside changing consumer, regulatory, and environmental requirements.
About the Author:
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Energy and Mining, Construction and Manufacturing, Automotive, Chemicals and Materials, and more.
Media & Sales Contact:
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104