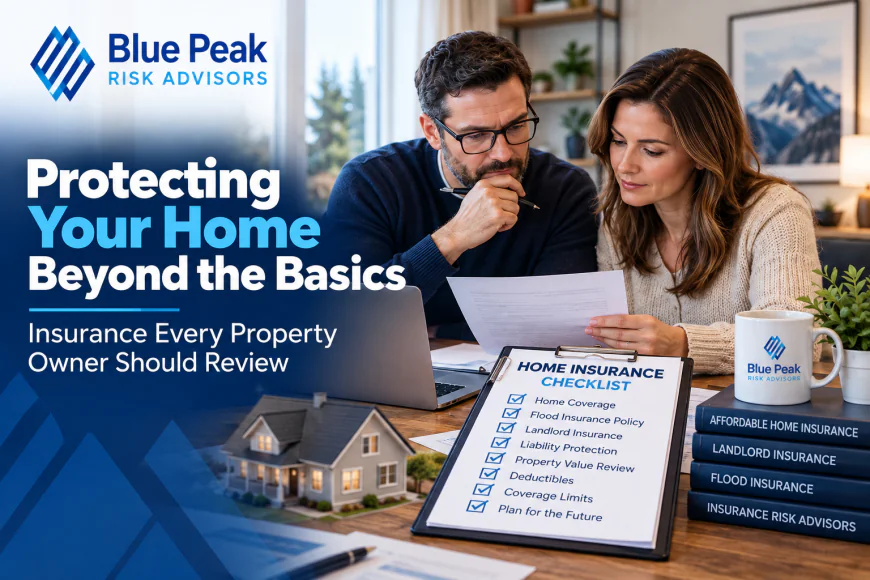
Protecting Your Home Beyond the Basics: Coverage Every Property Owner Should Review
Protect your property with the right home, landlord, and flood insurance. Learn what homeowners should review to avoid coverage gaps.
 michael jeff
Owning a home is a major financial responsibility. Whether you live in the property yourself, rent it to tenants, or own a home in an area exposed to flooding, the right insurance strategy can help protect both the property and your finances.
Many homeowners focus mainly on price when comparing policies. Cost matters, but the cheapest option does not always provide the protection a property owner expects. A better approach is to understand the risks connected with the property, review coverage limits, and make sure the policy still reflects the way the home is currently being used.
From affordable home insurance to rental-property and flood protection, different policies can address very different types of risk.
Why Home Insurance Should Be Reviewed Regularly
A home can change significantly over time.
You may replace the roof, remodel the kitchen, finish a basement, install a pool, build a detached garage, or purchase expensive furniture and electronics. These improvements can increase the amount it would cost to repair or rebuild the property after a covered loss.
At the same time, insurance markets, construction costs, deductibles, and coverage options can also change.
A policy purchased several years ago may still be active, but that does not automatically mean the limits and terms are still appropriate today.
Regular reviews can help homeowners look at:
- Dwelling coverage
- Personal property limits
- Liability protection
- Deductibles
- Policy exclusions
- Additional living expense coverage
- Optional endorsements
The purpose is not simply to purchase more insurance. It is to understand whether the protection currently in place still matches the property and the risks surrounding it.
Finding Affordable Coverage Without Focusing Only on Price
Everyone wants reasonable insurance costs.
However, there is an important difference between affordable coverage and simply selecting the lowest premium available.
Two home insurance policies can have similar prices while providing different limits, deductibles, exclusions, and conditions.
For example, one policy may have a lower annual premium but a much higher deductible. Another may provide different protection for the roof, personal property, water damage, or certain weather-related events.
Homeowners should therefore compare the complete policy rather than looking at one number.
Questions worth asking include:
- What is the dwelling limit?
- How high is the deductible?
- How is personal property valued?
- What losses are excluded?
- Are there separate deductibles for certain events?
- Are valuable belongings subject to special limits?
- How does the policy handle temporary living expenses?
These details can have a major impact when a claim occurs.
Homeowners and Landlords Face Different Risks
A property occupied by the owner is not the same as a property rented to tenants.
The risks can be different because the owner is no longer living in the home and the property is being used as part of a rental activity.
This is where landlord insurance can become relevant.
Landlord coverage may help address certain risks associated with tenant-occupied properties, depending on the policy.
For example, a landlord may need to consider protection for the structure itself, liability exposure, property owned by the landlord, and certain loss-of-rental-income situations after a covered event.
The exact coverage depends on the insurer and policy terms.
Why a Standard Homeowners Policy May Not Be Enough for a Rental
A common mistake is assuming that a homeowners policy will automatically continue working the same way after a home becomes a rental.
That may not always be the case.
The use of the property is an important part of insurance underwriting. A home occupied by its owner may be treated differently from a property occupied by tenants.
If you move out of a home and begin renting it, that change should be discussed with the insurer or advisor.
Similarly, rental-property owners should review coverage after:
- Changing tenants
- Renovating the property
- Adding another rental unit
- Increasing the value of the property
- Purchasing additional rental homes
- Changing the way the property is used
Keeping policy information accurate helps reduce confusion and potential coverage issues later.
Liability Protection Matters for Property Owners
Property ownership can create liability exposures.
Someone could fall on the property, be injured on a walkway, or claim that unsafe conditions caused harm.
Features such as pools, fences, pets, stairs, rental units, and recreational equipment can also influence liability risk.
This is why liability limits should be reviewed along with property coverage.
Property owners with significant assets may also want to understand how their home, rental, auto, and other liability policies work together.
Working with experienced insurance risk advisors can help homeowners and property owners review these areas and understand where one policy may end and another type of protection may become relevant.
Flooding Requires Special Attention
Water damage is one of the areas that often creates confusion for homeowners.
Not every type of water damage is treated the same way under an insurance policy.
A standard homeowners policy may address certain sudden and accidental water losses, depending on the cause and policy terms. Flooding caused by rising surface water, however, is typically treated differently.
That is why homeowners should not automatically assume their standard policy protects them from every flood-related event.
A separate flood insurance policy may be necessary for certain flood exposures.
Who Should Consider Flood Insurance?
Flood risk is not limited only to properties located directly next to rivers or oceans.
Heavy rain, drainage problems, overflowing waterways, storm systems, and changing development patterns can affect areas that homeowners may not traditionally think of as high-risk.
Property owners should understand whether their area has flood exposure and whether their current insurance arrangement addresses it.
Questions to consider include:
- Is the home located in or near a flood-prone area?
- Has the surrounding area experienced flooding before?
- Is the property located near a river, creek, lake, or low-lying area?
- Does the current homeowners policy exclude flood damage?
- What would it cost to repair the property after significant flooding?
Understanding these risks before a loss occurs is much easier than discovering a coverage gap afterward.
Rebuilding Cost Is Different From Market Value
Another area that can create confusion is home value.
The market value of a property and the cost to rebuild it are not necessarily the same.
Market value can be influenced by land, neighborhood demand, local real estate trends, school districts, and other factors.
Rebuilding cost focuses on what it would take to reconstruct the home after a major covered loss.
Labor costs, materials, local building codes, demolition, and specialized construction can all influence that amount.
That is why homeowners should not assume that the purchase price of the property is the correct amount of dwelling coverage.
Review Personal Property Too
The structure of the home is only one part of the insurance picture.
Most households accumulate a significant amount of personal property over time.
Furniture, electronics, appliances, clothing, jewelry, tools, collectibles, and other belongings can represent substantial value.
A homeowner should periodically review what they own and determine whether policy limits still make sense.
Certain categories of personal property may also have special limits.
High-value jewelry, artwork, collectibles, or specialized equipment may require additional consideration depending on the policy.
Keeping a home inventory can make this process much easier.
Photos, receipts, serial numbers, and purchase records can help create a clearer record of valuable belongings.
Deductibles Can Affect the Real Cost of Insurance
Premiums receive a lot of attention when people shop for coverage.
Deductibles are equally important.
A deductible is generally the amount the policyholder is responsible for before insurance begins paying according to the policy terms.
Higher deductibles can sometimes reduce the premium, but they also increase the amount you may need to pay after a covered loss.
Ask yourself whether the deductible would be financially manageable if you had to pay it tomorrow.
Some policies may also have different deductibles for certain events, so homeowners should understand whether more than one deductible structure applies.
Major Life Changes Should Trigger a Policy Review
Insurance needs often change because life changes.
Homeowners should consider reviewing their policies after events such as:
- Purchasing a new home
- Moving
- Getting married
- Renovating the property
- Renting the home
- Purchasing another property
- Adding valuable belongings
- Installing a pool
- Starting a home-based business
- Paying off the mortgage
- Changing how the property is used
These changes can affect property values, liability, and the type of coverage that may be appropriate.
Rental Property Owners Should Review Income Exposure
Landlords have another financial concern that owner-occupants generally do not: rental income.
If a rental home becomes uninhabitable after a covered event, the owner may temporarily lose rental income while repairs are made.
Depending on the policy, certain landlord insurance arrangements may include protection for qualifying loss-of-rent situations.
Property owners should review how this coverage works, how long it may apply, and what conditions must be met.
Again, policy details matter.
Do Not Wait Until a Claim to Understand the Policy
The worst time to discover an exclusion, low limit, or coverage gap is after a major loss.
Homeowners and landlords should understand the key parts of their policies before a claim occurs.
A useful annual review can include:
- Dwelling limits
- Deductibles
- Personal property
- Liability limits
- Rental-property use
- Flood exposure
- Valuable belongings
- Property improvements
- Additional structures
- Policy exclusions
- Major changes made during the year
Even a short review can reveal information that has become outdated.
Final Thoughts
Homeownership comes with both financial opportunity and financial responsibility.
A policy that worked several years ago may not automatically remain the right fit after renovations, increasing property values, lifestyle changes, rental activity, or new flood concerns.
The goal should not be to buy every type of coverage available. Instead, property owners should understand their biggest exposures and make sure their insurance reflects how the property is used today.
Homeowners may want to review home coverage for the structure and belongings, landlords should consider the risks associated with tenant-occupied property, and property owners in flood-exposed areas should understand how flood losses are treated.
Regular reviews can help identify gaps before those gaps become expensive problems.
Ultimately, the strongest insurance strategy is one that balances cost, coverage, deductibles, and real-world risks rather than focusing on price alone.