Philippines Chocolate Market Analysis Report 2026-2034
The Philippines chocolate market size reached USD 751.50 Million in 2025 and is projected to reach USD 1,198.71 Million by 2034, at a CAGR of 4.78%.
 Arlo Bennett
Market Overview
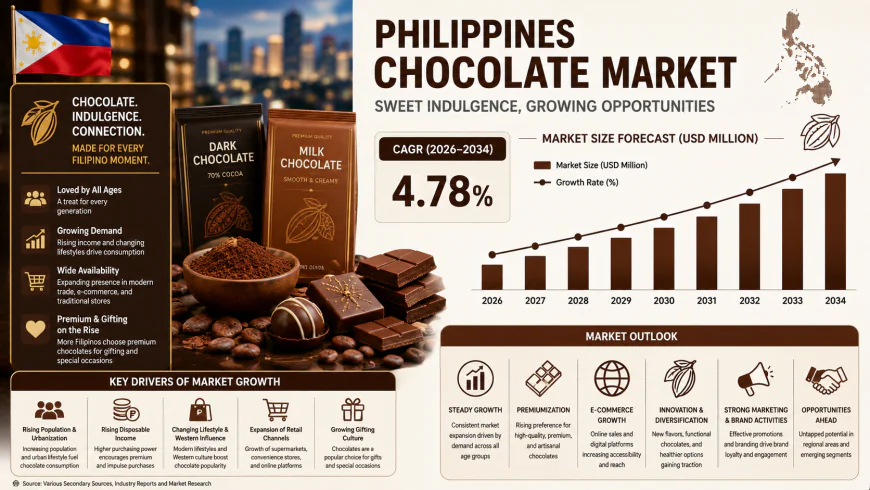
The Philippines chocolate market size reached USD 751.50 Million in 2025 and is projected to reach USD 1,198.71 Million by 2034, growing at a compound annual growth rate (CAGR) of 4.78% from 2026 to 2034. The market is driven by premium and artisanal chocolate demand, e-commerce growth, and domestic cacao production backed by government support.
Philippines Chocolate Market Summary
- The Philippines chocolate market covers white, milk, dark, and other chocolate, in molded, countline, and other forms, used in confectionery, bakery, desserts, and beverages.
- Chocolate is valued as an everyday treat, a gift and seasonal item, and an ingredient, with a growing premium and craft segment.
- The ecosystem includes cacao farmers, chocolate makers and bean-to-bar craftspeople, multinational and local confectioners, distributors, supermarkets and convenience stores, online sellers, food manufacturers, and consumers.
- Major segments identified in the market include product type (white, milk, dark, others), product form (molded, countlines, others), application, pricing (everyday, premium, seasonal), distribution, and region. IMARC does not give shares for these.
- IMARC cites the Department of Agriculture’s Cacao Industry Development Roadmap, which supports farmer training, seedlings, and post-harvest infrastructure.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/philippines-chocolate-market/requestsample
PORTER’S FIVE FORCES ANALYSIS
- Competitive Rivalry: Moderate to High. Multinational brands, local confectioners, and craft makers compete on price, taste, and brand. Business implication: Differentiate through flavors, origin stories, and gifting formats.
- Supplier Power (Cacao and Ingredients): Moderate to High. Cocoa prices swing globally, and local cacao supply is still small. Business implication: Build farmer partnerships and secure long-term supply.
- Buyer Power (Retailers and Consumers): Moderate to High. Supermarkets and convenience stores control shelf space, and shoppers switch brands easily. Business implication: Win listings and promotions, and build loyalty through premium ranges.
- Threat of Substitutes: Moderate. Other sweets, biscuits, and snacks compete for the same occasions. Business implication: Position chocolate for gifting, indulgence, and ingredient use.
- Threat of New Entrants: Moderate. Small craft makers enter easily online, but scale distribution is hard. Business implication: Build brand stories and online channels early.
MARKET GROWTH DRIVERS
Premium and Artisanal Demand
Rising disposable incomes and interest in craft, bean-to-bar, single-origin, and organic chocolate are lifting demand for higher-priced products. Consumers are trading up for quality and provenance, and local makers use Philippine cacao to create distinctive flavors, which expands the premium segment beyond everyday mass-market chocolate.
E-Commerce Growth
Online channels make it easier for small and premium brands to reach shoppers nationwide and for consumers to find gifts and specialty items. IMARC projects the Philippines e-commerce market to reach USD 75.59 billion by 2033, and online stores widen distribution beyond supermarkets and convenience stores.
Domestic Cacao and Government Support
The Department of Agriculture’s Cacao Industry Development Roadmap supports farmer training, seedlings, and post-harvest infrastructure. Better local supply helps chocolate makers source traceable beans, supports bean-to-bar brands and exports, and strengthens the link between Philippine cacao farmers and the premium chocolate products consumers increasingly seek.
PHILIPPINES CHOCOLATE MARKET SEGMENTATION
Product Type Insights:
- White
- Milk
- Dark
- Others
Product Form Insights:
- Molded
- Countlines
- Others
Application Insights:
- Food Products (Bakery, Sugar Confectionery, Desserts, Others)
- Beverages
- Others
Pricing Insights:
- Everyday
- Premium
- Seasonal
Distribution Channel Insights:
- Direct B2B Sales
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Stores
- Others
Regional Insights:
- Luzon
- Visayas
- Mindanao
COMPETITIVE LANDSCAPE
The Philippines chocolate market includes multinational and local confectioners, bean-to-bar craft makers, and food and beverage companies using chocolate. IMARC says detailed company profiles are in the full report and names only San Miguel Brewery Inc. on the page, with no ratings. Competition centers on price, flavor, brand, and distribution.
Key organizations mentioned in the report's context include:
- San Miguel Brewery Inc. launched San Miguel Chocolate Lager in 2024. IMARC describes it as a leader in alcoholic beverages, so it is not a chocolate maker.
REGIONAL ANALYSIS
- Luzon: The largest market, with Metro Manila’s retail, gifting, and online demand and the Cordillera’s craft chocolate makers.
- Visayas: A growing market, with Cebu a hub for retail and some craft chocolate producers.
- Mindanao: The main cacao-growing region, with Davao a key source of beans. IMARC gives no regional values.
RECENT INDUSTRY DEVELOPMENTS
April 2026: Filipino chocolatiers are building a bean-to-bar premium segment, according to IFEX Connect. Citing Philippine Statistics Authority data, cacao output averaged 10,308 metric tons in 2020 to 2024, about 44% above the 2015 to 2019 average, and chocolate and cocoa-based product exports were US$9.88 million in 2024, up 32% from 2023. Makers such as Kokomo Cordillera Chocolate, Dulche Chocolate House, Theo and Philo, and SaBroso Tsokolate sell single-origin and tablea products in export markets.
2024: San Miguel Brewery launched San Miguel Chocolate Lager.
Key Aspects Required for the Philippines Chocolate Market
- Market Performance: USD 751.50 Million in 2025, with a projected trajectory to USD 1,198.71 Million by 2034.
- Market Outlook: A 4.78% CAGR through 2034 indicates steady growth.
- Growth Drivers: Premium and artisanal demand; e-commerce growth; and domestic cacao and government support.
- Competitive Landscape: Multinational and local confectioners and craft makers competing on price, flavor, and brand.
- Value Chain Analysis: From cacao farmers and ingredient suppliers, through chocolate makers and craft producers, to distributors, retailers, online sellers, and consumers.
- Industry Trends: Bean-to-bar and single-origin chocolate; online sales; local cacao sourcing; and flavor innovation.
- Strategic Recommendations: Develop premium and local-origin ranges; build online channels; secure cacao supply through farmer partnerships; and target gifting and seasonal demand.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=42631&flag=C
Report Format, Delivery, and Customization Details
- Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
- Report Delivery Mode: Online Delivery, Physical Delivery
- Report Delivery Time: report delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
- Report Confirmation Mode: Yes, via email
- Report Customization Mode: Yes, via Email / Call
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request For Sample Report: Yes