Modular Data Center Market Size, Share, Trends & Forecast 2026-2034
The global modular data center market size was valued at USD 36,796.6 Million in 2025. Looking forward, IMARC Group estimates the market to reach USD 108,484.0 Million by 2034, exhibiting a CAGR of 12.38% during 2026-2034.
 ashish kumar
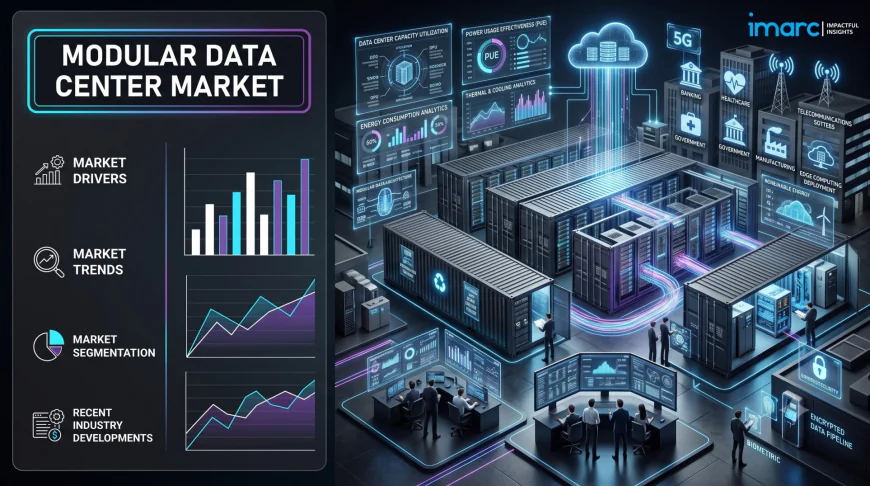
The global modular data center market size was valued at USD 36,796.6 Million in 2025. Looking forward, IMARC Group estimates the market to reach USD 108,484.0 Million by 2034, exhibiting a CAGR of 12.38% during 2026-2034. The global modular data center market has reached a valuation in the tens of billions of dollars, driven by accelerating demand for scalable, energy-efficient, and rapidly deployable IT infrastructure. Explosive growth in cloud computing, edge computing, 5G rollout, and AI-driven workloads is pushing enterprises and hyperscale operators toward prefabricated, modular building approaches that compress construction timelines from years to months.
How AI is Reshaping the Future of the Modular Data Center Market
-
AI-Optimized Power and Cooling Management: Machine learning systems embedded in modular units are dynamically adjusting cooling output and power distribution in real time based on workload intensity, reducing energy waste while keeping high-density GPU racks within safe operating thresholds.
-
Rapid Deployment of AI Training Infrastructure: Modular, factory-built pods pre-loaded with liquid cooling and high-density power capacity are letting AI companies stand up training and inference capacity in months instead of years, directly addressing the bottleneck created by traditional hyperscale construction timelines.
-
Predictive Maintenance for Modular Units: AI-driven monitoring platforms are tracking equipment health across geographically distributed modular deployments, flagging component wear before failures occur and reducing downtime across edge and remote sites.
-
Intelligent Site Selection and Capacity Planning: AI-powered analytics tools are helping operators model grid availability, power queue timelines, and climate conditions to identify optimal locations for modular deployments, addressing the multi-year grid connection delays now common in major markets.
-
Automated Workload Orchestration Across Distributed Nodes: AI systems are increasingly coordinating compute distribution across networks of modular edge data centers, allowing enterprises to run latency-sensitive applications closer to end users while balancing loads dynamically.
Grab a sample copy of this report: https://www.imarcgroup.com/modular-data-center-market/requestsample
Modular Data Center Market Trends and Drivers
The modular data center market is being propelled by a structural mismatch between AI-driven demand for compute capacity and the ability of traditional data center construction to keep pace. Conventional stick-built facilities typically require design-to-commissioning timelines stretching well beyond a year, and in power-constrained markets that timeline can extend further due to grid connection queues. Modular, prefabricated approaches are increasingly viewed by hyperscalers and enterprises as the practical alternative, compressing shell-to-operational timelines dramatically through off-site fabrication and standardized module design.
Grid capacity constraints are one of the most significant forces shaping deployment strategy. In several major markets, grid connection queues now stretch for years, and data center electricity demand is contributing meaningfully to overall power demand growth in some regions. This has pushed operators toward smaller, distributed modular footprints that can be sited more flexibly and connected to available power more quickly than massive single-site hyperscale campuses. Long-term supply agreements are becoming more common as a result, with operators locking in monthly delivery schedules for prefabricated modules over multi-year horizons to secure capacity against tightening supply chains for transformers, switchgear, and cooling equipment.
Sustainability and energy efficiency considerations continue to shape product design, with modern modular units increasingly built around advanced liquid cooling, heat reuse systems, and renewable energy integration. Government-backed digital infrastructure initiatives, expanding 5G networks, and rising enterprise adoption of edge computing are reinforcing demand across telecom, healthcare, BFSI, and government sectors, all of which require low-latency, rapidly deployable computing capacity closer to where data is generated.
Modular Data Center Industry Segmentation
The market has been segmented into the following categories:
Breakup by Component:
- Solutions (All-in-One Module, Individual Module)
- Services (Design and Consulting, Integration and Deployment, Support and Maintenance)
Solutions represent the dominant component segment, combining power, cooling, management software, and security systems into pre-engineered, expandable modules. This integrated approach minimizes deployment complexity and allows enterprises to bring high-density computing capacity online with far less on-site engineering work than traditional builds require.
Breakup by Data Center Size:
- Small and Medium-sized Data Centers
- Large Data Centers
Large data centers hold the largest share, serving hyperscale and enterprise cloud requirements with multiple modular units combined to deliver substantial computing power, storage, and networking capacity while retaining the deployment speed and redundancy advantages of modular construction.
Breakup by Application:
- Disaster Backup
- High Performance / Edge Computing
- Data Center Expansion
- Starter Data Centers
Data center expansion leads the application segment, reflecting how enterprises are using modular units to scale existing facilities in phased increments rather than committing to large, single-phase construction projects, allowing capacity to be added incrementally as workload demand grows.
Breakup by Industry Vertical:
- BFSI
- IT and Telecom
- Retail and Manufacturing
- Healthcare
- Energy
- Media and Entertainment
- Government and Defense
- Others
IT and telecom account for the largest vertical share, driven by the sector's need for highly scalable infrastructure to support cloud services, 5G rollout, and data-intensive applications, with modular deployment allowing operators to expand capacity quickly in response to rising connectivity and data traffic demands.
Breakup by Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
North America leads the market, supported by a dense concentration of hyperscale cloud providers, colocation operators, and enterprises pursuing high-performance computing capacity, alongside strong government support for green data center initiatives. Asia Pacific is expanding rapidly as China, India, Japan, and South Korea invest heavily in prefabricated infrastructure to support AI computing, 5G networks, and edge processing tied to national digitalization goals.
Competitive Landscape
The market features a mix of established technology conglomerates and specialized modular infrastructure providers, including:
- BASELAYER Technology LLC (Intermountain Electronics Inc.)
- Cannon Technologies Ltd
- Dell Technologies Inc.
- Eaton Corporation plc
- Hewlett Packard Enterprise Development LP
- Huawei Technologies Co. Ltd.
- International Business Machines Corporation
- Rittal GmbH & Co. KG
- Schneider Electric SE
- Vertiv Group Corp.
What Does This Market Cover?
- Complete market sizing across component, data center size, application, and industry vertical segments
- Analysis of growth drivers, restraints, and emerging opportunities
- Country-level insights across major modular data center markets
- Competitive profiling of leading modular infrastructure providers
- Assessment of AI, liquid cooling, and prefabrication trends reshaping deployment strategy
- Government policy and infrastructure investment analysis across key regions
Recent News and Developments
-
September 2026: Compu Dynamics Modular launched an expanded modular infrastructure portfolio for AI data centers, spanning configurations from a compact 750 kW all-in-one module up to a 5 to 6 MW turnkey AI factory, designed to deliver high-density power, cooling, and compute capacity through repeatable building blocks for AI training and inference workloads.
-
July 2026: Schneider Electric highlighted growing adoption of long-term supply agreements between operators and hyperscalers for prefabricated data center modules, with some contracts calling for delivery of multiple modules per month over multi-year periods to keep pace with sustained AI infrastructure demand.
-
February 2026: Industry analysis noted that modular, factory-built pods supporting high-density AI workloads and edge computing are increasingly positioned as a faster, more flexible alternative to hyperscale construction, as traditional facilities continue to face multi-year delays tied to permitting and grid connection constraints.
Note: If you require specific details, data, or insights that are not currently included in the scope of this content, we are happy to accommodate your request. Please let us know your exact needs.
Key Questions
- What is the current global modular data center market size?
- Which component segment holds the largest market share?
- What are the key drivers of modular data center market growth?
- Which region dominates the modular data center market and why?
- How is AI reshaping deployment speed and infrastructure design in this sector?
- Who are the leading companies in the modular data center market?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers create a lasting impact. The company provides a comprehensive suite of market entry and expansion services, including market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: [email protected]
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104