India Credit Card Market Growth Trends and Industry Outlook: Forecast Through 2034
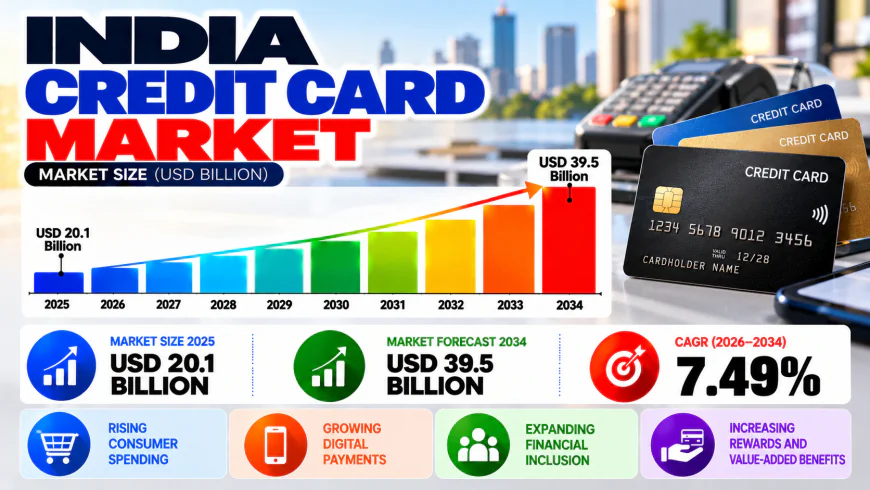
India credit card market size stood at USD 20.1 Billion in 2025, projected to reach USD 39.5 Billion by 2034 at 7.49% CAGR.
 chetan kalyan
How Is the India Credit Card Market Performing?
The market is expanding on the back of rapid digital payment adoption, fintech-driven co-branded cards and wider credit availability in Tier-II and Tier-III towns. Reward-based products, no-cost EMI plans and UPI-enabled credit cards are shaping how consumers choose and use cards.
Monthly credit card transactions stood at 496 million in September 2025, and the total reached 537 million on a monthly basis as of January 2026. Looking at Indian credit card industry statistics, the market was valued at USD 20.1 Billion in 2025 and is expected to reach USD 39.5 Billion by 2034, growing at a CAGR of 7.49% during 2026-2034.
The market growth is being driven by supportive digital payment policy, the integration of credit with UPI infrastructure through RuPay, surging e-commerce spending and growing first-time card ownership outside the largest cities. The industry in India is becoming a core part of everyday spending rather than a premium-only product.
Market Snapshot
- Market Size (2025): USD 20.1 Billion
- Forecast Value (2034): USD 39.5 Billion
- CAGR (2026-2034): 7.49%
- Leading Type: General Purpose (88.7% share)
- Leading Service Provider: Visa (43.5% share)
- Leading Credit Score Band: 701-850 (51.2% share)
- Leading Credit Limit: 51K-2L (46.4% share)
- Leading Card Type: Platinum (38.0% share)
- Leading Benefit: Cashback (60.0% share)
- Leading Region: West India (32.0% share)
What Growth Factors Are Driving the India Credit Card Market?
- Rapid Growth in Card Issuance and Digital Transactions
Outstanding credit cards in circulation have exceeded 100 million in recent years, and growth in cards in force signals rising transactions as urban consumers use cards for daily payments. This expansion is contributing to India credit card market growth as digital payment habits become more widespread.
- E-Commerce Growth and Digital Payment Integration
Online credit card transactions have been reaching record volumes. Integrating UPI with credit cards has widened usage, with UPI-based credit card transactions making up a significant share of overall transactions.
- Value-Added Offerings and Rewards Programs
Cashback, discounts, free EMIs and co-branded cards with retail and travel companies help issuers win new customers and encourage existing ones to spend more.
- Supportive Infrastructure and Tier-II/III Demand
The RBI Payments Vision 2025 aims to expand card acceptance infrastructure to 250 lakh touchpoints, reducing friction across merchant categories. Digital onboarding and fintech partnerships are lowering customer acquisition cost, enabling issuance in previously underserved demographics, while lifestyle spending on travel, premium retail and dining supports usage among urban millennials and Gen-Z professionals.
Evaluate Market Opportunity with the Business Sample Report
What Are the Latest Emerging Trends in the India Credit Card Market?
- UPI and Credit Integration
RuPay credit cards can be linked to PhonePe, Paytm and Google Pay, enabling use at millions of QR-based merchants that were previously reachable only with debit cards. By late 2025, UPI-based credit card transactions accounted for around 40% of total credit card transactions by volume, extending credit into semi-urban and rural merchant networks.
- Accelerating Demand for Co-Branded Cards
Co-brand cards tied to e-commerce, travel and lifestyle are gaining ground. In July 2025, SBI Card and PhonePe introduced the PhonePe SBI Card in PURPLE and SELECT BLACK variants, offering up to 10% value back on PhonePe transactions across RuPay and VISA.
- Geographic Expansion into Tier II and Tier III Cities
Growth is moving beyond the traditional metro markets. Delhi tops adoption at 12%, Maharashtra is home to 9.61 million credit card holders, and cities such as Surat, Nashik and Kanpur are also showing robust growth as digital onboarding opens credit to first-time holders. These developments are reshaping the credit card industry in India by expanding access beyond established urban markets.
What Opportunities Lie Ahead for the India Credit Card Market in the Coming Years?
India’s credit card market is poised to continue growing, driven by a young population, increasing income formalization and rising penetration of financial services in Tier-II and Tier-III cities. Ongoing investment in digital payment systems, co-branded products and supportive regulation on credit availability will keep the growth rate high through 2034.
Challenges remain and shape strategy. Credit cards are largely issued to people with a stable income and good credit history, leaving many informal-sector consumers outside the system. UPI apps compete for everyday payments, fraud concerns around online transactions persist, and high interest on outstanding dues and fear of personal debt can slow adoption. Issuers that address these concerns with secure, transparent and rewarding products are best placed to benefit.
Explore the Full Report with Charts, Table of Contents, and List of Figures
How Is the India Credit Card Market Segmented?
By Type
- General Purpose (leading at 88.7% share in 2025)
- Private Label
General purpose cards lead through mass-market adoption, digital onboarding, co-branded partnerships and broad merchant acceptance. They are issued by banks such as HDFC Bank, SBI Card, ICICI Bank and Axis Bank, and are usable across merchant categories, online and offline.
By Service Providing Company
- Visa (leading at 43.5% share in 2025)
- Mastercard
- RuPay
- Others
Visa’s lead reflects its trusted infrastructure, wide merchant acceptance and co-branded alliances. HDFC Bank, which held a 28.4% share of the spending market as of January 2026, relies on the Visa network for premium cards such as Infinia, Regalia and Millennia.
By Credit Score
- 701-850 (leading at 51.2% share in 2025)
- 300-500
- 501-700
- Above 851
Prime borrowers in the 701-850 band show low delinquency and high spending capacity, making them the most commercially attractive cardholders.
By Credit Limit
- 51K-2L (leading at 46.4% share in 2025)
- Up to 25K
- 25-50K
- 2L-5L
This mid-range tier fits the income profile of India’s salaried urban middle class. HDFC Bank led issuance with 25.79 million cards as of December 2025, followed by SBI Card at 21.81 million.
By Card Type
- Platinum (leading at 38.0% share in 2025)
- Base
- Signature
Platinum cards balance premium benefits with affordable fees, appealing to aspirational consumers seeking travel perks, lounge access and lifestyle rewards.
By Benefits
- Cashback (leading at 60.0% share in 2025)
- Voucher
Cashback is the most transparent and immediately tangible benefit in a price-sensitive market, with accelerated tiers on high-frequency categories like groceries, fuel, dining and utility bills.
By Region
- West India (leading at 32.0% share in 2025)
- South India
- North India
- East India
West India leads on Mumbai’s financial services density, Ahmedabad’s e-commerce adoption and Maharashtra’s mature organized retail. South India is driven by Bengaluru, Hyderabad and Chennai, North India by Delhi-NCR, and East India is the smallest region with the strongest catch-up potential from a low penetration base.
Competitive Landscape
A small cluster of private and public sector banks, including HDFC Bank, SBI Cards, ICICI Bank and Axis Bank, compete through products and digitally distributed co-branded cards. Mid-sized issuers such as RBL Bank and Kotak Mahindra are gaining pace with new launches and digital strategies. Other issuers include Citibank India, Bank of Baroda, Punjab National Bank and IndusInd Bank.
Request Customized Data Tailored to Your Interest
Investment & Growth Opportunities
- UPI-linked and RuPay credit card products that extend credit to QR-based merchants.
- Co-branded cards with fintech, e-commerce and travel partners that combine rewards with seamless digital payments.
- Digital-first issuance in Tier-II and Tier-III cities to reach first-time cardholders at lower acquisition cost.
- Premium and cashback-led propositions for the salaried urban middle class.
- Fintech and neo-banking partnerships that broaden the addressable demographic.
India Credit Card Market Recent Developments & News
- September 2025: ICICI Bank and Amazon Pay renewed their co-branded credit card partnership. The Amazon Pay ICICI Bank Credit Card, with over 5 million customers, saw its forex markup on international transactions cut from 3.5% to 1.99%, effective October 11, 2025.
- July 2025: SBI Card and PhonePe launched the PhonePe SBI Card in two variants on RuPay and VISA. The RuPay variants link directly to UPI across 40 million merchants.
- June 2025: PhonePe and HDFC Bank launched co-branded UPI-linked credit cards, Ultimo and UNO, on the RuPay network, with a fully digital application inside the PhonePe app.
Source: IMARC Group