Germany Automotive Market Size, Share, Trends and Report 2034
Germany automotive market worth 1,494.01 Thousand Units in 2025 is growing at a CAGR 3.36% to reach 2,011.53 Thousand Units by 2034.
 Yadwender Kumar
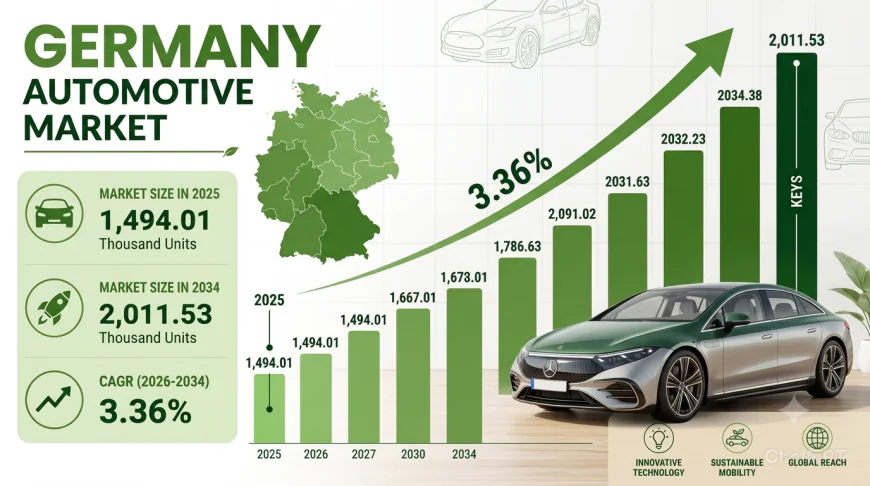
The Germany automotive market size reached 1,494.01 Thousand Units in 2025 and is projected to reach 2,011.53 Thousand Units by 2034, growing at a compound annual growth rate of 3.36% from 2026‑2034. The market is gaining momentum as the country continues its transition toward sustainable mobility while maintaining its position as Europe's largest vehicle market. Stringent EU emission regulations, expanding EV charging infrastructure, and robust investment in autonomous driving and connected vehicle technologies are reshaping the competitive landscape. Major German manufacturers are accelerating electrification strategies, launching affordable electric models, and enhancing digital integration across vehicle platforms, strengthening Germany's automotive market share.
The Germany automotive market is evolving rapidly as the country balances its deep-rooted automotive heritage with the accelerating transition toward electrified and connected mobility. Germany remains Europe's largest vehicle market, accounting for approximately a quarter of all new passenger car registrations in the European Union. The market recorded approximately 2.86 million new passenger car registrations in 2025, representing a modest recovery from prior years. The electrification trend is gaining significant traction, with battery-electric vehicle registrations surging by over 43% in 2025 to reach 545,000 units. Electric mobility is gaining momentum as automakers expand their portfolios with more accessible models designed for everyday use. This shift reflects a broader effort to make electric vehicles mainstream rather than niche offerings. At the same time, the automotive landscape is evolving through progress in autonomous driving systems, enhanced vehicle connectivity, and the steady rollout of charging infrastructure, collectively supporting a more integrated and future-ready transportation ecosystem.
The Germany automotive market is poised for sustained expansion, driven by the accelerating electrification of vehicle fleets, expanding charging infrastructure, and continued technological innovation. With a projected CAGR of 3.36% through 2034, the market presents significant opportunities for established manufacturers and new entrants focused on electric, connected, and autonomous mobility solutions.
GERMANY AUTOMOTIVE MARKET SUMMARY
-
The Germany automotive market encompasses a wide range of vehicles designed for personal mobility, commercial transport, and industrial applications. The ecosystem includes global and domestic OEMs (Volkswagen, BMW, Mercedes-Benz, Audi, Porsche, and others), tier-1 suppliers, technology providers, charging infrastructure operators, and end‑use consumers. Major segments identified in the market include propulsion type (electric and internal combustion), vehicle type (passenger vehicles and commercial vehicles), and region (Western Germany, Southern Germany, Eastern Germany, and Northern Germany). The internal combustion segment is the dominant propulsion category, accounting for approximately 81% of total market share, while passenger vehicles lead the vehicle type segment with approximately 76% of total market share.
PORTER'S FIVE FORCES ANALYSIS – GERMANY AUTOMOTIVE MARKET
The competitive dynamics of the Germany automotive market can be analyzed using Porter's Five Forces framework.
Porter's Five Forces Analysis – Germany Automotive Market
-
Competitive Rivalry: High, with intense competition between established German OEMs and international EV manufacturers. Rivalry is driven by electrification investments, pricing pressure, model proliferation, and technological differentiation. Business implication: Manufacturers must differentiate through innovation, cost optimization, and brand loyalty to sustain market share.
-
Supplier Power: Moderate. Suppliers of batteries, semiconductors, and specialized components have increasing negotiating power due to supply chain constraints and rising demand for EV-specific inputs. Business implication: OEMs must develop strategic partnerships, vertical integration, and multi-sourcing strategies to mitigate supply risks.
-
Buyer Power: Increasing. Consumers and fleet operators have growing bargaining power due to a wider range of vehicle choices, transparent pricing, and shifting preferences toward electric and connected vehicles. Business implication: Manufacturers must offer compelling value propositions, competitive pricing, and enhanced digital experiences to attract and retain customers.
-
Threat of Substitutes: Moderate. Alternative mobility solutions (public transport, ride-sharing, micro-mobility), hydrogen fuel cell vehicles, and used vehicle imports pose substitution threats. Business implication: Automotive players must articulate clear advantages in performance, sustainability, and total cost of ownership relative to alternatives.
-
Threat of New Entrants: Moderate to High. High barriers exist for traditional vehicle manufacturing (capital intensity, regulatory compliance, brand establishment), but lower barriers for EV startups and technology-focused entrants. Germany's growing EV market attracts new domestic and international entrants. Business implication: Established players should build defensible positions through technology leadership, charging ecosystem partnerships, and strong customer relationships.
Competitive Rivalry – Moderate to High (Healthy)
-
Multi-tier competition spans domestic leaders (Volkswagen Group, BMW, Mercedes-Benz), premium specialists (Audi, Porsche), and international challengers (Tesla, Chinese EV manufacturers such as BYD, NIO, and MG) -- driving differentiation through electrification, autonomous driving capabilities, digital integration, and sustainability credentials rather than destructive price competition.
-
Volkswagen's comprehensive electric mobility strategy unveiled at IAA Mobility 2025 (including ID. Polo, ID. Polo GTI, ID. Cross concept, and ID. EVERY1 concept), BMW's first Neue Klasse production model (the all-new BMW iX3 electric SUV), and Wayve's establishment of an on-road testing hub in Baden-Württemberg reflect active strategic repositioning that is strengthening the overall market ecosystem.
Request for Sample Report: https://www.imarcgroup.com/germany-automotive-market/requestsample
MARKET GROWTH DRIVERS:
Several key factors are propelling the expansion of the Germany automotive market. Stringent EU emission regulations and government policy support serve as a powerful demand driver for electric and low-emission vehicles. The European Union's progressively tightening CO2 emission standards are compelling manufacturers to accelerate their transition toward cleaner propulsion technologies. Germany's federal government has complemented these regulations with targeted industrial policies, including the National Innovation Programme for Hydrogen and Fuel Cell Technology, under which the Federal Ministry for Digital and Transport invested EUR 259 million in research and development and EUR 285 million for market activation. Additionally, the rapid expansion of electric vehicle charging infrastructure is supporting automotive consumption, with Germany's charging network reaching approximately 184,000 public charging points by mid‑2025, a year‑on‑year increase of nearly 20,000 installations, and motorway charging coverage standing at 67%, significantly exceeding the EU target of 15%.
MARKET GROWTH DRIVERS:
The Germany automotive market is also benefiting from accelerating technological innovation and new model launches by German OEMs. There is an accelerating shift toward electric and hybrid vehicle platforms, as German manufacturers strategically reposition their product portfolios to meet evolving regulatory requirements and shifting consumer preferences toward sustainable mobility solutions. Electric vehicles offer superior efficiency and lower emissions, while the Germany electric vehicle market size reached USD 41.9 Billion in 2025 and is expected to reach USD 259.1 Billion by 2034, exhibiting a growth rate (CAGR) of 22.44% during 2026‑2034. Advancement of autonomous driving and AI‑powered mobility solutions, including the federal government's comprehensive legal framework for autonomous driving and the Strategy for Automated and Connected Driving, is creating a new segment, with companies like Wayve establishing on-road testing hubs and deploying test vehicles across Germany's diverse driving environments. Furthermore, the expansion of connected vehicle technologies and digital integration is enhancing safety, convenience, and the overall driving experience, with automakers integrating sophisticated infotainment systems, telematics, and vehicle‑to‑everything communication capabilities into new models.
GERMANY AUTOMOTIVE MARKET SEGMENTATION
Segmentation analysis provides a detailed view of the Germany automotive market by category:
-
Propulsion Type Insights: Electric, Internal Combustion.
-
Vehicle Type Insights: Commercial Vehicles, Passenger Vehicles.
-
Regional Insights: Western Germany, Southern Germany, Eastern Germany, Northern Germany.
COMPETITIVE LANDSCAPE
The Germany automotive market features a highly competitive landscape, with multi‑tier competition spanning global leaders and strong domestic players. Key companies operating in the market include:
-
Volkswagen Group
-
BMW AG
-
Mercedes-Benz Group AG
-
Audi AG
-
Porsche AG
-
Tesla, Inc.
-
BYD Company Ltd.
-
NIO Inc.
Strategic developments are shaping the competitive arena, notably Volkswagen's comprehensive electric mobility strategy unveiled at IAA Mobility 2025 (including four new electric models in the small car and compact segment), and BMW's unveiling of its first Neue Klasse production model, the all‑new BMW iX3 electric SUV, at the IAA Mobility exhibition in Munich.
REGIONAL ANALYSIS:
Regional dynamics within the Germany automotive market are shaped by varying levels of industrial concentration, infrastructure activity, and manufacturing presence. Western Germany represents a significant automotive market, benefiting from high population density, strong economic activity, and the presence of major metropolitan centers such as Cologne and Düsseldorf that drive substantial vehicle demand across both passenger and commercial segments. Southern Germany is a major automotive hub, home to the headquarters and manufacturing facilities of premium brands including BMW in Munich and Mercedes‑Benz in Stuttgart, alongside a dense network of automotive suppliers and technology companies concentrated in Bavaria and Baden‑Württemberg. Eastern Germany has emerged as an important region for automotive innovation, with Tesla's Gigafactory in Grünheide near Berlin serving as a major EV manufacturing hub, contributing to the region's growing role in electric vehicle production and advanced manufacturing. Northern Germany benefits from its strategic location for logistics and export, with major ports in Hamburg facilitating vehicle exports, alongside Volkswagen's extensive manufacturing operations in Lower Saxony that anchor the region's automotive ecosystem.
RECENT INDUSTRY DEVELOPMENTS
September 2025: Volkswagen presented its comprehensive electric mobility strategy at the IAA Mobility show in Munich, unveiling four new electric models in the small car and compact segment, including the ID. Polo, ID. Polo GTI, ID. Cross concept, and ID. EVERY1 concept.
September 2025: A major milestone in BMW's electrification journey was marked with the unveiling of its first Neue Klasse production model. The all‑new BMW iX3 electric SUV made its official debut in Munich during the IAA Mobility exhibition. The launch was particularly significant, coming nearly 60 years after the original Neue Klasse concept helped the company overcome financial challenges in the 1960s.
March 2025: UK‑based AI autonomous driving company Wayve established an on‑road testing and development hub in Baden‑Württemberg following its USD 1.05 billion Series C funding round, deploying a fleet of test vehicles across Germany's diverse driving environments, including Autobahns, urban areas, and winter road conditions.
April 2024: Germany and China signed a joint declaration to cooperate on autonomous and connected driving, aiming to develop shared standards and rules for data management, reflecting the growing importance of cross‑border collaboration in advancing connected mobility solutions.
KEY ASPECTS REQUIRED FOR THE GERMANY AUTOMOTIVE MARKET
-
Market Performance: 1,494.01 Thousand Units in 2025, with a projected trajectory to 2,011.53 Thousand Units by 2034.
-
Market Outlook: A 3.36% CAGR through 2034 indicates robust growth across electric and internal combustion propulsion segments, passenger and commercial vehicle categories, and all regions.
-
Growth Drivers: Stringent EU emission regulations compelling electrification; rapid expansion of EV charging infrastructure (approximately 184,000 public charging points by mid‑2025); technological innovation and new model launches by German OEMs; growing consumer preference for connected and autonomous vehicles; supportive government policies promoting sustainable transportation; EUR 259 million invested in hydrogen and fuel cell R&D and EUR 285 million for market activation.
-
Competitive Landscape: A highly competitive environment characterized by well‑established domestic manufacturers alongside an increasing number of international entrants, with moderate concentration at the manufacturer level. Key players include Volkswagen Group, BMW AG, Mercedes‑Benz Group AG, Audi AG, Porsche AG, Tesla, Inc., BYD Company Ltd., and NIO Inc.
-
Value Chain Analysis: From raw material sourcing and component manufacturing through vehicle assembly, distribution, sales, and after‑sales services to end‑use consumers.
-
Industry Trends: Accelerating electric vehicle adoption and market penetration; advancement of autonomous driving and AI‑powered mobility solutions; expansion of connected vehicle technologies and digital integration; workforce restructuring and industry transition challenges; intensifying competition from international EV manufacturers.
-
Strategic Recommendations: Focus on electrification and battery technology innovation, autonomous driving and connected vehicle capabilities, charging infrastructure partnerships, cost optimization and production efficiency, workforce retraining and transition management; develop differentiated capabilities in software‑defined vehicles and digital services; build strong relationships with technology partners and suppliers.
Note: If you need any specific information that is not covered currently within the scope of the report, we will provide the same as a part of customization.
Request Customization: https://www.imarcgroup.com/request?type=report&id=23723&flag=E
Write this before about us –
-
Report Format, Delivery, and Customization Details
-
Report Format Mode: PPT, PDF, and Excel
-
Report Delivery Mode: Online Delivery, Physical Delivery
-
Report Delivery Time: Report Delivered Over Email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
-
Report Confirmation Mode: Yes via Email
-
Report Customization Mode: Yes via Email / Call
-
Report Table of Content: Yes
-
Report List of Figures: Yes
-
Report Methodology Mode: Yes
-
Request For Sample Report: Yes