Defense Equipment Market Opportunities in Unmanned Vehicles and Advanced Military Technologies
7% in 2025, reflecting the importance of military aviation, propulsion systems, combat operations, air defense, and strategic mobility.
 Eknath Girhepunje
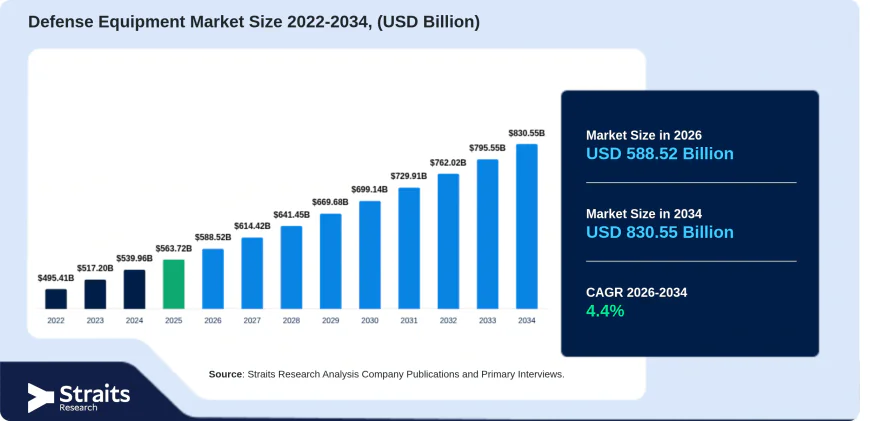
The global defense equipment market plays a critical role in national security, military readiness, and the modernization of armed forces. Defense equipment includes specialized machinery, military vehicles, weapons, aircraft, naval platforms, communication systems, and technologies designed to protect personnel and support military operations. Investment in advanced defense platforms, soldier protection, autonomous systems, and domestic manufacturing is shaping industry priorities as governments seek reliable equipment and stronger defense capabilities.
The global defense equipment market size was valued at USD 563.72 billion in 2025 and is projected to grow from USD 588.52 billion in 2026 to USD 830.55 billion by 2034, registering a CAGR of 4.4% during the forecast period from 2026 to 2034. North America dominated the defense equipment market with a share of 38.4% in 2025, supported by substantial defense procurement, established aerospace and defense manufacturers, and investment in military modernization.
For detailed market insights, growth forecasts, and competitive analysis, visit: https://straitsresearch.com/report/defence-equipment-market
Market Drivers
Military Equipment Modernization and Replacement Programs
The need to replace aging military platforms supports demand for modern defense equipment that improves operational readiness, reliability, and battlefield performance. Older vehicles and weapon systems may require frequent maintenance and lack capabilities suited to current military requirements. Modernization programs create procurement opportunities for manufacturers of armored vehicles, aircraft, weapons, communication systems, and associated components. For instance, U.S. Army procurement plans include armored multipurpose vehicles and continued development of the XM30 combat vehicle, which is intended to replace the Bradley infantry fighting vehicle.
Demand for Soldier Protection Equipment
Protecting military personnel from ballistic threats, fragments, and other battlefield hazards remains an important defense procurement priority. Body armor, protective helmets, ballistic eyewear, and specialized clothing help reduce injury risks while supporting mobility and operational effectiveness. Defense organizations require equipment that balances protection, durability, comfort, and suitability for different mission environments. Large-scale procurement requirements support manufacturers of protective equipment and encourage the development of lighter materials and improved protective designs.
Investment in Advanced Defense Technologies
Investment in advanced defense technologies supports demand for modern aircraft, unmanned vehicles, communication systems, sensors, and integrated military platforms. Defense organizations are also examining autonomous ground systems that can support logistics, resupply, communications, and casualty evacuation in dangerous areas. These systems can help reduce the logistical workload on personnel and limit exposure to hazardous environments. Continued investment in research and development encourages defense manufacturers to improve equipment performance, system integration, and operational reliability.
Market Challenges
Dependence on Specialized Components and Supply Chains
The defense equipment market depends on specialized semiconductors, sensors, electronic components, advanced materials, and precision-manufactured parts. Limited supplier availability, long manufacturing lead times, and disruptions in component production can delay equipment deliveries and increase procurement costs. These challenges are particularly important for advanced platforms that require multiple specialized technologies to function together. Manufacturers and defense agencies must manage supplier relationships, component availability, and production planning to maintain reliable delivery schedules.
Geopolitical Restrictions and Export Controls
Export controls, sanctions, and restrictions on technology transfers can complicate defense equipment procurement and international collaboration. Manufacturers may face licensing requirements or limits on supplying certain technologies and components to overseas customers. Changes in trade policies can also affect sourcing arrangements, manufacturing partnerships, and access to international markets. These restrictions can increase compliance costs, delay projects, and require companies to develop alternative supply arrangements or domestic production capabilities.
High Development and Procurement Costs
Advanced defense equipment requires substantial investment in research, engineering, testing, manufacturing, and maintenance. Complex platforms such as military aircraft, submarines, missile systems, and integrated defense technologies may require lengthy development cycles before entering service. Governments must balance procurement priorities with budget limitations and other national requirements. Cost overruns, technical changes, and extended testing can affect project timelines and create uncertainty for manufacturers and defense procurement agencies.
Market Segmentation
By Product Type
Based on product type, the defense equipment market includes high mobility vehicles, small arms and rifles, heavy arms and missiles, unmanned vehicles, communication systems, naval fleets, aircraft and aero engines, submarines, and training and simulation systems. The aircraft and aero engines segment dominated the market with a share of 19.7% in 2025, reflecting the importance of military aviation, propulsion systems, combat operations, air defense, and strategic mobility. The unmanned vehicles segment is projected to grow at a CAGR of 8.2% during the forecast period from 2026 to 2034, supported by the use of unmanned platforms for surveillance, reconnaissance, and mission support.
By End Usage
The market is segmented by end usage into air force, navy, army, and research and development initiatives. The air force segment accounted for 34.7% of the market in 2025, supported by requirements for aircraft, air defense capabilities, advanced weapons, and military aviation systems. The research and development initiatives segment is expected to grow at a CAGR of 7.4% during the forecast period from 2026 to 2034, fueled by investment in advanced defense technologies, next-generation equipment, and improvements in military capabilities. Each end-use category requires equipment tailored to its operational responsibilities and technical requirements.
Regional Insights
North America
North America dominated the defense equipment market with a share of 38.4% in 2025. The region benefits from established defense manufacturers, advanced aerospace capabilities, substantial procurement programs, and investment in military modernization. The U.S. Department of Defense's fiscal 2026 budget request includes USD 11.48 billion for Columbia-class submarines and USD 10.293 billion for the B-21 bomber program. In Canada, the defense industrial strategy identifies approximately CAD 180 billion in defense procurement opportunities and CAD 290 billion in defense-related capital investment opportunities over the next decade. These initiatives could support equipment manufacturing, technology development, and domestic supply-chain capabilities.
Europe
The European defense equipment market is projected to grow at a CAGR of 5.2% during the forecast period from 2026 to 2034. Defense modernization, equipment procurement, and domestic manufacturing initiatives support regional market activity. The United Kingdom's defense investment plan is backed by GBP 298 billion in investment over four years, with priorities including military readiness, equipment modernization, and domestic industry. Germany is reforming its Bundeswehr equipment procurement authority to simplify purchasing procedures, accelerate acquisitions, and improve collaboration with industry. These measures could support equipment manufacturers and improve the responsiveness of defense supply chains.
Asia Pacific
Asia Pacific is expected to be the fastest-growing regional market, registering a CAGR of 7.1% during the forecast period from 2026 to 2034. Defense modernization, domestic production initiatives, and investment in advanced military technologies contribute to regional demand. Japan's fiscal 2026 defense budget includes approximately JPY 907.5 billion for ammunition-related requirements and provisions for acquiring ammunition and missiles, alongside initiatives supporting equipment maintenance and domestic missile production. China's 2026 defense expenditure is budgeted at approximately CNY 1.94 trillion, with priorities including equipment modernization and defense science and technology. India's fiscal 2026–27 Union Budget allocates approximately USD 90 billion to the Ministry of Defence, including around USD 21.2 billion for capital acquisition and approximately USD 15.9 billion for procurement from domestic defense industries.
Key Players Analysis
The defense equipment market includes multinational defense contractors, aerospace manufacturers, government-owned defense enterprises, and specialized military technology providers. Competition is shaped by technological innovation, research and development capabilities, product quality, manufacturing capacity, system integration, government contracts, and supply-chain networks. The major players in this market include:
- Lockheed Martin Corporation
- BAE Systems plc
- Northrop Grumman Corporation
- Raytheon Company
- General Dynamics Corporation
Established companies compete through advanced technology portfolios, large-scale manufacturing, long-term government relationships, and the ability to deliver integrated defense platforms. Regional and specialized manufacturers focus on indigenous production, customized equipment, cost-effective solutions, and technologies tailored to specific military requirements.
Conclusion
The defense equipment market is projected to reach USD 830.55 billion by 2034, supported by military modernization, soldier protection requirements, and investment in advanced defense technologies. North America held the largest regional share in 2025, while Asia Pacific is expected to record the fastest growth during the forecast period from 2026 to 2034. However, supply-chain dependence, geopolitical restrictions, and high procurement costs remain important challenges. Domestic manufacturing, research and development, and more resilient supply networks will continue to influence the industry's development.
About Us
Straits Research is a market research and intelligence company that provides market sizing, revenue forecasts, competitive assessments, and strategic insights across multiple industries. Its research helps businesses, investors, and decision-makers understand market developments, evaluate competitive positioning, and make informed strategic decisions.
Contact Us
For further information about the defense equipment market, customized research, or detailed market forecasts, contact Straits Research.
Website: https://straitsresearch.com/
Email: [email protected]
India: +91 8087085354
U.S.: +1 646 905 0080
U.K.: +44 203 695 0070