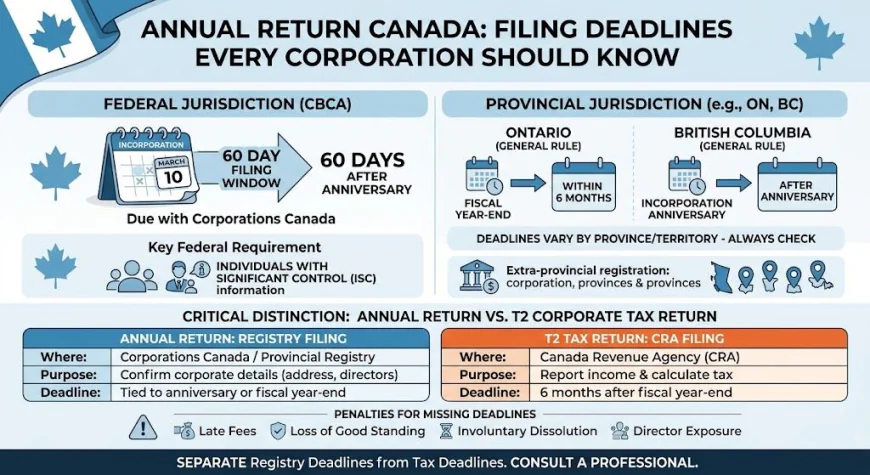
Annual Return Canada: Filing Deadlines Every Corporation Should Know
Others tie it to the fiscal year or to tax filings. Always confirm the current requirement with the relevant registry, because rules and portals are updated periodically.
 james smith-9
Every incorporated business in Canada has ongoing compliance duties, and the annual return Canada requirement is one of the easiest to overlook. A missed deadline can bring late fees, a loss of good standing, and in serious cases, dissolution of the corporation. This guide explains what a corporate annual return Canada filing is, when it is due, and how to keep your annual return filing Canada on schedule.
What Is an Annual Return in Canada?
An annual return is a yearly update filed with the government body that governs your corporation. It confirms that your corporate records are accurate and that the business is still active. Typical details include the registered office address, directors and officers, and the corporation's name and status.
A corporation annual return is not a financial statement, and it is not a tax filing. It is a corporate registry update. Many business owners confuse it with the T2 corporate income tax return filed with the Canada Revenue Agency (CRA), but the two are separate obligations with separate deadlines, authorities, and penalties.
Federal vs. Provincial: Where Do You File?
The place you file depends on where your corporation was incorporated.
- Federally incorporated corporations (under the Canada Business Corporations Act, or CBCA) file with Corporations Canada.
- Provincially or territorially incorporated corporations file with the relevant provincial or territorial registry, such as the Ontario Business Registry or BC Registries.
Knowing your jurisdiction of incorporation comes first. Your articles of incorporation or certificate of incorporation will tell you.
Federal Annual Return Deadline (CBCA)
For federally incorporated corporations, the rule is simple. The annual return is due within 60 days after the anniversary of the corporation's incorporation date. If the corporation was formed through an amalgamation or continuance, the anniversary is based on that date instead.
For example, if your corporation was incorporated on March 10, the anniversary falls on March 10 each year. The annual return filing Canada window then runs for the 60 days that follow.
Filing Fees and Method
Corporations Canada accepts annual returns online, and online filing is generally faster and cheaper than paper. Fees can change, so check the current fee on the Corporations Canada website before you file.
Individuals With Significant Control
Federal corporations must also keep a register of individuals with significant control (ISC), meaning people who hold or control a meaningful share of the corporation. This information is reported in the annual return, so it should be reviewed before you file.
Provincial Annual Return Deadlines
Provincial deadlines vary considerably, so a corporation registered in one province cannot assume its neighbour's rules apply. These are two well-known examples.
Ontario
Ontario corporations file their annual return through the Ontario Business Registry. The filing is generally due within six months after the corporation's fiscal year-end. Ontario ties the return to the fiscal year rather than the incorporation anniversary, which sets it apart from the federal model.
British Columbia
In British Columbia, a company must file an annual report with BC Registries. The report is generally due after the anniversary of the company's incorporation or recognition, so the calendar works more like the federal one.
Other Provinces and Territories
Alberta, Quebec, Manitoba, Nova Scotia, and the other jurisdictions each have their own timing, forms, and fees. Some tie the filing to the anniversary date. Others tie it to the fiscal year or to tax filings. Always confirm the current requirement with the relevant registry, because rules and portals are updated periodically.
Annual Return vs. T2 Corporate Tax Return
The two obligations are often mixed up, and mixing them up is a common source of missed deadlines.
| Annual Return | T2 Corporate Tax Return | |
|---|---|---|
| Filed with | Corporations Canada or a provincial registry | Canada Revenue Agency |
| Purpose | Confirm corporate details | Report income and calculate tax |
| Typical deadline | Tied to anniversary or fiscal year-end, depending on jurisdiction | Six months after fiscal year-end |
The T2 return is generally due six months after the corporation's fiscal year-end. Any tax owing is usually due sooner, generally two months after year-end, or three months for certain Canadian-controlled private corporations. Filing the T2 does not satisfy the registry's annual return requirement, and the reverse is also true.
What Happens If You Miss the Deadline?
Consequences depend on the jurisdiction, but they can include:
- Late filing fees or penalties.
- Loss of "active" or "good standing" status.
- Difficulty opening bank accounts, securing financing, or completing a sale of the business.
- Involuntary dissolution by the registry after prolonged non-compliance.
Directors can also face compliance exposure when required filings are neglected. Reinstating a dissolved corporation takes time and money, and it can leave gaps in your legal and contractual history. Filing on time is far cheaper.
Practical Tips to Stay Compliant
A few simple habits prevent most missed deadlines:
- Record your incorporation date and jurisdiction in a shared calendar with reminders at least 30 days before the due date.
- Keep corporate records current. Update director, officer, and address changes when they happen instead of waiting for the annual return.
- Review ISC and shareholder information before each filing, particularly for federal corporations.
- Separate your compliance calendar into registry filings and CRA tax filings so neither is mistaken for the other.
- Assign ownership. Decide who is responsible, whether an officer, an accountant, or a corporate service provider, and confirm they have the access they need.
- Ask a professional when your situation is unusual. Amalgamations, continuances, and extra-provincial registrations all complicate the timeline.
Conclusion
Timely annual return Canada filing keeps your corporation in good standing, protects the directors, and avoids expensive clean-up later. Start by identifying where your corporation is incorporated, then mark the correct deadline, whether that is 60 days after the anniversary for federal corporations or the fiscal-year-based or anniversary-based rule in your province. Treat the annual return and the T2 tax return as two separate tasks, and check current rules with the relevant registry each year.
Frequently Asked Questions
Q1: When is the annual return due for a federal corporation in Canada?
A federally incorporated corporation must file its annual return with Corporations Canada within 60 days after the anniversary of its incorporation date. For amalgamated or continued corporations, the anniversary is based on the amalgamation or continuance date.
Q2: Is an annual return the same as filing corporate taxes?
No. The annual return is a registry filing that updates corporate information with Corporations Canada or a provincial registry. Corporate taxes are reported to the CRA on the T2 return, which has its own deadline and penalties. Filing one does not satisfy the other.
Q3: What happens if a corporation does not file its annual return?
The corporation may face late fees and lose good standing. If non-compliance continues, the registry can dissolve it. A dissolved corporation must go through a reinstatement or revival process, which costs time and money.