United States Data Center Construction Market Size is Expected to Reach USD 25,025.7 Million by 2034 | CAGR 5.15%
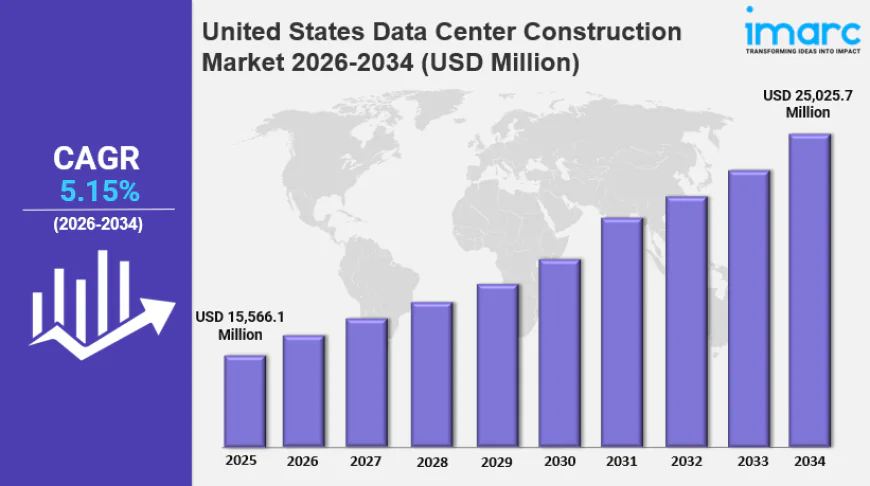
The United States data center construction market size reached USD 15,566.1 Million in 2025 and is projected to reach USD 25,025.7 Million by 2034, expanding at a CAGR of 5.15% during 2026-2034.
 marketinsights
IMARC Group has recently released a new research study titled "United States Data Center Construction Market Size, Share, Trends, and Forecast by Construction Type, Data Center Type, Tier Standards, Vertical, and Region, 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
United States Data Center Construction Market Size & Share 2026-2034
The United States data center construction market size reached USD 15,566.1 Million in 2025 and is projected to reach USD 25,025.7 Million by 2034, expanding at a CAGR of 5.15% during 2026-2034. In 2026, the market continues to gain momentum, propelled by demand from artificial intelligence (AI), cloud, and hyperscale computing, and by rapid capacity expansion in key regions such as Northern Virginia, Texas, and the Southeast.
Growth in 2026 is further reinforced by the construction of modern Tier III and Tier IV facilities, advanced cooling systems, and modular designs, along with the rising adoption of edge computing and supportive policies and tax incentives. These developments are expected to strengthen United States data center construction market demand throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 15,566.1 Million
- Projected Market Size (2034): USD 25,025.7 Million
- Growth Rate: CAGR of 5.15% (2026-2034)
Explore Opportunities in the United States Data Center Construction Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-data-center-construction-market/requestsample
Key Growth Drivers and Trends in the United States Data Center Construction Market
Growth in the United States data center construction market is being driven by surging demand for digital infrastructure. Rapid growth in data generation, fueled by machine learning, AI, the Internet of Things (IoT), and 5G, is pushing hyperscale cloud providers and enterprises to expand their data center footprints, with Google Cloud, Microsoft Azure, and Amazon Web Services building next-generation facilities with high power density and efficient cooling. In January 2025, OpenAI, SoftBank, and Oracle launched the Stargate joint venture to invest USD 100 Billion in AI infrastructure, with potential expansion to USD 500 Billion, and with the first site already underway in Abilene, Texas.
One of the leading United States data center construction market trends is the emergence of AI, IoT, and other technological innovations that require real-time processing, low latency, and robust computing infrastructure. At the same time, data consumption and cloud dependency keep rising. According to CTIA's 2024 Annual Wireless Industry Survey, U.S. wireless networks carried a record 100.1 trillion megabytes of data in 2023, an 89% increase since 2021, and organizations migrating workloads to the cloud are intensifying demand for secure, high-capacity facilities.
Another key factor supporting United States data center construction market growth is the push for sustainability, edge computing, and large-scale investment. Operators are adopting renewable energy and optimized cooling, and favorable policies, tax incentives, and renewable energy mandates are encouraging energy-efficient construction. Remote work adds to demand, with roughly 14% of the U.S. workforce, or about 22 million people, working fully remotely. Recent moves include Related Companies launching Related Digital in March 2025, a division focused on data center development across the United States and Canada, and Microsoft beginning to build its first data centers with cross-laminated timber in October 2024 to cut carbon emissions by up to 65% versus concrete.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20217&flag=C
United States Data Center Construction Industry Segmentation Insights
Breakup by Construction Type:
- Electrical Construction: Expected to hold a dominant share given the power-intensive nature of modern facilities, covering switchgear, generators, UPS systems, and power distribution units (PDUs) that deliver resilient, redundant power as AI, IoT, and cloud workloads scale.
- Mechanical Construction: A critical, high-value segment centered on thermal management, including advanced HVAC, liquid cooling, immersion cooling, free-air cooling, and airflow management for high-density servers, supported by the push for energy-efficient green designs.
Breakup by Data Center Type:
- Mid-Size Data Centers: Gaining prominence for their balance of scalability, cost-efficiency, and deployment speed, serving regional enterprises, content delivery networks, and service providers, and supporting edge and hybrid cloud strategies in secondary U.S. markets.
- Enterprise Data Centers: Maintained by large organizations for security, compliance, and data control, particularly in government, healthcare, and finance, and often integrated with public clouds in hybrid environments.
- Large Data Centers: Dominant as cloud providers, hyperscalers, and tech giants expand aggressively to support AI workloads, streaming, gaming, and e-commerce, typically in locations offering tax incentives, renewable energy access, and strong connectivity.
Breakup by Tier Standards:
- Tier I and II: Cost-effective facilities for small to mid-sized enterprises with moderate uptime needs, increasingly developed in secondary markets and for edge computing.
- Tier III: The preferred standard for enterprises and colocation providers, offering concurrently maintainable infrastructure with 99.982% uptime and widely used in financial services, healthcare, and cloud services.
- Tier IV: Designed for mission-critical operations with the highest fault tolerance and 99.995% uptime, with construction rising in defense, government, and hyperscale cloud computing.
Breakup by Vertical:
- Public Sector: Federal, state, and local bodies are investing in secure, resilient infrastructure for digital governance, public services, and national security, with data sovereignty and disaster recovery needs driving demand for Tier III and Tier IV facilities.
- Oil and Energy: Digital transformation, real-time analytics, and AI-driven decision-making require high-performance and edge data centers, particularly in energy-rich regions such as Texas and Louisiana.
- Media and Entertainment: Video streaming, gaming, virtual reality, and OTT platforms require high bandwidth and low latency, prompting capacity expansion near urban hubs.
- IT and Telecommunication: Relies on data center capacity to support network services, cloud platforms, and growing data traffic.
- Banking, Financial Services and Insurance (BFSI): Requires secure, highly available infrastructure to meet compliance, transaction processing, and disaster recovery needs.
- Healthcare: Needs reliable, compliant infrastructure for patient data, medical records, and digital health services.
- Retail: Depends on data centers for e-commerce, inventory systems, and customer analytics.
- Others: Covers additional verticals that rely on data center infrastructure.
Breakup by Region:
- Northeast: Strategically located near major financial institutions, dense urban populations, and government agencies, with technology hubs such as New York City and Boston, strict data compliance rules, and demand for low-latency networks and disaster recovery sites.
- Midwest: Becoming a central hub thanks to lower land and utility costs, a stable climate, and low natural disaster risk, with states such as Ohio, Illinois, and Iowa offering tax incentives and renewable energy access.
- South: A leader in data center construction, driven by business-friendly regulations, ample land, competitive energy pricing, and generous tax breaks in states such as Texas, Georgia, and Virginia.
- West: A major hub, particularly California and Washington, with a concentration of tech giants and innovation clusters, leadership in green data center initiatives and edge computing, and strong demand from entertainment, e-commerce, and SaaS sectors despite high real estate and energy costs.
Key Challenges and Growth Opportunities in the United States Data Center Construction Market
The United States data center construction market is capital-intensive and highly competitive, with new entrants intensifying competition as demand for hyperscale and edge facilities rises. Regions with high real estate and energy costs, such as parts of the West, also face cost pressures, and builders must keep pace with fast-changing requirements for power density and cooling.
Despite this, the market offers considerable growth opportunities driven by AI, cloud, and hyperscale demand, expanding edge computing, and demand from healthcare, banking, and e-commerce for reliable IT infrastructure. Modular and scalable designs, energy-efficient and renewable-powered facilities, and growth in secondary markets are expected to create substantial opportunities for long-term growth in the United States data center construction market.
Competitive Landscape
The United States data center construction market is competitive and fragmented, shaped by global technology companies, real estate developers, engineering firms, and specialized contractors. Key players such as Turner Construction, DPR Construction, Jacobs Engineering, and Holder Construction lead large-scale projects, often partnering with major cloud providers such as Microsoft Azure, Google Cloud, and Amazon Web Services. Rising demand for hyperscale and edge facilities has attracted new entrants, and firms are differentiating through modular builds, energy-efficient designs, and fast-track construction methods, supported by strategic alliances, geographic expansion, and sustainability initiatives.
Recent developments include Amazon's June 2025 announcement of a USD 10 Billion data center expansion in North Carolina as part of its USD 100 Billion AI-focused capital plan for 2025, EDGNEX Data Centers by DAMAC's January 2025 announcement of a USD 20 Billion U.S. expansion targeting 2,000MW of capacity, and Meta's December 2024 announcement of a USD 10 Billion AI-optimized data center in northeast Louisiana. In January 2025, Engine No. 1, Chevron, and GE Vernova also announced plans for U.S. data centers powered by up to four gigawatts of domestic natural gas, with launch targeted by 2027.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: [email protected]
United States: +1-201-971-6302