Europe Construction Market: How a EUR 723 Billion Recovery Fund Is Building the Continent's Next Industrial Era
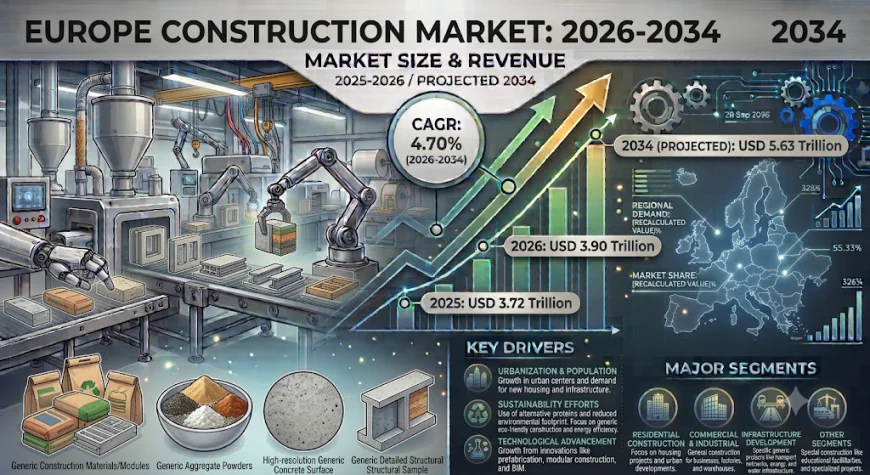
Europe construction market grew from USD 3.72 Trillion in 2025 to USD 3.90 Trillion in 2026 and is projected to reach USD 5.63 Trillion by 2034, growing at a CAGR of 4.70% during the forecast period 2026-2034.
 Team Imarc
There are moments in economic history when public investment and structural necessity align so completely that an entire industry enters a growth phase that is self-reinforcing rather than dependent on any single favourable variable. Europe's construction sector is in precisely such a moment. The EUR 723.8 Billion Recovery and Resilience Facility the largest coordinated public investment programme in European Union history is funding infrastructure, housing, energy transition, and digital connectivity projects simultaneously across 27 member states. At the same time, the EU Green Deal's building renovation mandates, REPowerEU's renewable energy targets, and a demographic housing crisis that 16.9% of EU residents living in overcrowded households makes viscerally concrete are all driving construction demand from independent directions that compound rather than cancel each other.
The market data reflects that convergence at an exceptional scale. The Europe construction market grew from USD 3.72 Trillion in 2025 to USD 3.90 Trillion in 2026 and is projected to reach USD 5.63 Trillion by 2034, growing at a CAGR of 4.70% during the forecast period. Adding nearly USD 1.91 Trillion in incremental annual construction output over nine years across the full spectrum of residential, commercial, industrial, infrastructure, and energy sectors is not simply a market growing. It is a continent rebuilding itself for the next half-century of climate, demographic, and economic requirements simultaneously.
What's Driving Growth in the Europe Construction Market?
- Residential construction's commanding 38.0% sector share in 2025 anchors the market's demand foundation through a housing crisis that no short-term policy intervention is resolving quickly. House prices have risen over 50% across the EU since 2010, while 9% of EU residents face housing payment arrears — creating both the social urgency and the political will to sustain public and private residential investment pipelines that reach deep into the forecast period. The EU-backed affordable housing programmes, build-to-rent institutional investment flows across the United Kingdom, Ireland, and Spain, and the accelerating energy-performance retrofit agenda under the revised Energy Performance of Buildings Directive are collectively sustaining residential construction as the market's single largest and most structurally reliable demand category.
- Germany's 25.0% market leadership reflects the country's unmatched concentration of industrial manufacturing, data centre investment, and residential renovation activity anchored by the federal government's EUR 500 Billion special infrastructure and climate fund, the KfW energy-efficient retrofit programme, and a growing gigafactory and battery manufacturing pipeline across Brandenburg, Saxony, and Saarland that is creating entirely new industrial construction demand categories that did not exist in meaningful volume five years ago.
- Transportation infrastructure's 18.7% sector share being sustained and expanded by the Trans-European Transport Network corridor upgrades, Rail Baltica, the Lyon-Turin tunnel, HS2 in the United Kingdom, the Frecciarossa high-speed rail network expansion in Italy, and metro programme extensions in Paris, Warsaw, Stockholm, and Madrid — representing a multi-trillion-euro pipeline of committed and funded public infrastructure investment whose delivery timelines extend well beyond 2034 and sustain specialist civil engineering, tunnelling, and rail contractor demand across the entire forecast period.
- Commercial construction at 24.6% of sector output being driven by the logistics warehouse boom tied to European industrial reshoring and e-commerce fulfilment network expansion, the rapid data centre capacity additions across FLAP-D markets Frankfurt, London, Amsterdam, Paris, and Dublin and a healthcare and hospitality investment wave across Southern Europe where ageing populations and tourism recovery are simultaneously creating new facility requirements at a pace that existing building stock cannot accommodate.
- Energy and Utility construction at 8.3% of output — the fastest-growing sub-segment with a projected CAGR of 6.5–7.0% through 2030 being powered by REPowerEU's offshore wind build-out in the North Sea and Baltic Sea, grid reinforcement and cross-border interconnector investment, hydrogen storage and distribution infrastructure, and the nuclear new-build programmes advancing at Hinkley Point C and Sizewell C in the United Kingdom and the EPR2 six-reactor programme in France targeting approximately EUR 72.8 Billion in committed investment.
Three Trends Reshaping the Industry
The Renovation Wave transforming retrofit from voluntary upgrade to regulatory imperative
The revised Energy Performance of Buildings Directive represents the most commercially consequential regulatory shift the European construction market has experienced in a generation and unlike previous building regulation updates, it is driving renovation activity not through incentive but through minimum performance standards that progressively make non-compliant buildings unlettable and unsaleable. The Renovation Wave strategy's target of doubling the annual energy renovation rate by 2030 covering 35 million building units across the EU — is creating a multi-decade procurement pipeline for insulation, triple-glazed fenestration, heat pump installation, solar PV integration, smart building controls, and the mechanical, electrical, and plumbing systems that deep retrofit requires. Italy's Superbonus scheme which generated a historic wave of residential retrofit activity before its subsequent adjustment demonstrated both the extraordinary speed at which policy-backed renovation demand can materialise and the scale of contractor capacity that structured retrofit programmes require. For specialist retrofit contractors, envelope insulation specialists, and MEP installers across Germany, France, the Netherlands, and Poland, the Renovation Wave represents the most durable and policy-protected growth pipeline in the European construction market one whose regulatory foundation makes it structurally resilient against the interest rate cycles and economic sentiment fluctuations that affect discretionary construction investment.
Modular and prefabricated construction scaling from Nordic pilot to continental delivery standard
The industrialisation of European construction the systematic replacement of on-site, trade-skill-dependent building processes with factory-manufactured, digitally designed, and precision-assembled components — is advancing from early adoption in the Nordics and the United Kingdom toward mainstream specification across residential, healthcare, education, and hospitality construction throughout the continent. Volumetric modular systems, panelised structural assemblies, and engineered timber cross-laminated timber packages are compressing programme times by 30–50% compared to traditional construction methods a productivity advantage that translates directly into lower financing costs for developers, faster operational commencement for public sector clients, and meaningfully reduced on-site labour requirements in markets where construction skills shortages are acute and worsening. The construction federations of Germany, the United Kingdom, the Netherlands, and the Nordics collectively report structural shortages of skilled trades and site engineers that cannot be resolved through recruitment or wage inflation alone making the offsite manufacturing model not merely an efficiency innovation but a structural response to a labour supply constraint that is becoming more severe with each passing year. For tier-1 contractors including Vinci, Bouygues, and Skanska all of whom have invested in proprietary modular delivery platforms this industrialisation trend is creating a durable competitive advantage over competitors who remain dependent on traditional on-site delivery methodologies whose cost and programme certainty are deteriorating as skills shortages intensify.
BIM, digital twins, and AI-enabled delivery transforming project economics across every construction segment
Building Information Modelling has completed its transition from a progressive delivery tool into a regulatory baseline across the United Kingdom, France, Germany, and the Nordics and the technology layer building above BIM is now advancing at a pace that is beginning to deliver measurable productivity improvements at project scale rather than in isolated pilot applications. Digital twins are being deployed on major airports, metro networks, and energy assets to enable full-lifecycle asset optimisation from the design phase through operations and maintenance compressing the information gap between what is designed, what is built, and what is operated that has historically been one of the construction industry's most persistent sources of cost overrun and quality deficiency. AI-powered scheduling and resource allocation tools are reducing programme uncertainty on complex multi-contractor infrastructure projects where the coordination of thousands of interdependent activities across dozens of specialist packages has traditionally been managed through human judgement alone. Computer vision site monitoring systems are detecting safety hazards, tracking workforce productivity, and generating progress data at a granularity and frequency that manual site supervision cannot approach. For the tier-1 European contractors Vinci, ACS, Bouygues, Skanska, Strabag, and Ferrovial who are investing most substantially in proprietary digital delivery platforms, these technology capabilities are creating competitive differentiation in public procurement processes where digital maturity is increasingly evaluated alongside price and programme certainty as a contract award criterion.
What the Market Numbers Actually Tell Us
The single-year growth from USD 3.72 Trillion in 2025 to USD 3.90 Trillion in 2026 USD 180 Billion in additional annual construction output added in twelve months, reflects a market operating across multiple simultaneously active demand cycles rather than a single growth catalyst driving incremental expansion. Residential construction's 38.0% dominance provides the volume base; commercial and industrial construction's combined 35.0% share reflects the private sector investment in logistics, data centres, and reshored manufacturing capacity; transportation and energy infrastructure's combined 27.0% share reflects the public investment programmes whose EUR 723.8 Billion RRF foundation is supplemented by national infrastructure funds including Germany's EUR 500 Billion special vehicle and France's EUR 54 Billion France 2030 plan. The competitive landscape, where tier-1 pan-European contractors including Vinci, ACS, Bouygues, and Skanska collectively account for 22–28% of regional revenue while a long tail of national champions and specialist contractors serves geographically and technically specific market segments ,reflects an industry that is simultaneously consolidating at the top through sustainability credentials and digital delivery capability while remaining fundamentally fragmented at the national and specialist level in ways that preserve meaningful competition and create ongoing consolidation opportunity.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe construction market lies at the intersection of the deep-retrofit Renovation Wave and the data centre construction boom ,two demand categories whose growth trajectories are both accelerating and whose combined technical complexity is creating procurement advantages for contractors with multidisciplinary capability that neither specialist retrofit firms nor conventional commercial contractors can match independently. Contractors who can credibly integrate building envelope performance, MEP systems design, smart building controls, and the critical power and cooling infrastructure that hyperscale data centre clients require within a single design-and-build delivery model are positioning themselves at the highest-margin frontier of the European construction market's growth ,serving client categories whose investment pipelines are policy-protected, privately funded, and growing faster than the market average in every national geography simultaneously. Equally, the Central and Eastern European markets — Poland, Romania, and the Western Balkans ,where EU cohesion funds, transport corridor investment, and residential expansion are driving construction growth rates above the continental average, represent geographic expansion opportunities for Western European contractors with the project management capability and supply chain relationships to deliver at scale in markets where local tier-1 competition is less entrenched than in the established Western European construction economies.
Browse Complete Report for Strategic Insights with TOC: Europe Construction Market