Europe Cosmetics Market: How Biotech Ingredients and Male Grooming Are Rewriting a USD 111 Billion Industry
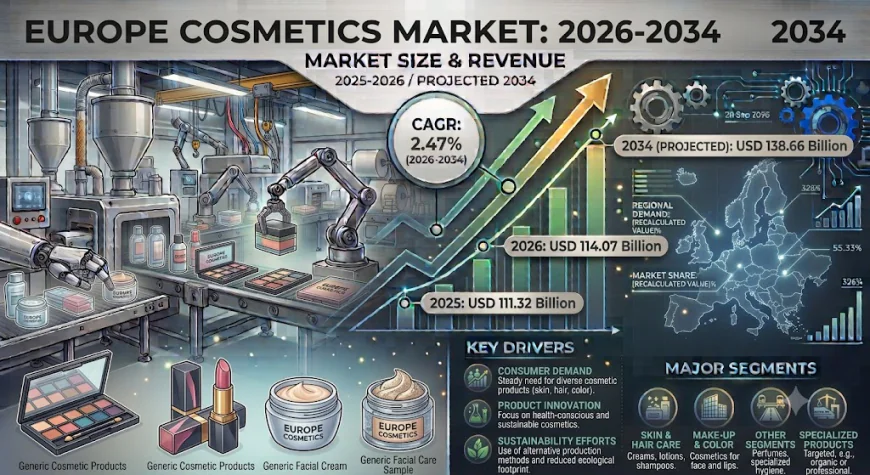
Europe cosmetics market increased from USD 111.32 Billion in 2025 to USD 114.07 Billion in 2026 and is projected to reach USD 138.66 Billion by 2034, growing at a CAGR of 2.47% during the forecast period
 Team Imarc
There is a laboratory in the Paris suburb of Aulnay-sous-Bois where L'Oréal's scientists are engineering peptides from fermentation processes , molecules that would previously have been extracted from animal sources or synthesised through petrochemical pathways , and turning them into the efficacy claims that will define the next generation of European prestige skincare. A few hundred kilometres away in Hamburg, Beiersdorf's R&D team is advancing Thiamidol, a patented active ingredient targeting hyperpigmentation, into a clinical evidence base robust enough to rival pharmaceutical dermatology. And in Berlin, Paris, and London simultaneously, a generation of indie brands built on gender-neutral positioning, ingredient transparency, and social commerce distribution is capturing market share that heritage brands had considered structurally protected for decades.
These are not isolated developments. They are the three converging forces , biotech-driven ingredient science, the structural expansion of male and unisex beauty, and digital-native brand disruption , that are reshaping a European cosmetics market of extraordinary scale and maturity. The Europe cosmetics market increased from USD 111.32 Billion in 2025 to USD 114.07 Billion in 2026 and is projected to reach USD 138.66 Billion by 2034, growing at a CAGR of 2.47% during the forecast period. Adding USD 27.34 Billion in annual market value over nine years , in a consumer category as established and culturally embedded as European beauty , reflects a market that is expanding not through the acquisition of new consumers but through the progressive deepening of value per consumer across a more sophisticated, more ingredient-literate, and more sustainability-conscious purchasing population than has ever existed before.
What's Driving Growth in the Europe Cosmetics Market?
- Skin and sun care products commanding 33.0% of product type share in 2025 reflects the most commercially significant structural shift in European beauty purchasing of the past decade , the elevation of skincare from a functional personal care routine into a considered, efficacy-driven investment in long-term dermatological health. Pharmacy-channel brands including La Roche-Posay, Avène, Vichy, Bioderma, Eucerin, and Uriage are commanding prestige-adjacent pricing in France, Germany, Italy, and Spain, supported by dermatologist endorsement, clinical trial evidence, and the kind of repeat-purchase loyalty that colour cosmetics trends cannot sustain across economic cycles.
- Germany's 21.6% market leadership anchored by the scale of Beiersdorf's Nivea and Eucerin franchises, Henkel Beauty Care's haircare dominance, and the extraordinary distribution reach of dm-drogerie markt and Rossmann , both of which have built Europe's most commercially significant certified-natural private-label beauty ranges in Alverde and Alterra respectively , creates a market structure where sustainability-led organic beauty is simultaneously mainstream and premium, distributed at mass-market price points through drugstore channels that reach the full spectrum of the German consumer population.
- Supermarkets and hypermarkets commanding 32.0% of distribution channel share reflects the foundational role of everyday retail in sustaining the volume base that supports the entire European beauty market's scale , while the progressive expansion of specialty perfumery chains including Douglas, Sephora, and Marionnaud, pharmacy and para-pharmacy channels delivering dermocosmetic authority, and a rapidly growing e-commerce ecosystem combining Amazon Beauty, brand-owned D2C sites, and social commerce platforms including TikTok Shop together represent the channels where per-unit value, brand storytelling depth, and consumer relationship quality are highest and growing fastest.
- Conventional cosmetics maintaining 80.0% category share while the organic segment at 20.0% grows faster than the overall market reflects a commercial dynamic that is less competitive displacement than progressive market expansion , the organic and clean-beauty category is adding incremental spend from consumers upgrading their routine rather than systematically replacing conventional products, creating a market where both categories grow simultaneously and the total addressable spend per consumer increases as ingredient sophistication rises.
- Male grooming at 21.7% and unisex at 20.3% of gender segment share together representing 42.0% of the market's combined demand signals that the binary assumption on which European beauty has historically been commercially organised , that cosmetics are overwhelmingly a female consumer category , is being structurally dismantled by cultural shifts, social media normalisation of male skincare, and the commercial investment of major brands in dedicated male skincare, beard-care, and premium fragrance lines that are growing at rates meaningfully above the overall market average in Italy, France, and the United Kingdom.
Three Trends Reshaping the Industry
Biotech-derived actives and precision fermentation transforming the efficacy frontier of European skincare
The most commercially consequential scientific development reshaping the Europe cosmetics market is the systematic replacement of botanically extracted and petrochemically synthesised active ingredients with fermentation-derived, bio-identical, and precision-manufactured molecules that deliver superior efficacy, more consistent quality, and dramatically lower environmental impact than their predecessors. L'Oréal's 2025 showcase at Viva Technology , demonstrating a broad portfolio of biotech-collaboration innovations built on partnerships with startups and research institutions , illustrated how the world's largest beauty company is structuring its R&D investment around the premise that biotech will define the efficacy claims of prestige skincare for the next decade as comprehensively as retinol and hyaluronic acid defined the previous one. Beiersdorf's continued commercial expansion of Thiamidol , a patented ingredient developed through systematic screening of over 50,000 compounds , into Eucerin and Nivea product ranges across Germany, France, and the United Kingdom demonstrates how proprietary biotech investment is building durable competitive moats that generic and private-label competitors cannot bridge through formulation imitation alone. As fermentation-derived peptides, lab-grown squalane, and bio-identical hyaluronic acid progressively displace less efficient conventional alternatives, the cost curve of biotech actives is following the same downward trajectory that has historically made premium ingredient innovation accessible to mass-market price points , expanding the total addressable market for efficacy-led skincare beyond the prestige consumer segment where it first gained commercial traction.
Clean beauty and the EU Green Claims Directive creating a regulatory competitive frontier
The mainstreaming of clean beauty across European retail channels , from Sephora Europe and Douglas's dedicated certified-natural sections to dm-drogerie markt's Alverde range and Naturalia's pharmacy ecosystem in France , has created a consumer market that is simultaneously large enough to matter commercially and sufficiently ingredient-literate to detect and penalise greenwashing claims that cannot be substantiated through recognised third-party certification. The EU's Green Claims Directive , actively being enforced by national consumer protection authorities across France, Germany, and the Netherlands , is converting the clean beauty marketing environment from a space where aspirational environmental claims could be made with limited evidentiary burden into one where only brands with credible COSMOS, Ecocert, NATRUE, or equivalent certification and genuinely reformulated ingredient compositions can sustain clean positioning without regulatory intervention risk. For brands with authentic clean credentials, this regulatory shift is commercially advantageous , it raises the barrier to greenwashing competitors and validates the investment they have made in reformulation and certification compliance. For brands whose clean positioning has relied on selective ingredient marketing without comprehensive formula transparency, it is a structural challenge that will require substantive product investment to resolve rather than communication adjustment alone.
Male grooming and gender-neutral beauty structurally expanding the market's consumer base
The commercial expansion of European male cosmetics beyond its historical concentration in functional shaving products into a sophisticated, multi-category grooming ecosystem , spanning dedicated skincare routines, beard-care regimens, premium fragrance, and colour cosmetics for men,represents the most structurally significant demand expansion the European beauty market has generated from within its existing geographic footprint in the current decade. The male skincare category's growth is being sustained simultaneously by three independent demand drivers: established heritage brands including Nivea Men and L'Oréal Men Expert capturing the mass-market entry point; premium brands including Bulldog, Lab Series, and Clinique for Men building the considered grooming category; and prestige fragrance houses in France and Italy , where male grooming culture is deepest and most commercially validated , developing dedicated male skincare lines that leverage the consumer relationships built through decades of fragrance loyalty. Intersecting with this male expansion is the gender-neutral fragrance and unisex skincare movement being led by indie brands including Byredo, Le Labo, Maison Margiela Replica, and a growing roster of European direct-to-consumer labels that have built substantial consumer followings through social media without traditional retail distribution , reaching a Gen-Z consumer cohort for whom gender-neutral beauty positioning is not a niche preference but a baseline expectation that mainstream brands are only beginning to address with the commercial seriousness the demographic's purchasing power demands.
What the Market Numbers Actually Tell Us
The single-year growth from USD 111.32 Billion in 2025 to USD 114.07 Billion in 2026 , adding USD 2.75 Billion in annual market value in twelve months , reflects the compounding effect of premiumisation driving higher average transaction values across skincare and fragrance, the progressive volume expansion of male and unisex categories into previously female-dominated product adjacencies, and the organic and clean-beauty segment growing at an estimated 3.5% CAGR that meaningfully outpaces the headline market rate. The trajectory to USD 138.66 Billion by 2034 implies the addition of over USD 27 Billion in incremental annual consumer spending , distributed across the full spectrum of national markets but concentrated most heavily in Germany, France, the United Kingdom, Italy, and Spain, which together account for over 81% of European cosmetics revenue and whose combined market dynamics set the commercial agenda for the brands and retailers serving the entire continent. For the leading multinational beauty groups , L'Oréal, Unilever, Beiersdorf, LVMH, and Estée Lauder , who collectively control a substantial majority of European category revenue, the market's moderate but structurally consistent growth trajectory provides the commercial foundation from which premiumisation, biotech investment, and sustainability transformation can be funded without dependence on volume growth that a mature market of this scale cannot reliably generate.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe cosmetics market sits at the intersection of AI-powered personalisation and the pharmacy and para-pharmacy channel's unique dermatological authority , a combination that no other beauty distribution format can replicate with equivalent credibility. Pharmacy chains including Boots in the United Kingdom, Pharmacies Lafayette in France, and the German para-pharmacy networks that distribute La Roche-Posay, Vichy, and Eucerin are positioning themselves as the integration point between consumer skin health concerns, dermatologist-endorsed product recommendations, and AI-powered diagnostic tools that can translate clinical skin assessment into personalised skincare regimens at the scale and accessibility of mass retail rather than dermatology clinic appointments. Brands that invest in AI diagnostic tools, pharmacist training programmes, and integrated loyalty and replenishment models that use the pharmacy relationship as a long-term skin health management platform , rather than a single-transaction distribution channel , are positioned to build the kind of recurring, clinically anchored consumer relationship that no colour cosmetics trend cycle or social media campaign can displace. Simultaneously, Poland, the Nordics, and the Netherlands , currently representing a combined minority of European cosmetics revenue but growing faster than the continental average on the back of rising per-capita beauty spend, strong organic-beauty consumer literacy, and digitally native younger populations , represent the geographic expansion frontier where early brand investment is most likely to build durable market positions before competitive intensity reaches the levels that characterise the mature Western European markets where category leadership has been established for decades.
Browse Complete Report for Strategic Insights with TOC: Europe Cosmetics Market