European Cross-Laminated Timber Market: Why Mass Timber Is Redefining the Future of Urban Construction
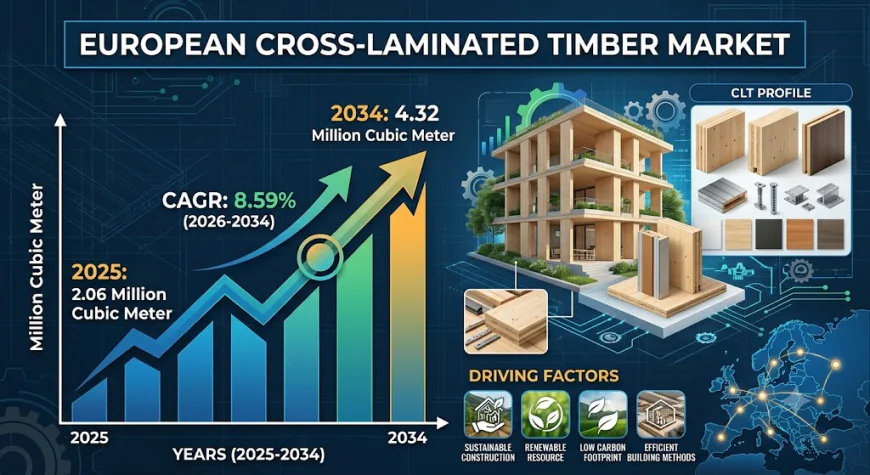
European cross-laminated timber market reached 2.06 Million Cubic Meter in 2025 and is projected to reach 4.32 Million Cubic Meter by 2034, growing at a CAGR of 8.59% during 2026–2034.
 Team Imarc
There is a building material quietly dismantling assumptions that have governed European construction for over a century. It weighs significantly less than concrete, sequesters carbon rather than emitting it during production, can be precision-machined in a factory and assembled on-site in a fraction of the time of conventional construction, and in fire testing demonstrates a predictable, self-limiting charring behaviour that modern building codes are increasingly recognising as a credible safety profile. Cross-laminated timber is not an experimental material — it is a structurally certified, commercially proven engineering product that is progressively displacing concrete and steel from applications where both have been unquestioned defaults for decades.
The market trajectory reflects that displacement actively underway. The European cross-laminated timber market reached 2.06 Million Cubic Meter in 2025 and is projected to reach 4.32 Million Cubic Meter by 2034, growing at a CAGR of 8.59% during 2026–2034. A market that more than doubles in volume over nine years — in a construction materials category defined by long project cycles and conservative procurement practices — signals not an emerging trend but a structural inflection point that leading European manufacturers, architects, and policymakers have already committed to at scale.
What's Driving Growth in the European Cross-Laminated Timber Market?
- Supportive EU environmental regulation creating a policy-driven floor for CLT demand is the most powerful structural force shaping the market's long-term trajectory. The EU Emissions Trading System's anticipated extension to construction-related emissions by 2027 will add measurable cost premiums to concrete and steel — directly improving CLT's competitive cost position without requiring any reduction in timber's own production costs. Simultaneously, building codes across Austria, Germany, Sweden, and the United Kingdom are being progressively revised to permit taller timber structures, with several jurisdictions now allowing wooden buildings of up to eighteen storeys, opening urban mid-rise and high-rise applications that were structurally inaccessible to CLT a decade ago.
- Record CLT production capacity expansion demonstrating industry confidence at the largest scale the European market has ever seen. CLT manufacturers in the DACH region, Italy, and the Czech Republic collectively produced 1.42 Million Cubic Meters in 2024 — a nine percent increase over the previous year and a new industry record — reflecting simultaneous output growth across the continent's most established manufacturing nations. This production expansion is not speculative; it is responding to firm order pipelines from residential developers, municipal housing authorities, and commercial developers whose own project commitments create multi-year demand visibility for CLT producers.
- Residential construction commanding 45% of market share as Europe's most urgent application segment anchors consistent, policy-reinforced demand. Social housing programmes across European cities are accelerating CLT adoption through prefabricated modular construction that reduces build times by approximately thirty percent compared to conventional methods — a productivity advantage that translates directly into lower labour costs and faster revenue recognition for developers operating under housing delivery pressure. In Austria, a substantial proportion of new multi-family residential units now incorporate CLT, reflecting how deeply the material has penetrated mainstream residential procurement in the market's most advanced adoption environment.
- Custom CLT's 62% product type dominance reflecting the growing sophistication of European construction projects that require architectural flexibility, structural complexity, and project-specific dimensional specifications that standard blank panels cannot efficiently deliver. KLH Massivholz's investment in advanced CNC production technology at its Austrian facilities — enabling precision panel customization with integrated openings, embedded mechanical systems, and exact dimensional tolerances — illustrates how leading manufacturers are building the technical capability to serve increasingly demanding client requirements across both residential and commercial segments.
- Wall panels' 46% element type share underpinning the market's most commercially active product category through their combination of structural load-bearing capability, thermal insulation performance, acoustic attenuation, and prefabrication compatibility that makes them the default structural solution in both residential and commercial CLT applications. Stora Enso's CLT wall panel systems — deployed in the world's first large-scale timber data center in Falun, Sweden, developed by EcoDataCenter — demonstrate that the application universe for CLT wall panels is expanding well beyond conventional residential and commercial construction into technically demanding infrastructure categories.
Three Trends Reshaping the Industry
Digital fabrication and BIM integration transforming CLT from a building material into a precision manufacturing system
The commercial significance of cross-laminated timber's compatibility with digital fabrication technology cannot be overstated in the context of a construction industry historically characterised by on-site variability and quality inconsistency. Advanced CNC machining centres are enabling precision cutting and customization of CLT panels with integrated openings, connection details, and embedded service channels that reduce on-site modification requirements to near zero — transforming construction assembly from a trade-skill-dependent process into a logistics and coordination exercise. Stora Enso's April 2024 completion of a prefabricated timber school building in Nantes, France — utilising its automated coating line for CLT and demonstrating the efficiency of modular CLT construction in educational infrastructure — illustrates how digital fabrication is enabling CLT to compete for project types that previously defaulted to conventional materials on the basis of construction programme certainty. Ledinek's third-generation X-Press hydraulic pressing systems, capable of producing panels up to sixteen metres long and 3.5 metres wide with consistent pressure distribution and rapid cycle times, are enabling the high-throughput manufacturing that the market's accelerating volume growth requires without compromising the dimensional accuracy that precision assembly demands.
Circular economy innovation positioning CLT as the built environment's carbon storage solution
The emergence of genuinely circular cross-laminated timber production — where reclaimed wood, post-consumer timber, and demountable construction systems enable material recovery at end of building life — is repositioning CLT from a low-carbon alternative to a carbon-positive building system within the European construction narrative. Stora Enso's September 2025 achievement of producing a CLT panel entirely from reclaimed wood at its Ybbs Mill in Austria — as part of the EU-funded Woodcircles initiative, with the panels forming the structural core of a modular demonstration building toured across European cities including Turin, Rotterdam, and Tartu — represents the most commercially ambitious demonstration of circular CLT production yet achieved at structural scale. The growing interest in mechanically fastened CLT panels — which avoid chemical adhesive bonding and enable material recovery without the need for chemical separation processes — reflects a design philosophy shift toward buildings conceived as material banks rather than permanent structures, aligning with European circular economy policy objectives in ways that concrete and steel construction cannot readily replicate. Mayr-Melnhof Holz's November 2024 EUR 13 Million investment in solar power installations across its plants in Leoben, Gaishorn, Reuthe, Paskov, Wismar, and Olsberg signals that the industry's sustainability commitment is extending beyond product-level carbon sequestration into manufacturing-level decarbonisation — building the full-lifecycle sustainability credentials that institutional procurement increasingly requires.
Mid-rise urban housing driving the market's highest-volume growth segment
The convergence of European urban densification pressure, housing shortage urgency, and progressive building code reform has created the conditions for CLT's most commercially significant application expansion since the material's commercial introduction. Mid-rise buildings of five to ten storeys — commanding 44% of the storey class segment in 2025 — represent the sweet spot where CLT's structural performance, weight advantages over concrete, construction speed benefits, and now-permitted building heights intersect with the housing typology that European cities most urgently need. Municipal housing initiatives in Germany, Austria, and Sweden are providing the public sector demand anchor that de-risks private sector investment in CLT-specific design and procurement capability, creating a positive adoption feedback loop where each successfully completed CLT residential project builds the professional familiarity and supply chain confidence that makes the next project faster and cheaper to deliver. A June 2025 German data center company's unveiling of a prefabricated timber module for data center applications — accommodating five server racks within a 6.5 × 3.0 × 3.4 metre CLT enclosure featuring a propane-powered indirect free cooling system — further illustrates how CLT's application universe is expanding into technically demanding commercial categories that further validate the material's structural and thermal performance credentials across a diversifying client base.
What the Market Numbers Actually Tell Us
A CAGR of 8.59% sustained over nine years in a construction materials market defined by multi-year project cycles, conservative specification practices, and significant capital barriers to manufacturing capacity expansion reflects a structural adoption inflection rather than a marginal share gain. The doubling of market volume from 2.06 Million Cubic Meters to 4.32 Million Cubic Meters over the forecast period requires not only demand growth but the committed manufacturing investment to supply it — and the production records already being set across the DACH region, combined with the capacity expansion announcements from Hydro, Hammerer Aluminium Industries, and Mengtai Group in adjacent mass timber categories, confirm that European producers are making those commitments in the expectation of sustained demand rather than cyclical optimism. The structural applications segment's 78% market share dominance confirms that CLT's commercial story is built on engineering performance credentials rather than aesthetic or marketing positioning — a foundation that translates more durably into repeat specification and procurement loyalty than trend-driven purchasing decisions.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the European cross-laminated timber market sits at the intersection of high-rise timber construction and the updated Eurocode 5 structural design provisions currently under revision — which, when finalised, will provide the standardised engineering framework that enables architects and structural engineers across all European markets to specify CLT for buildings above ten storeys with the same regulatory confidence that currently exists for concrete and steel. Manufacturers who invest now in the production capability, engineering expertise, and project reference portfolio to serve high-rise timber applications — currently representing a small but rapidly growing share of the storey class segment — will hold a first-mover advantage in what is structurally the market's highest-value growth frontier. Simultaneously, the mechanically fastened CLT segment — currently overshadowed by adhesive-bonded production's 71% market dominance — represents a structurally distinct commercial opportunity for producers willing to invest in the demountable construction systems and building-as-material-bank design methodologies that European circular economy policy is progressively incentivising through carbon pricing, embodied carbon regulation, and public sector procurement criteria that reward end-of-life material recoverability.