Polyvinyl Chloride Market Size, Share & Trends Analysis Report, Forecast 2034
Vehicle makers increasingly rely on lightweight PVC formulations for cable insulation, interior trims, and underbody protection to trim vehicle weight, enhance energy efficiency, and extend driving range.
 Kapil Kazade
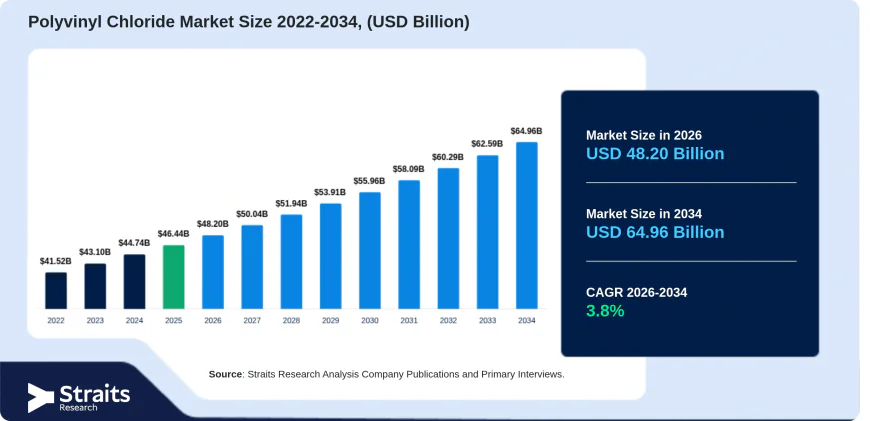
The global polyvinyl chloride market was valued at USD 46.44 billion in 2025 and is projected to expand from USD 48.20 billion in 2026 to USD 64.96 billion by 2034, registering a CAGR of 3.8% Growth is predominantly fueled by extensive global infrastructure expansion, increasing residential construction, and rising demand for lightweight, durable pipes and fittings across municipal and agricultural sectors
Polyvinyl Chloride (PVC) Market: Comprehensive Industry Analysis & Global Outlook
The global polyvinyl chloride (PVC) market is experiencing steady expansion, driven by widespread infrastructure development, rapid urbanization, and growing industrial applications. Valued at USD 46.44 billion in 2025 and USD 48.20 billion in 2026, the global PVC market is projected to reach USD 64.96 billion by 2034, expanding at a compound annual growth rate (CAGR) of 3.8% during the forecast period from 2026 to 2034.
PVC is one of the most widely produced synthetic thermoplastic polymers globally, renowned for its exceptional strength, lightweight nature, flame retardancy, and high chemical resistance. Manufactured through the polymerization of vinyl chloride monomer (VCM)—typically utilizing hydrocarbon feedstocks from oil and natural gas or increasingly bio-based ethylene derived from sugar crops—PVC resin is formulated into two distinct categories: rigid PVC and flexible PVC. These primary forms serve a broad spectrum of sectors including building and construction, packaging, electrical and electronics, automotive, healthcare, and consumer goods.
Key Market Drivers and Growth Catalysts
The continuous growth of the global PVC market is primarily anchored by the robust construction and building sector. Attributes such as durability, minimal maintenance requirements, resistance to weathering and corrosion, and ease of fabrication make PVC an indispensable structural component. PVC is extensively utilized in windows, doors, roofing membranes, wall coverings, and decorative flooring. The accelerating pace of urban development across developing economies, paired with ongoing infrastructure revitalization programs in developed nations, creates a durable, high-volume demand stream for PVC products.
Another major market catalyst is the surge in advanced technical applications, such as 3D printing technology. The integration of specialty PVC filaments—often termed 3D vinyl—delivers superior UV resistance, lower embodied energy content, enhanced fire retardancy, and excellent rigidity compared to conventional polymers like ABS or PET. Moreover, the global shift toward electric vehicles (EVs) presents lucrative expansion avenues for PVC manufacturers. Vehicle makers increasingly rely on lightweight PVC formulations for cable insulation, interior trims, and underbody protection to trim vehicle weight, enhance energy efficiency, and extend driving range.
Segmental Overview
- By Type: The market is segregated into Rigid PVC and Flexible PVC. Rigid PVC commands the major market share (holding approximately 46.7%), underpinned by its high structural integrity, flame resistance, and long operational lifespan across heavy-duty building components. Flexible PVC, blended with plasticizers, maintains strong adoption in wire insulation, flexible tubing, medical devices, and film packaging.
- By Application: The Pipes & Fittings segment leads overall revenue generation. PVC pipes are preferred over metallic alternatives due to their non-corrosive properties, smooth interior surfaces preventing flow resistance, affordability, and effortless installation across municipal water supply, agricultural irrigation, sewage, and industrial fluid transport networks. Other vital applications include film & sheets, profiles & tubes, wires & cables, and bottles.
- By End-User: The Building and Construction sector stands as the single largest revenue-generating end-use industry, followed by packaging, electrical & electronics, consumer goods, and transportation.
Regional Dynamics
The Asia-Pacific region dominates the global PVC market landscape, capturing a massive 46.5% share in 2025. This dominance is propelled by booming construction activities, expanding manufacturing facilities in Southeast Asian nations (such as Vietnam and Indonesia), and strong domestic consumption in major hubs like China and India. Prominent global producers originating from Asia, including Shin-Etsu Chemical and Formosa Plastics Group, play a defining role in shaping global supply chains.
North America maintains a prominent position, accounting for roughly 27% of the market share, supported by large-scale residential construction, pipe replacement programs, and competitive raw material costs driven by domestic shale gas resources. Meanwhile, Europe demonstrates significant demand for sustainable, recyclable PVC materials and energy-efficient building profiles.
Market Restraints and Environmental Landscape
Despite bright growth prospects, the market faces notable challenges. Fluctuations in crude oil and natural gas prices directly impact VCM manufacturing costs. Additionally, heightened scrutiny regarding environmental and health impacts—specifically related to toxic emissions during incineration, phthalate plasticizers, and end-of-life disposal—has led to stringent regulatory standards globally. In response, top chemical manufacturers are focusing heavily on bio-attributed PVC resins, eco-friendly non-phthalate plasticizers, advanced closed-loop recycling processes, and alternative high-performance polymers such as HDPE.
Get the Complete Market Report=https://straitsresearch.com/report/polyvinyl-chloride-market