Self Employed Loan App: Online Loan Options for Independent Professionals
Although requirements differ among lenders, commonly requested documents may include: PAN and identity documents Address proof Recent bank statements Income...
 divyanshu1112
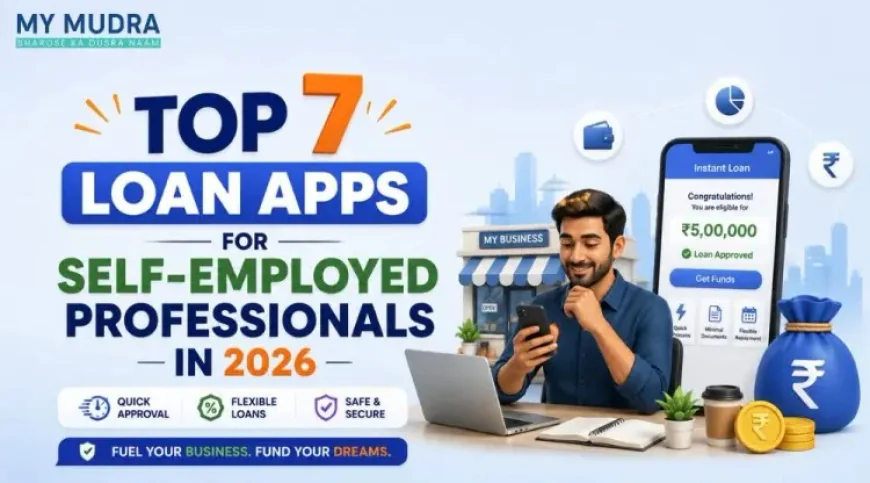
Self-employment offers the freedom to work independently, but it can also make borrowing slightly different from the process followed by salaried professionals. Freelancers, consultants, doctors, designers, traders, shop owners, and entrepreneurs may have income coming from multiple sources instead of receiving a fixed salary every month.
When additional funds are needed, online lending platforms can provide a convenient starting point. A self employed loan app allows eligible applicants to explore loan options digitally, understand basic requirements, and submit their details online. Depending on the lender and product, the process may involve online KYC, income verification, bank statement analysis, and credit assessment.
However, choosing a loan app should involve more than looking for a quick application process. Understanding the loan amount, interest rate, fees, repayment period, eligibility criteria, and lender information can help borrowers make a more informed decision.
Why Self-Employed Individuals May Need Loans
Financial requirements can arise for both personal and professional reasons. A freelancer may need funds to purchase a laptop or other equipment, while a consultant could require money to manage a temporary cash-flow gap. Business owners may need additional working capital, whereas an individual may require funds for education, medical expenses, travel, or household needs.
The appropriate loan product depends largely on the purpose of borrowing. Personal loans may be considered for personal expenses, while business-oriented financing can be more appropriate when the money is required for business operations.
Digital platforms allow borrowers to research these options without necessarily visiting several physical branches.
How Does a Self Employed Loan App Work?
The exact process varies depending on the platform and lending partner, but an online application generally starts with basic personal and financial information.
An applicant may need to provide their name, contact details, occupation, income information, and requested loan amount. The lender can then ask for KYC and financial documents to verify the information provided.
For self-employed borrowers, income assessment may involve documents different from those used for salaried applicants. Depending on the lender, these can include Income Tax Returns, bank statements, GST-related records, business registration documents, or other financial information.
Once the required information is submitted, the lender evaluates the application according to its internal eligibility and credit policies. Approval, loan amount, interest rate, and repayment terms can therefore vary between applicants.
What Makes a Loan App Suitable for Self-Employed Borrowers?
People looking for the best loan app for self employed applicants should compare the complete borrowing terms instead of focusing on one feature.
Eligibility is a good starting point. Check whether the lender accepts self-employed professionals and whether there are requirements relating to income, business vintage, credit history, or documentation.
The cost of borrowing is another major consideration. Look at the applicable interest rate along with processing fees, taxes, prepayment charges, late payment fees, and other costs mentioned in the loan agreement.
Repayment flexibility can also matter. Compare available tenures and calculate the EMI before deciding whether the proposed repayment fits within your monthly budget.
It is equally useful to check the identity of the lender and read the applicable terms and conditions before proceeding with an application.
Documents That May Be Needed
Self-employed applicants should keep their financial records organised before beginning a loan application. Although requirements differ among lenders, commonly requested documents may include:
- PAN and identity documents
- Address proof
- Recent bank statements
- Income Tax Returns
- GST documents, where applicable
- Business registration or proof of business activity
- Financial statements or other income-related records
Having accurate and updated documents available can make the verification process more convenient.
Personal Loans for Self-Employed Professionals
A self employed personal loan app can be relevant when an individual needs financing for personal expenses. Since personal loans are commonly unsecured, eligible applicants may not need to provide collateral, although the exact structure depends on the lender.
Before taking such a loan, consider the amount actually required rather than borrowing more than necessary. A higher loan amount can result in a larger EMI and greater total repayment.
It is also useful to calculate existing financial commitments before taking on another monthly payment. This gives borrowers a clearer understanding of whether the proposed EMI is manageable.
For a detailed look at loan options available to self-employed individuals, eligibility considerations, and the application process, visit this guide on self employed loan app.
Credit History and Loan Approval
Credit history can be an important part of the loan assessment process. Lenders may review an applicant's previous repayment behaviour, outstanding credit obligations, and overall credit profile before making a decision.
Self-employed individuals can also benefit from maintaining consistent financial records. Regular banking transactions, proper tax filings, and accurate income documentation can provide lenders with information needed to evaluate the application.
However, meeting basic eligibility conditions does not necessarily guarantee approval. Each lender applies its own assessment criteria, and the final terms may differ based on the applicant's profile.
Personal Loan or Business Financing?
Understanding the purpose of the loan can help determine which type of financing to explore.
If the requirement involves personal expenses such as education, medical treatment, family needs, or travel, a personal loan may be relevant if the borrower meets the applicable criteria.
For requirements such as inventory purchases, business expansion, equipment, working capital, or operational expenses, a business loan or another business financing product may be more suitable.
The interest rate, repayment period, documentation, and eligibility requirements can vary between these products, so comparing them before applying is worthwhile.
What Should You Check Before Applying Online?
Before accepting a loan offer, review the complete cost and repayment conditions. Do not focus only on the advertised interest rate. Check the processing fee, applicable taxes, EMI, tenure, late payment charges, and prepayment or foreclosure conditions.
Also make sure the information entered in the application matches the supporting documents. Incorrect or inconsistent details can create complications during verification.
Applicants should read the loan agreement carefully and understand the repayment schedule before accepting the offer.
Final Thoughts
Online lending has created a convenient way for self-employed professionals to explore borrowing options. Whether you earn through freelancing, consulting, trading, professional services, or your own business, digital applications can simplify the initial loan application process.
At the same time, convenience should not replace careful comparison. Before selecting a loan app, consider eligibility, documentation, interest rates, fees, repayment terms, lender details, and your own ability to repay.
Taking time to compare these factors can help self-employed borrowers approach online borrowing with a clearer understanding of the financial commitment involved.