Clinical Nutrition Market to Grow from USD 33.06 Billion in 2025 to USD 52.08 Billion by 2034
The global clinical nutrition market size was valued at USD 33.06 billion in 2025 and is projected to grow from USD 34.77 billion in 2026 to USD 52.08 billion by 2034, registering a CAGR of 5.18% during the forecast period from 2026 to 2034.
 Dhiraj V
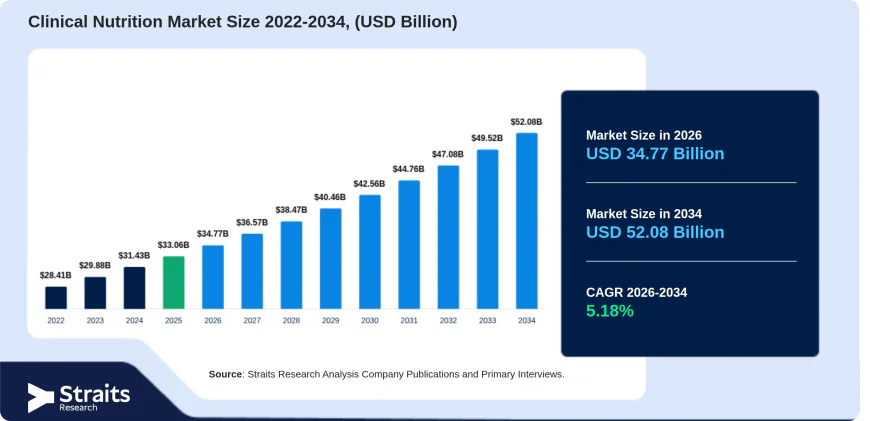
The global clinical nutrition market is experiencing steady growth, supported by increasing prevalence of chronic diseases, rising demand for specialized nutritional support, growing geriatric populations, and expanding healthcare infrastructure. The global clinical nutrition market size was valued at USD 33.06 billion in 2025 and is projected to grow from USD 34.77 billion in 2026 to USD 52.08 billion by 2034, registering a CAGR of 5.18% during the forecast period from 2026 to 2034.
Clinical nutrition products provide essential nutritional support to patients who cannot meet their dietary requirements through conventional food intake. Enteral and parenteral nutrition are increasingly used across hospitals, long-term care facilities, home healthcare settings, and specialized treatment centers. Growing awareness of the role of nutrition in recovery, disease management, and patient outcomes is further supporting market expansion.
Market Drivers
Rising Prevalence of Chronic Diseases
The increasing prevalence of chronic conditions such as cancer, diabetes, gastrointestinal disorders, and cardiovascular diseases is driving demand for specialized nutritional support. Patients undergoing intensive treatments or experiencing impaired nutrient absorption may require enteral or parenteral nutrition to maintain adequate nutritional intake. The growing chronic disease burden is therefore expanding the need for clinical nutrition products across healthcare settings.
Growing Geriatric Population
The global aging population is contributing to increased demand for clinical nutrition solutions. Older adults are more likely to experience conditions associated with reduced appetite, swallowing difficulties, impaired nutrient absorption, and chronic disease. Healthcare providers are increasingly incorporating specialized nutritional support into treatment and long-term care programs to address these nutritional requirements.
Increasing Adoption of Enteral and Parenteral Nutrition
Healthcare facilities are increasingly using enteral and parenteral nutrition for patients who are unable to consume or absorb sufficient nutrients through regular diets. Improvements in formulations, delivery systems, and clinical protocols are making nutritional support more adaptable to different patient requirements. This is supporting the adoption of clinical nutrition products across hospitals, intensive care units, and home healthcare environments.
Expansion of Home Healthcare and Personalized Nutrition
The expansion of home healthcare is creating additional opportunities for clinical nutrition products outside traditional hospital environments. Patients requiring long-term nutritional support can increasingly receive care at home with appropriate monitoring and delivery systems. At the same time, greater emphasis on individualized nutrition is encouraging the development of formulations designed for specific medical conditions and patient needs.
Market Challenges
High Cost of Specialized Clinical Nutrition Products
Clinical nutrition products, particularly specialized formulations and parenteral nutrition solutions, can involve significant production, storage, and delivery costs. Healthcare providers and patients in markets with limited reimbursement coverage may face financial barriers to long-term nutritional support. Cost considerations can therefore affect adoption, particularly in developing healthcare systems.
Risk of Complications Associated with Nutritional Support
Enteral and parenteral nutrition require appropriate patient assessment, formulation, administration, and monitoring. Improper use can result in complications such as infections, metabolic imbalances, or gastrointestinal issues. Healthcare professionals therefore require appropriate training and monitoring protocols, which can increase the complexity of clinical nutrition management.
Regulatory and Quality Requirements
Clinical nutrition products must comply with stringent safety, quality, labeling, and manufacturing requirements. Manufacturers need to maintain consistent formulation quality while meeting regulatory standards across different markets. These requirements can increase product development costs and lengthen the time required to introduce new formulations.
Market Segmentation
The clinical nutrition market is segmented based on route of administration, product type, application, and end user.
By Route of Administration:
- Enteral Nutrition
- Parenteral Nutrition
Enteral nutrition represents an important segment as it provides nutritional support through the gastrointestinal tract for patients who are unable to consume adequate food orally but have sufficient digestive function.
By Product Type:
- Enteral Nutrition Products
- Parenteral Nutrition Products
- Nutritional Supplements
- Specialized Medical Foods
- Others
Enteral and parenteral formulations remain core product categories, while specialized medical foods and nutritional supplements are gaining importance as healthcare providers increasingly focus on condition-specific nutritional requirements.
By Application:
- Cancer
- Diabetes
- Gastrointestinal Disorders
- Neurological Disorders
- Critical Care
- Others
Critical care and chronic disease management represent significant application areas because patients with severe illnesses often require additional nutritional support during treatment and recovery.
By End User:
- Hospitals
- Long-Term Care Facilities
- Home Healthcare
- Specialty Clinics
- Others
Hospitals account for a significant share of demand due to the extensive use of clinical nutrition in intensive care, surgical recovery, oncology, and other specialized treatment settings. Home healthcare is also expanding as long-term nutritional support increasingly moves beyond hospital environments.
Regional Insights
North America
North America represents a significant market for clinical nutrition, supported by advanced healthcare infrastructure, high healthcare expenditure, and widespread use of specialized nutritional support. The presence of established healthcare providers and clinical nutrition manufacturers is further supporting product availability. Growing demand for home healthcare and personalized nutritional care is also contributing to regional market development.
Europe
Europe is witnessing steady growth in clinical nutrition demand due to its aging population, established healthcare systems, and increasing focus on nutritional management in hospitals and long-term care facilities. Growing awareness of malnutrition among vulnerable patient groups is supporting the use of enteral and parenteral nutrition solutions across the region.
Asia-Pacific
Asia-Pacific is expected to experience significant market growth due to expanding healthcare infrastructure, increasing healthcare expenditure, rising chronic disease prevalence, and a growing elderly population. China, Japan, India, South Korea, and other emerging economies are increasing their capacity for specialized medical care, creating additional demand for clinical nutrition products.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa are emerging markets for clinical nutrition as healthcare infrastructure improves and awareness of specialized nutritional care increases. Growing investments in hospitals, intensive care facilities, and home healthcare services are creating opportunities for enteral and parenteral nutrition providers.
Key Players Analysis
The clinical nutrition market is competitive, with leading companies focusing on specialized formulations, product innovation, nutritional delivery systems, and expansion of healthcare distribution networks. Key players include:
- Abbott Laboratories
- Nestlé S.A.
- Danone S.A.
- Fresenius SE & Co. KGaA
- B. Braun SE
- Baxter International Inc.
- Reckitt Benckiser Group plc
- Otsuka Pharmaceutical Co., Ltd.
- Ajinomoto Co., Inc.
- Meiji Holdings Co., Ltd.
These companies are focusing on condition-specific formulations, enteral and parenteral nutrition solutions, nutritional delivery technologies, and expanded healthcare distribution to address the growing demand for specialized nutritional support.
For Detailed Insights, Visit:
https://straitsresearch.com/report/clinical-nutrition-market
About Us
Straits Research is a leading market research and consulting organization providing industry reports, business intelligence, and strategic insights across a wide range of industries. Our research helps businesses understand market dynamics, emerging opportunities, competitive landscapes, and industry trends to support informed business decisions.
Contact Us
Email: [email protected]
Tel: +1 646 905 0080 (U.S.)
Tel: +44 203 695 0070 (U.K.)