Mexico Smart Grid Market Size, Trends, Demand and Forecast 2026-2034
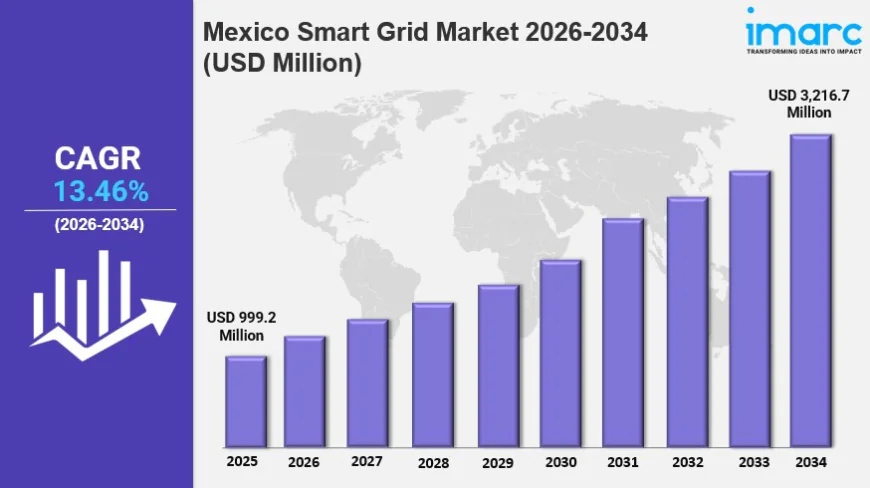
The Mexico smart grid market size reached USD 999.2 Million in 2025 and is projected to reach USD 3,216.7 Million by 2034, expanding at a CAGR of 13.46% during 2026-2034.
 marketinsights
IMARC Group has recently released a new research study titled "Mexico Smart Grid Market Report by Component (Software, Hardware, Services), End-User (Residential, Commercial, Industrial), and Region 2026-2034", offering a detailed analysis of the market drivers, segmentation, growth opportunities, trends, and competitive landscape to understand the current and future market scenarios.
Mexico Smart Grid Market Size & Share 2026-2034
The Mexico smart grid market size reached USD 999.2 Million in 2025 and is projected to reach USD 3,216.7 Million by 2034, expanding at a CAGR of 13.46% during 2026-2034. In 2026, the market continues to gain momentum, shaped by growing demand for renewable energy integration, rapid advancement of advanced metering infrastructure (AMI), and strong government mandates for grid modernization.
The market expanded from USD 531.5 Million in 2020 to USD 999.2 Million in 2025, driven by grid infrastructure upgrades, increased deployment of smart meters, and growing integration of distributed renewable energy resources. Growth in 2026 is further reinforced by industrial electrification and nearshoring demand and by expanding data centers and digital infrastructure. These dynamics are expected to strengthen the Mexico smart grid market share throughout the forecast period.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020-2025
- Forecast Period: 2026-2034
- Market Size (2025): USD 999.2 Million
- Projected Market Size (2034): USD 3,216.7 Million
- Growth Rate: CAGR of 13.46% (2026-2034)
- Leading Component (2025): Hardware, with a 46.8% share
- Leading End-User (2025): Residential, with a 44.9% share
- Leading Region (2025): Central Mexico, with a 42.6% share
Explore Opportunities in the Mexico Smart Grid Market: Download the IMARC Sample Report: https://www.imarcgroup.com/mexico-smart-grid-market/requestsample
Key Growth Drivers and Trends in the Mexico Smart Grid Market
Growth in the Mexico smart grid market is being driven primarily by grid modernization and infrastructure expansion. Ongoing investments in transmission networks, substations, and distribution infrastructure are strengthening grid reliability and creating sustained demand for smart grid hardware, software, and digital monitoring solutions.
Renewable energy integration requirements are another major driver. Growing national targets for clean energy generation require advanced grid infrastructure, including automation, storage coordination, and smart inverter technologies, to manage variable power from solar and wind sources. According to IMARC Group, the Mexico renewable energy market is set to reach 86.3 GW by 2034, at a CAGR of 9.03% during 2026-2034.
Industrial electrification and nearshoring demand is also supporting growth. The relocation of manufacturing operations is generating concentrated new electricity demand across industrial zones, accelerating adoption of power quality monitoring, automated fault detection, and real-time energy management platforms. Expanding data centers, telecommunications networks, and digital infrastructure further increase demand for stable, high-quality power supply.
One of the leading Mexico smart grid market trends is the mass deployment of AMI, as Mexico's national utility, CFE, progresses toward large-scale smart meter rollout, prioritizing urban residential zones and high-consumption commercial areas. Other trends include the integration of artificial intelligence (AI) and grid analytics for predictive maintenance, fault detection, and load forecasting; the growth of distributed energy resource management as rooftop solar, small-scale wind, and electric vehicle charging expand; and nearshoring-driven industrial grid modernization in border states such as Nuevo León, Chihuahua, and Coahuila.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=33447&flag=C
Mexico Smart Grid Industry Segmentation Insights
Breakup by Component:
- Hardware: The leading component, with a 46.8% share in 2025. Includes sensors, programmable logic controllers (PLCs), AMI meters, networking hardware, and others, driven by large-scale deployment of smart meters, sensors, distribution automation equipment, and communication infrastructure across CFE's network.
- Software: The second largest component, with a 34.7% share in 2025. Includes AMI, smart grid distribution management, smart grid network management, substation automation, and others, supported by adoption of energy management systems, meter data management platforms, and grid analytics, and growing faster than the overall market.
- Services: Includes consulting, support and maintenance, and deployment and integration services that support smart grid projects and ongoing operations.
Breakup by End-User:
- Residential: The leading end-user, with a 44.9% share in 2025, underpinned by mass smart meter rollout programs targeting household energy efficiency, accurate billing, and demand response, along with government electrification programs for underserved communities.
- Commercial: The second largest end-user, with a 30.6% share in 2025, reflecting adoption of building energy management systems, demand-side management tools, and smart metering in urban commercial sectors in Mexico City, Monterrey, and Guadalajara.
- Industrial: Industrial users adopting power quality monitoring, automated fault detection, and real-time energy management platforms, supported by nearshoring-led manufacturing expansion.
Breakup by Region:
- Central Mexico: The largest region, with a 42.6% share in 2025, anchored by Mexico City, the State of Mexico, Puebla, and Querétaro, with high population density, a large industrial and commercial base, and CFE's primary grid infrastructure.
- Northern Mexico: The second largest region, with a 30.2% share in 2025, driven by nearshoring-led industrial expansion in Nuevo León, Chihuahua, Coahuila, and Baja California, and by solar energy integration.
- Southern Mexico: A 16.4% share in 2025, supported by rural electrification programs, wind and geothermal integration in the Isthmus of Tehuantepec, and government infrastructure investment in underserved communities.
- Others: A 10.8% share in 2025, reflecting distributed energy adoption in tourist and coastal regions, emerging smart city initiatives, and grid reliability programs in secondary cities.
Key Challenges and Growth Opportunities in the Mexico Smart Grid Market
The Mexico smart grid market faces challenges including high capital expenditure requirements, regulatory uncertainty around tariffs, interconnection rights, and grid access, and cybersecurity vulnerabilities in connected grid infrastructure. Limited technical workforce and skill gaps, particularly outside major urban centers, and the difficulty of integrating modern platforms with fragmented legacy infrastructure can also slow deployment and raise costs.
Despite these challenges, the market offers considerable growth opportunities. Ongoing AMI expansion under government-driven metering upgrade programs creates a large addressable market for AMI hardware, communication modules, and meter data management software. Growing adoption of rooftop solar, small-scale storage, and electric vehicle charging also increases demand for grid edge and distributed energy resource management platforms. Software is the fastest-growing component, Northern Mexico is the fastest-growing region, and Southern Mexico is a significant emerging opportunity.
Competitive Landscape
The Mexico smart grid market is moderately concentrated, with a mix of global technology multinationals and specialized grid equipment providers competing for utility procurement contracts and industrial projects. Key players include Siemens, Schneider Electric, GE Vernova, and Honeywell International Inc., among others. Siemens (SIPROTEC 5), Schneider Electric (EcoStruxure Grid), and GE Vernova (Grid Solutions) hold leading positions, while Honeywell (Connexo) is positioned as a challenger focused on AMI network management. Barriers to entry include high capital requirements, the need for CFE certification, Spanish-language technical support, and Mexico's evolving regulatory framework. The IMARC report examines the competitive landscape along with profiles of the key players.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: [email protected]
United States: +1-201-971-6302