Logistics Software Market Size, Share, Regional Insights & Industry Forecast 2034
Challenges in the Logistics Software Market 1. Limited Standardization Across Logistics Networks Logistics operations involve multiple carriers, suppliers, warehouses, and technology systems that may use different data formats and communication standards.
 manish chaudhari
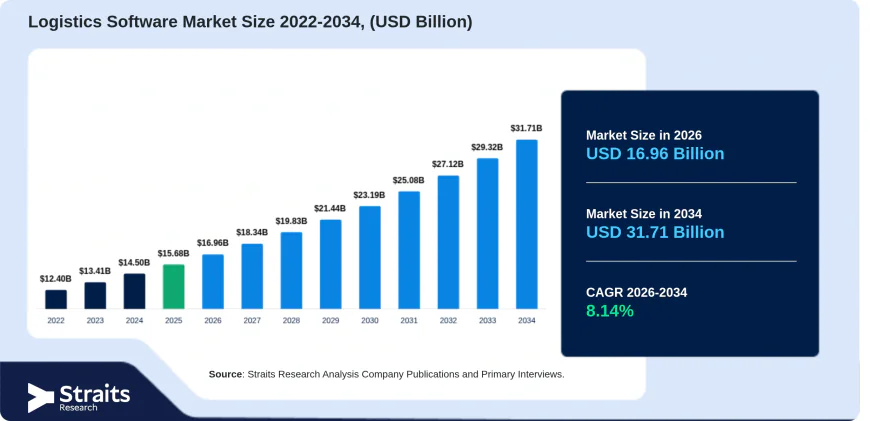
The global logistics software market size was valued at USD 15.68 billion in 2025 and is projected to grow from USD 16.96 billion in 2026 to USD 31.71 billion by 2034, registering a CAGR of 8.14% during the forecast period (2026–2034). North America dominated the logistics software market with a share of 36.5% in 2025. The market is expanding as businesses adopt digital solutions to improve transportation planning, warehouse operations, inventory management, shipment tracking, and supply chain visibility. Growing logistics complexity and demand for faster, more reliable deliveries are increasing the importance of integrated software platforms.
Key Trends in the Logistics Software Market
1. Integration of Artificial Intelligence and Predictive Analytics
Artificial intelligence and predictive analytics are becoming important features of logistics software. These technologies help businesses forecast demand, estimate delivery times, identify potential disruptions, and optimize transportation routes. Data-driven planning can improve resource utilization and support faster responses to changing shipment conditions.
2. Growing Adoption of Cloud-Based Logistics Platforms
Cloud-based logistics software enables businesses to access shipment, inventory, and transportation information across multiple locations. These platforms support collaboration among manufacturers, suppliers, warehouses, carriers, and retailers without requiring every organization to maintain extensive on-premises infrastructure. Flexible deployment and real-time data sharing are encouraging adoption among businesses seeking scalable logistics operations.
Growth Drivers of the Logistics Software Market
1. Expansion of E-Commerce and Omnichannel Retail
The expansion of e-commerce is increasing the volume and complexity of deliveries, returns, and order fulfillment. Logistics software helps retailers and logistics providers coordinate shipments, manage inventory across distribution centers, and improve delivery visibility. Demand for accurate order tracking and timely fulfillment is supporting investment in transportation management, warehouse management, and order management solutions.
2. Increasing Need for Supply Chain Visibility and Efficiency
Businesses are investing in logistics software to gain better visibility into shipments, inventory levels, delivery schedules, and transportation costs. Centralized platforms help logistics teams identify delays, coordinate carriers, and respond to disruptions before they significantly affect operations. The need to reduce operating expenses and improve delivery reliability is supporting software adoption across manufacturing, retail, healthcare, and other industries.
Market Opportunities in the Logistics Software Market
1. Adoption of Automation in Warehousing and Distribution
Automated warehouses and distribution centers create opportunities for logistics software providers offering warehouse management, labor planning, and inventory optimization tools. Integration with robotics, barcode scanners, and automated material-handling systems can improve order accuracy and processing speed. Software vendors can expand their offerings by providing platforms that connect warehouse equipment with broader transportation and supply chain systems.
2. Growth Opportunities Among Small and Medium-Sized Enterprises
Small and medium-sized businesses increasingly need affordable tools to manage shipments, inventory, delivery schedules, and carrier relationships. Subscription-based cloud platforms can reduce the need for large upfront investments in software infrastructure. Providers that offer easy implementation, flexible pricing, and integrations with e-commerce and accounting systems can reach a broader customer base.
Restraints in the Logistics Software Market
1. High Implementation and Integration Costs
Logistics software implementation can require substantial investment in licensing, customization, employee training, and system integration. Businesses with complex supply chains may also need to connect new platforms with legacy enterprise resource planning systems, warehouse tools, and carrier networks. These expenses can delay adoption, particularly among smaller organizations with limited technology budgets.
2. Data Security and Privacy Concerns
Logistics platforms process sensitive information related to customers, shipments, suppliers, inventory, and commercial transactions. Unauthorized access or data breaches can expose business information and disrupt operational processes. Companies must invest in access controls, encryption, monitoring, and data governance, increasing the resources required to maintain secure systems.
Challenges in the Logistics Software Market
1. Limited Standardization Across Logistics Networks
Logistics operations involve multiple carriers, suppliers, warehouses, and technology systems that may use different data formats and communication standards. Inconsistent information can create delays in shipment updates, tracking, and operational reporting. Software providers must support reliable data exchange across diverse systems to deliver accurate and consistent supply chain visibility.
2. Workforce Training and Change Management
The introduction of new logistics software can require employees to change established workflows and learn unfamiliar digital tools. Resistance to new processes, limited technical skills, and inadequate training can reduce adoption and delay expected productivity improvements. Vendors and logistics operators must provide effective onboarding and ongoing support to ensure that software investments deliver operational value.
Logistics Software Market Segmentation Analysis
The logistics software market includes solutions for transportation management, warehouse management, inventory management, order management, fleet management, and supply chain visibility. Transportation management systems help businesses plan routes, coordinate carriers, and control freight costs, while warehouse management systems support inventory accuracy, storage planning, and order fulfillment.
Deployment options generally include cloud-based and on-premises solutions. Cloud platforms offer scalability and remote access, while on-premises systems may appeal to organizations seeking greater control over their infrastructure and data environment. End users include third-party logistics providers, retailers, manufacturers, wholesalers, and other businesses that manage complex distribution and transportation activities.
Regional Outlook for the Logistics Software Market
North America dominated the logistics software market with a 36.5% share in 2025. The region benefits from established logistics networks, advanced digital infrastructure, and widespread adoption of e-commerce and supply chain technologies. Businesses across retail, manufacturing, transportation, and third-party logistics continue to use software to improve delivery performance and operational visibility.
Europe represents an important market due to cross-border trade, established transportation networks, and demand for more efficient distribution operations. Asia Pacific offers growth potential through expanding e-commerce activity, manufacturing networks, and investment in logistics infrastructure. Adoption across emerging markets will depend on digital readiness, implementation costs, and the availability of software that supports local logistics requirements.
Competitive Landscape of the Logistics Software Market
The logistics software market includes enterprise software vendors, specialized logistics technology providers, cloud platform companies, and supply chain solution developers. Competition focuses on functionality, ease of integration, real-time tracking, analytics, scalability, cybersecurity, and compatibility with existing enterprise systems. Established providers benefit from broad product portfolios and relationships with large organizations, while specialized vendors compete through focused capabilities for transportation, warehousing, fleet management, and shipment visibility. Partnerships with carriers, e-commerce platforms, and enterprise software providers also help expand integration capabilities and strengthen offerings across the market ecosystem.
Recent Developments in the Logistics Software Market
Product development in the logistics software market continues to emphasize artificial intelligence, cloud deployment, automation, and real-time visibility. Providers are enhancing route optimization, predictive planning, warehouse workflows, and shipment tracking to help customers manage increasingly complex operations. Greater integration between logistics platforms and enterprise systems is also supporting more coordinated planning across procurement, inventory, transportation, and fulfillment.
Future Outlook of the Logistics Software Market
The logistics software market is expected to expand through 2034 as businesses prioritize supply chain visibility, efficient transportation, and faster order fulfillment. Artificial intelligence, cloud platforms, warehouse automation, and predictive analytics are likely to remain important areas of development. However, implementation costs, data security, interoperability, and workforce training will continue to influence adoption. Providers offering scalable, secure, and easily integrated solutions are positioned to address the changing requirements of logistics operators and businesses across industries.
For More Information
Explore the full report for additional market insights, segmentation, and industry analysis: https://straitsresearch.com/report/logistics-software-market