India Spices Market 2026–2034: Packaged Seasonings, Culinary Innovation, Export Opportunities & Growth Prospects
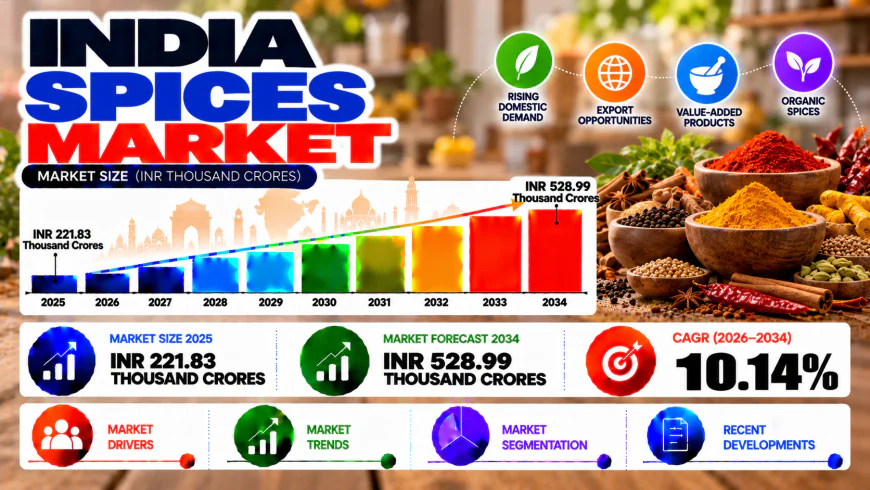
India spices market size was valued at INR 221.83 Thousand Crores in 2025, projected to reach INR 528.99 Thousand Crores by 2034 at 10.14% CAGR
 chetan kalyan
India Spices Market Outlook
The market is anchored by deeply rooted culinary traditions, rising demand for organic and clean-label products, a fast-growing food processing sector, and the rapid rise of e-commerce and quick commerce. The spice industry in India is the world’s largest producer, consumer, and exporter, accounting for more than 70% of global spice exports and growing over 75 varieties across diverse agro-climatic zones.
The market is moving from loose, unbranded sales toward hygienic, traceable, packaged formats, while premium organic, GI-tagged, and ready-to-cook products are creating new value tiers. This transition is reshaping how households, food processors, and exporters buy and use spices.
Market Snapshot
- Market Size (2025): INR 221.83 Thousand Crores
- Forecast Market Size (2034): INR 528.99 Thousand Crores
- CAGR (2026-2034): 10.14%
- Leading Product Type: Pure Spices, 63% share (2025)
- Leading Form: Packets, 67.0% share (2025)
- Leading Application: Veg Curries, 29.0% share (2025)
- Leading Region: North India, 30.0% share (2025)
- Fastest Growing Region: West and Central India
- Key Growth Drivers: Culinary heritage, organic demand, food processing growth, e-commerce, export support
Executive Summary
The spices market size in India was INR 221.83 Thousand Crores in 2025 and is projected to reach INR 528.99 Thousand Crores by 2034 at a CAGR of 10.14%. India cultivates approximately 75 of the 109 ISO-listed spice varieties. Pure spices lead with a 63% share, driven by household purchases of turmeric, red chilli, coriander, cumin, and pepper, while blended and ready-to-cook masalas grow quickly among convenience-seeking urban consumers.
Packets hold 67.0% of the market by form as consumers leave loose spices behind, and veg curries lead applications at 29.0%. The market is highly fragmented: national brands such as Everest, MDH, ITC’s Aashirvaad, Catch, and Badshah collectively account for less than 30% of revenue, and the organized market is beginning a gradual consolidation led by premium and organic segments.
India Spices Market Key Drivers
- Culinary Heritage and Household Demand:
Spices are non-discretionary essentials across India’s 300+ million households. Regional cuisines, from spice-rich southern curries to aromatic northern dishes, need a steady supply of many varieties.
- Rising Health Consciousness and Organic Demand:
The medicinal reputation of Indian spices is driving demand for premium, additive-free products. An ASSOCHAM survey reported 95% growth in urban organic produce purchases, with 62% of metropolitan consumers buying organic products, including spices.
- Expansion of the Food Processing Industry:
As of February 28, 2025, the Ministry of Food Processing Industries had approved 1,608 projects under PMKSY, including 41 Mega Food Parks, 394 Cold Chain projects, 75 Agro-processing Clusters, and 536 Food Processing Units, building steady institutional demand for spice ingredients.
- E-Commerce and Quick Commerce Growth:
India’s e-commerce industry, valued at INR 10,82,875 crore (USD 125 billion) in 2024, is expected to reach INR 29,88,735 crore (USD 345 billion) by 2030, a CAGR of 15%, widening access to branded and specialty spices.
- Government Export Promotion and Infrastructure Support:
The Spices Board of India’s SPICED scheme, with an outlay of INR 422.30 Crore through FY 2025-26, supports export promotion, quality upgradation, and processing infrastructure. Schemes such as PM-FME and One District One Product help micro food processors and local spice clusters formalize and scale.
Evaluate Market Opportunity with the Business Sample Report
India Spices Market Emerging Trends
- Organic and Clean-Label Spices:
Urban consumers who prioritize ingredient transparency are willing to pay 15-25% premiums for certified organic products. Organic and clean-label spices are the fastest-growing segment, at a CAGR of roughly 13.5% through 2034.
- Ready-to-Cook Blends and Convenience Formats:
Convenience-oriented formats are attracting established FMCG companies and digital-native brands alike, with a CAGR of roughly 12.1%, particularly among urban consumers aged 22-40.
- Digital and Quick-Commerce Transformation:
E-commerce and quick commerce is the fastest-growing channel at roughly 14.8% CAGR. Delivery in 10-15 minutes drives impulse purchases and widens the audience for premium and specialty spices.
- Premiumization, GI Tags, and Specialty Spices:
GI-tagged spices such as Byadgi chilli, Lakadong turmeric, and Malabar pepper command 2-4x price premiums over generic equivalents, and brands are building premium ranges around origin and quality.
India Spices Market Challenges
Despite robust momentum, the spice industry in India faces persistent headwinds:
- Erratic monsoons, unseasonal frosts, and droughts can devastate yields, tighten supply, and cause sharp price spikes
- Food safety incidents, including pesticide residue concerns in exported spices, have prompted tighter FSSAI and international scrutiny and raised compliance burdens
- A fragmented, largely unorganized supply chain of small traders, regional brands, and loose-spice vendors limits uniform quality
- Price volatility in key spices, such as jeera surpassing INR 60,000 per 100 kilograms at Unjha, and rising export competition from China, Vietnam, and Indonesia in categories such as pepper, star anise, and ginger
Explore the Full Report with Charts, Table of Contents, and List of Figures
India Spices Market Segment Insights
By Product Type
- Pure Spices: 63% (chilli, turmeric, coriander, cumin, pepper, cardamom, clove, cinnamon, and others)
- Blended Spices: garam masala, kitchen king, chat masala, pav bhaji masala, and other blends
By Application
- Veg Curries: 29.0%
- Meat and Poultry Products: 19.4%
- Snacks and Convenience Foods
- Soups, Sauces, and Dressings
- Bakery and Confectionery, Frozen Foods, Beverages, and Others
By Form
- Packets: 67.0% (hygienic, branded, portion-controlled)
- Sprinkler: 19.4% (direct-application convenience in food service)
- Crusher: 13.6% (freshly crushed premium spices)
Regional Insights
- North India: Share (2025): 30.0%
- South India: Share (2025): 29.0%
- West and Central India: Share (2025): 24.0%
- East India: Share (2025): 17.0%
Competitive Landscape
The spices market in India is highly fragmented, with national FMCG brands, strong regional players, private-label offerings, and a large base of unorganized manufacturers. Brand awareness and organized shelf space sit with a handful of leaders, while ZOFF Foods’ digital scale-up shows how technology-native brands can win share without traditional distribution.
- Everest Food Products Pvt. Ltd., Brand / Platform: Everest Masala, Tikhalal
Core Strength: Broadest national distribution and 52+ blended masala variants
- Mahashian Di Hatti (MDH), Brand / Platform: MDH Masala, Chunky Chat, Kitchen King
Core Strength: Premium North Indian masala with decades of brand equity
- ITC Ltd., Brand / Platform: Aashirvaad Spices, 24 Mantra Organic
Core Strength: Organic expansion across premium and mass segments
- DS Group, Brand / Platform: Catch Masala, Catch Salt
Core Strength: Innovative sprinkler and seasoning formats; impulse and food service focus
- Orkla India / MTR Foods, Brand / Platform: MTR Masala, Ready Mixes
Core Strength: South India leadership and ready-to-cook integration
Recent Developments
- June 2025: ITC completed its INR 472.50 Crore acquisition of Sresta Natural Bioproducts (24 Mantra Organic), expanding its organic spices portfolio for domestic premium retail and exports
- June 2025: ZOFF Foods partnered with Reliance Retail to launch its Quick Homestyle Food range, including 5-Minute Gravies and 1-Minute Marinades, across 400+ stores
- October 2025: ZOFF Foods reported that 75% of its revenue comes from online retail, with 65% from quick-commerce platforms
- 2025: Gujarat’s Mehsana district exported cumin, fennel, and Isabgol worth INR 3,995 Crore, underlining export strength
Investment Opportunities
- High-Growth Segments: Ready-to-cook blends, organic and clean-label spices, and e-commerce and quick-commerce channels are the fastest-growing areas, and ZOFF Foods’ INR 170 Crore revenue target shows the scale possible in convenience spices.
- Geographic Expansion: East India holds only a 17.0% share despite its population, and rapid e-commerce adoption in Patna, Bhubaneswar, and Guwahati, with modern trade growth in Kolkata, creates openings for branded manufacturers.
- Venture & Strategic Investment: Public infrastructure under the SPICED scheme and Mega Food Parks is mobilizing private capital, while digital-native brands attract venture funding on e-commerce-first models.
Discuss Your Requirements With an Analyst and Get Your Customized Market Report
Frequently Asked Questions (FAQ)
- What is the spices market size in India in 2025?
India spices market was valued at INR 221.83 Thousand Crores in 2025, driven by culinary heritage, organic demand, and e-commerce growth.
- What is the projected market size by 2034?
The market is projected to reach INR 528.99 Thousand Crores by 2034, growing at a CAGR of 10.14% during 2026-2034.
- Which form segment leads?
Packets lead with a 67.0% share in 2025, reflecting a shift toward hygienic, tamper-proof, portion-controlled packaging with standardized quality.
- Which region dominates?
North India leads with a 30.0% share in 2025, supported by spice-intensive cuisines, high household consumption, and strong export demand.
- Who are the leading companies?
Everest Food Products, MDH, ITC (Aashirvaad and 24 Mantra Organic), DS Group (Catch Foods), Badshah Masala, Orkla India (MTR Foods), Patanjali Ayurved, Aachi Masala Foods, and Goldiee Group.
Conclusion
The India spices market is a standout opportunity in food and agribusiness, supported by non-discretionary household demand, expanding food processing, export leadership, and fast-growing digital channels. Premiumization through organic, GI-tagged, and specialty products will define value creation through 2034.
Three forces will shape the market: packaged, branded spices replacing loose sales; e-commerce and quick commerce bringing premium spices to smaller cities; and ready-to-cook blends opening new demand. Companies that invest in quality, traceability, and distribution reach will capture disproportionate value. Request a sample of the IMARC Group report to explore the data behind these shifts.
Source: IMARC Group