Europe Telehealth Market 2026 | Worth USD 25.98 billion by 2034
Europe's telehealth market is set to grow from USD 6.62B to USD 25.98B by 2034. Explore AI integration, cloud infrastructure, and opportunities.
 Ranjeet Sharma
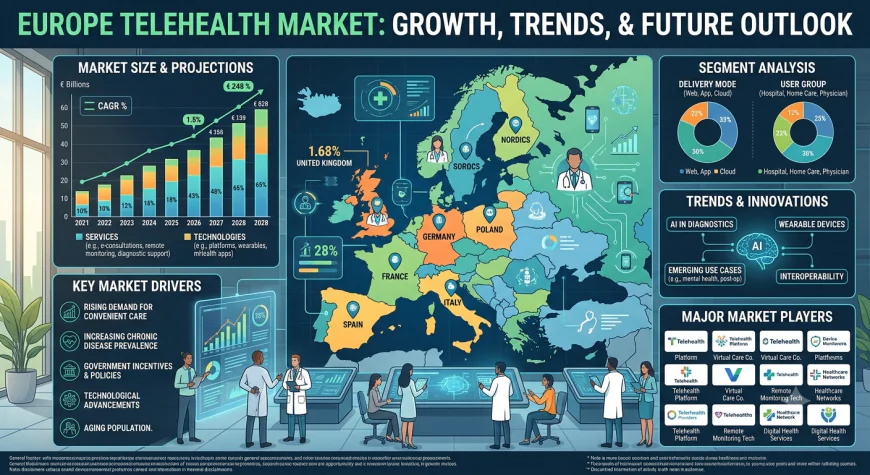
European healthcare executives are confronting a paradox of progress. The continent boasts some of the world's most advanced medical systems, yet patients in rural areas still wait weeks for specialist appointments, hospitals struggle with workforce shortages, and chronic disease management consumes an ever-growing share of health budgets. The pandemic proved that virtual care could work at scale—but sustaining that momentum requires more than temporary emergency measures. The Europe telehealth market sits at the centre of this transformation. Valued at USD 6.62 billion in 2025, the market is projected to reach USD 25.98 billion by 2034, growing at a compound annual growth rate of 16.4 per cent from 2026 to 2034. These figures reflect an industry moving from crisis response to permanent healthcare infrastructure.
What's Driving Growth of Europe's Telehealth Market?
Supportive government policies and regulatory frameworks are creating favourable conditions for adoption. European governments are implementing comprehensive digital health strategies that establish reimbursement mechanisms, technical standards, and legal frameworks enabling healthcare providers to deliver and bill for virtual care services. The European Health Data Space regulation, which came into force in March 2025, is enabling seamless electronic health data sharing for care and research across EU member states.
Aging populations and rising chronic disease prevalence are expanding demand for remote care. Europe's demographic profile is characterised by rapidly aging populations requiring increased healthcare services, particularly for chronic condition management. Remote monitoring platforms enable providers to track vital signs, medication adherence, and disease progression without requiring frequent in-person visits, addressing the needs of older adults who may face mobility challenges or live in areas with limited healthcare facility access.
Technological advancements in digital health infrastructure are enhancing capabilities. Rapid progress in artificial intelligence, wearable devices, and cloud computing is enhancing the capabilities and accessibility of telehealth solutions. Advanced algorithms enable real-time analysis of patient data, predictive health modelling, and automated clinical decision support. Wearable technology integration allows continuous health monitoring outside clinical settings, generating valuable data streams for personalised care management.
Workforce shortages and cost pressures are compelling digital adoption. Healthcare organisations face persistent challenges in recruiting and retaining clinical staff, particularly in specialised disciplines and rural areas. Telehealth solutions enable providers to extend specialist expertise across geographies, optimise resource utilisation, and reduce hospital admissions through remote monitoring, addressing both workforce constraints and cost efficiency imperatives.
Three Trends Reshaping the Industry
AI integration is transforming reactive care into predictive health management.
Healthcare providers across Europe are increasingly integrating artificial intelligence capabilities into telehealth platforms to enhance diagnostic accuracy and streamline clinical workflows. AI-powered tools enable real-time analysis of patient data from wearable devices, supporting early detection of health deteriorations and facilitating proactive interventions. In November 2024, Hamburg-based TCC raised €20 million in Series A funding to enhance intensive care unit support through AI-enabled telehealth solutions, currently managing over three thousand hospital beds globally.
Why it matters: AI transforms telehealth from a convenience channel into a clinical decision-support tool capable of improving outcomes.
Business implication: Platform providers must invest in AI capabilities or risk commoditisation as basic video consultation becomes standardised.
Future impact: Predictive health management will become the primary value proposition for telehealth platforms, shifting reimbursement toward outcomes rather than consultations.
Cloud-based infrastructure is becoming the default deployment model.
The migration toward cloud-based telehealth platforms is accelerating across European healthcare systems, driven by the need for scalable, interoperable, and cost-efficient digital infrastructure. Cloud solutions enable seamless integration with electronic health records and facilitate secure data sharing across disparate healthcare settings. Philips announced in February 2025 that its cloud-based HealthSuite Imaging technology would be extended to Europe, providing radiology departments with safe remote access to AI-enabled processes and imaging tests via Amazon Web Services.
Why it matters: Cloud infrastructure enables healthcare organisations to deploy advanced virtual care capabilities without substantial capital investments.
Business implication: On-premises vendors must transition to cloud-native architectures or face displacement by more agile competitors.
Future impact: Cloud-based platforms will enable cross-border telehealth services, allowing patients to access specialists anywhere in the EU.
Mental health teleconsultation is emerging as a major service category.
Telepsychiatry and mental health teleconsultation services are witnessing significant adoption growth across European markets as awareness of mental wellness increases and stigma surrounding virtual therapy diminishes. Digital platforms are providing accessible pathways for individuals to receive counselling, therapy, and psychiatric care regardless of geographic location. Telepsychiatry has emerged as one of the most utilised telehealth services across the region, with numerous countries integrating mental health teleconsultation within broader digital health frameworks.
Why it matters: Mental health represents a high-demand, recurring service category that benefits disproportionately from virtual delivery.
Business implication: Telehealth providers must develop specialised mental health offerings or risk losing share to dedicated platforms.
Future impact: Mental health teleconsultation will become a standard component of national healthcare systems across Europe.
What the Market Numbers Actually Tell Us
A market expanding from USD 6.62 billion to USD 25.98 billion over nine years suggests transformative commercial activity across software providers, hardware manufacturers, service operators, and healthcare institutions. The 16.4 per cent compound annual growth rate signals one of the fastest-growing segments in European healthcare. Software dominates the component segment at 56 per cent, driven by accelerating adoption of cloud-native platforms and interoperable electronic health record integrations. Video conferencing leads communication technology at 43 per cent, enabling real-time clinical consultations. Cloud-based and web-based hosting exhibits clear dominance at 68 per cent, indicating strong preference for scalable, adaptable infrastructure. Teleconsultation and telementoring represent the largest application segment at 23 per cent. Providers prevail as end users at 43 per cent, integrating telehealth into hospital networks and primary care practices. The United Kingdom leads the regional market with 32 per cent share, driven by the NHS's strategic embrace of digital transformation.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of AI, interoperability, and cross-border care. The European Health Data Space regulation creates a framework for seamless data sharing across member states, enabling telehealth providers to offer services across borders. In March 2024, the UK government announced £3.4 billion investment in NHS digitisation, doubling investment in digital transformation to harness AI capabilities. In April 2025, the UK announced up to £600 million investment for a centralised Health Data Research Service designed to streamline NHS data access for researchers. National frameworks across multiple European markets are encouraging widespread adoption of standardised telehealth software systems, promoting interoperability and data sharing across care settings. Companies that can navigate the complex regulatory landscape, invest in AI-powered clinical decision support, and develop interoperable platforms are well-positioned to capture value in this rapidly evolving market. Key players are expanding digital care portfolios, enhancing platform interoperability, and investing in AI-powered diagnostic capabilities, with strategic partnerships with national health systems accelerating adoption across diverse healthcare settings.