Europe Online Grocery Market Size, Share, Report 2026-2034
Europe's online grocery market is set to grow from USD 81.8B to USD 506.9B by 2034. Explore quick commerce, subscription models, and opportunities.
 Ranjeet Sharma
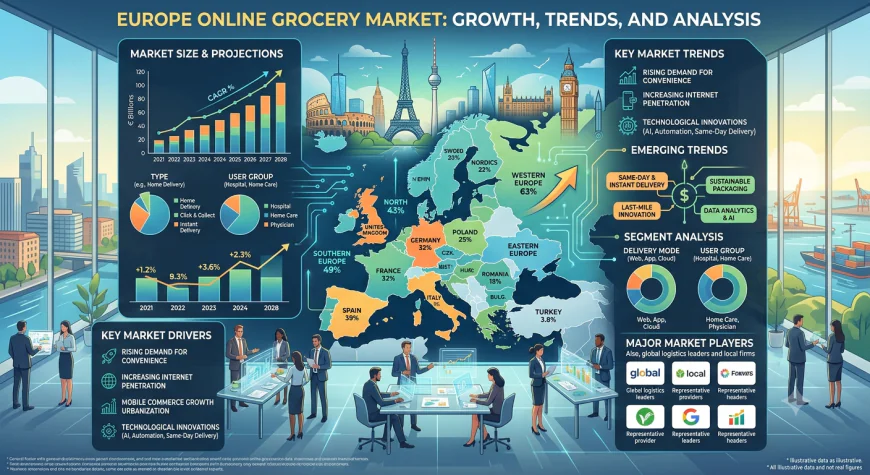
European grocery retailers are confronting a transformation that would have seemed implausible just five years ago. The pandemic accelerated online grocery adoption from a niche convenience into a mainstream expectation, and consumers who discovered the ease of doorstep delivery have proven reluctant to return to weekly supermarket trips. Yet the economics of online grocery remain brutally challenging—thin margins, complex cold-chain logistics, and the "last mile" problem that has defeated many well-funded entrants. The Europe online grocery market sits at the centre of this high-stakes evolution. Growing from USD 81.81 billion in 2025 to USD 100.20 billion in 2026, the market is projected to reach USD 506.88 billion by 2034, exhibiting a compound annual growth rate of 22.46 per cent during 2026-2034. These figures reflect an industry experiencing one of the fastest transformations in European retail history.
What's Driving Growth of Europe's Online Grocery Market?
Post-COVID digital grocery habit formation has proven permanent rather than temporary. A PwC study indicated that 22 per cent of German consumers use the internet as their main grocery shopping channel. Around 52 per cent increased their online grocery purchases during the COVID-19 pandemic, and over 82 per cent plan to continue buying groceries online going forward. This behavioural shift has created a structural increase in demand rather than a temporary spike.
Smartphone app and mobile commerce explosion is reshaping shopping behaviour. By 2030, Europe is projected to have 527 million unique mobile subscribers, accounting for an 89 per cent penetration rate across the region. Europeans spend an average 4.8 hours daily on their smartphones, with grocery apps accessible at any moment. App-based platforms dominate at 68.08 per cent market share, reflecting the smartphone's primacy as Europe's primary digital commerce interface.
Quick commerce is redefining convenience standards across European cities. Ten to fifteen-minute grocery delivery, virtually non-existent in Europe before 2020, has reshaped consumer expectations of delivery speed. Berlin has emerged as the capital of European quick commerce, hosting the headquarters of Gorillas, Flink, and Knuspr, and this concentration of venture-backed investment has fundamentally shifted German consumer expectations.
Urbanisation and dual-income time poverty are concentrating demand. The urban population in the European Union was reported at 75.95 per cent in 2024, concentrating consumers in dense urban environments where online grocery delivery is operationally efficient and highly time-competitive versus in-store shopping. Europe's level of urbanisation is expected to increase to approximately 83.7 per cent in 2050.
Three Trends Reshaping the Industry
Automated micro-fulfilment centres are transforming online grocery economics.
Automated micro-fulfilment centres are processing grocery orders at five to eight times the speed of manual picking at 30-40 per cent lower operating cost. Ocado's Luton customer fulfilment centre became the fastest-ramping fulfilment centre, reaching approximately 40,000 orders per week within its first four weeks of operation. At full capacity, the facility is expected to handle up to 65,000 orders weekly. These automated systems are the physical infrastructure enabling online grocery economics to improve sufficiently for profitable delivery at competitive consumer prices.
Why it matters: Automation is the prerequisite for sustainable online grocery market share growth beyond the penetration ceiling that expensive manual fulfilment would otherwise impose.
Business implication: Retailers must invest in automated fulfilment infrastructure or concede the online channel to more efficient competitors.
Future impact: Online penetration will accelerate as delivery economics approach parity with in-store shopping.
Subscription-first models are building customer lifetime value.
European grocery subscription models—unlimited free deliveries, exclusive member pricing, early access to promotions, and personalised loyalty rewards—are becoming primary customer retention strategies for all major platforms. Subscription is the fastest-growing segment at approximately 27.4 per cent CAGR, more than double the overall market rate. The economics are compelling for both platforms and consumers: subscribers generate four to six times the annual gross merchandise value of non-subscribers, while consumers with unlimited free delivery subscriptions order 3.5 times more frequently than pay-per-delivery customers.
Why it matters: Subscription transforms occasional online grocery buyers into habitual digital shoppers with dramatically higher lifetime value.
Business implication: Platforms must develop compelling subscription propositions or risk losing their most valuable customers to competitors.
Future impact: Subscription will become the dominant purchase model, displacing one-time transactions as the primary revenue driver.
Sustainability and zero-waste grocery are creating a premium market segment.
European consumer demand for sustainable online grocery options—zero-plastic packaging, verified organic provenance, reduced food waste algorithms, and carbon-neutral delivery—is creating a new premium market segment. Platforms are responding with electric delivery fleets, recyclable packaging, and supply chain transparency initiatives that appeal to environmentally conscious consumers willing to pay premium prices for verified sustainability credentials.
Why it matters: Sustainability credentials are becoming a competitive differentiator in a market where price competition is intense.
Business implication: Platforms must invest in sustainable delivery infrastructure and transparent sourcing to capture premium customer segments.
Future impact: Carbon-neutral delivery will become a standard expectation rather than a premium differentiator.
What the Market Numbers Actually Tell Us
A market expanding from USD 81.81 billion to USD 506.88 billion over nine years suggests transformative commercial activity across grocery retailers, quick commerce platforms, technology providers, and logistics operators. The 22.46 per cent compound annual growth rate signals one of the fastest-growing segments in European retail. Vegetables and fruits represent the largest product segment at 32 per cent, while hybrid marketplace business models lead at 53 per cent. One-time purchases dominate at 83 per cent, though subscription is growing at more than double the overall market rate. Germany commands the largest country share at 26 per cent, driven by Rewe and Edeka's digital transformation and Berlin's quick commerce ecosystem. The United Kingdom follows at 22.4 per cent, representing Europe's most mature online grocery market, while France at 18.3 per cent is uniquely defined by the Drive click-and-collect model. Italy is the fastest-growing country at approximately 23.2 per cent CAGR from a low base. For investors and industry participants, this trajectory indicates that online grocery is transitioning from a supplementary channel to the dominant mode of grocery shopping in many urban markets.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of automation, subscription, and underpenetrated markets. Dark store automation capital expenditure represents a high-return investment vector, enabling profitable delivery at competitive prices. Grocery subscription platforms are attracting venture and growth equity investment as investors recognise the superior unit economics of recurring revenue models. Italy's online grocery market, growing at approximately 25.8 per cent from a 3.2 per cent penetration base, represents the highest absolute incremental market opportunity among the five major European markets, with an estimated USD 35-45 billion in incremental annual gross merchandise value achievable by 2034. Central and Eastern European markets, including Poland, Czech Republic, Hungary, Romania, and Bulgaria, represent the highest-growth frontier, with online grocery penetration below 2 per cent in most countries. In March 2026, Flink secured USD 100 million in fresh funding from Prosus Ventures and Btomorrow Ventures, valuing the Berlin-based grocery delivery startup at USD 900 million. Companies that can navigate the complex logistics of grocery fulfilment, invest in automation technology, and develop subscription models are well-positioned to capture value in this rapidly evolving market.