Europe Compound Feed Market: Why Insect Protein and Blockchain Are Rewriting the Rules of Animal Nutrition
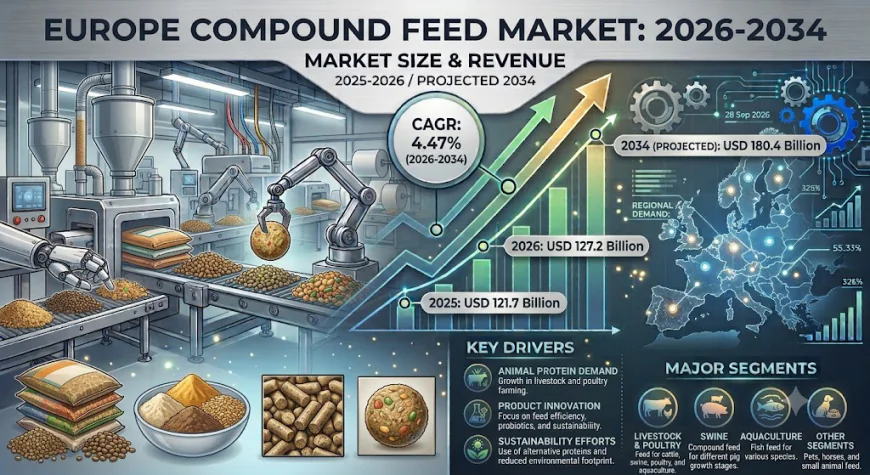
Europe compound feed market increased from USD 121.7 Billion in 2025 to USD 127.2 Billion in 2026 and is expected to reach USD 180.4 Billion by 2034, growing at a CAGR of 4.47% during 2026–2034.
 Team Imarc
There is a quiet revolution happening in the facilities that produce the feed sustaining Europe's livestock and aquaculture industries. Alongside the familiar grain silos, oilseed processing lines, and fishmeal handling systems, new infrastructure is appearing insect rearing chambers, algae cultivation vessels, precision fermentation bioreactors, and blockchain-connected traceability terminals that can track every ingredient in a feed batch from field to farm in real time. The Europe compound feed market is not simply growing it is undergoing a fundamental reimagining of what animal nutrition looks like when environmental sustainability, food system transparency, and precision science converge simultaneously in one of the continent's largest agricultural sectors.
The market numbers capture that transformation at commercial scale. The Europe compound feed market increased from USD 121.7 Billion in 2025 to USD 127.2 Billion in 2026 and is expected to reach USD 180.4 Billion by 2034, growing at a CAGR of 4.47% during 2026–2034. EU feed production reached a total of 147 million tons in December 2024, with FEFAC projecting industrial compound feed output to rise by 0.50% when accounting for the economic, regulatory, environmental, and animal health factors operating across livestock sectors simultaneously. A market of this scale growing at 4.47% annually is adding billions of euros in incremental value each year driven not by increasing European meat consumption alone, but by the compounding investment in ingredient innovation, production technology, and supply chain transparency that is reshaping how compound feed is formulated, manufactured, and certified across the region.
What's Driving Growth in the Europe Compound Feed Market?
- The European Green Deal and Farm to Fork strategy creating policy-driven ingredient transformation are the most commercially consequential regulatory forces reshaping the market's long-term trajectory. These frameworks targeting carbon emission reductions, biodiversity enhancement, and reduced dependency on imported protein ingredients — are compelling feed manufacturers to redirect R&D investment away from conventional animal protein sources toward plant proteins, insect-derived ingredients, and novel fermentation-based alternatives that align with both environmental objectives and the sustainability procurement criteria increasingly applied by European food retailers and processors across their livestock supply chains.
- Total EU industrial compound feed output reaching 147 million tons in 2024 provides the foundational scale context within which the market's growth trajectory should be understood. That volume distributed across poultry, swine, ruminant, and aquaculture applications represents the physical throughput of an industry whose ingredient procurement, logistics, and manufacturing infrastructure is deeply integrated with European grain markets, oilseed crush capacity, and international fishmeal trade flows that collectively determine the input cost environment within which every compound feed manufacturer operates.
- Grains and cereals maintaining their position as the foundational ingredient category reflects the biological reality that energy provision remains the primary nutritional function of compound feed across every animal species with wheat, maize, and barley providing the caloric substrate on which protein, vitamin, mineral, and specialty ingredient additions are layered. The stability of this ingredient category provides the demand floor that sustains European grain farming profitability and anchors the commodity trading relationships that link European feed manufacturers to both domestic agricultural production and international import supply chains.
- Poultry and swine sectors driving the highest volume compound feed demand reflects the protein consumption patterns of European households where poultry and pork remain the dominant meat categories by volume creating consistent, large-scale demand for the broiler, layer, and pig starter, grower, and finisher feeds that compound feed manufacturers produce at industrial scale across dedicated production facilities optimised for the precise nutritional specifications each growth stage requires.
- Aquaculture sector growth expanding the addressable market beyond terrestrial livestock as European consumers shift protein consumption toward fish and seafood categories perceived as healthier and more sustainable than red meat. The aquaculture segment's compound feed requirements particularly the progressive substitution of wild-capture fishmeal with alternative protein sources including insect meal, algae, and processed animal proteins represent one of the most technically demanding and commercially dynamic ingredient innovation frontiers in the entire European compound feed industry.
Three Trends Reshaping the Industry
Alternative protein ingredients transitioning from regulatory ambition to commercial production at scale
The shift away from conventional fishmeal and meat-and-bone meal toward insect protein, algae-derived meal, and single-cell protein derived from precision fermentation has moved decisively from pilot programme to committed commercial investment across Europe driven simultaneously by regulatory frameworks that have progressively expanded the approved uses of processed animal proteins and novel ingredients, and by the economic logic of reducing dependence on globally traded fishmeal whose price volatility has historically been a significant source of compound feed cost instability. Portugal's feed market producing 4.2 million tons and identified by IACA's Secretary General in August 2024 as a proponent for sustainable agriculture innovations has become a reference point for how insect protein ventures including InsectERA and precision feeding innovation programmes including FeedInov are building the commercial infrastructure that takes alternative ingredients from laboratory validation to farm-scale deployment. As European regulatory frameworks continue to expand the approved applications of insect-derived and single-cell protein ingredients across poultry, aquaculture, and swine feeds, the commercial opportunity for ingredient manufacturers who have invested in scaling production ahead of mainstream adoption is becoming increasingly tangible and the first movers who have built certified production capacity are beginning to convert regulatory approval into long-term supply agreements with major compound feed producers.
Blockchain and AI traceability systems transforming feed supply chain transparency from aspiration to commercial infrastructure
The February 2025 launch of Feedentity an automated supply chain traceability system combining blockchain and AI to monitor environmental factors including temperature and humidity throughout the agri-food supply chain represents the most commercially ambitious integration of traceability technology into European compound feed supply chains yet deployed at meaningful scale. The system's ability to prevent waste, improve sustainability documentation, and provide real-time insights that optimise both agricultural and logistical practices addresses a set of requirements that EU regulatory frameworks are progressively mandating across the feed sector and that major food retailers and processors are already requiring through their own supply chain transparency standards before regulators formally impose them. The December 2024 EU Member States endorsement of an updated Code for Green Labelling for Feed providing detailed guidelines on environmental performance addressing climate change, emissions, and biodiversity, and explicitly supporting the feed sector's efforts to meet Scope 3 emissions requirements signals that traceability investment is transitioning from a voluntary competitive differentiator into a compliance prerequisite that will progressively determine market access for compound feed manufacturers supplying premium retail-aligned livestock production systems across the continent.
Precision feeding technology and IoT-enabled livestock management improving feed conversion efficiency across all animal categories
The integration of sensor networks, IoT-connected feeding systems, and data-driven formulation platforms into European livestock production is delivering measurable improvements in feed conversion ratios that simultaneously reduce the cost per kilogram of animal protein produced and lower the environmental intensity of livestock farming in ways that directly address EU Farm to Fork sustainability objectives. Automatic feeding systems that adjust nutrient delivery in real time based on individual animal weight, health status, and production stage data are reducing the overfeeding that has historically characterised pen-based feeding systems eliminating the nutrient excess that contributes to both feed cost inefficiency and the nitrogen and phosphorus emissions that European environmental regulations are progressively tightening. For compound feed manufacturers, this precision feeding trend creates commercial incentive to develop more tightly specified, stage-appropriate feed formulations that deliver measurably better outcomes when deployed in precision feeding systems shifting the commercial conversation from price-per-tonne to cost-per-unit-of-animal-output and enabling manufacturers with superior formulation science to build pricing power and customer retention that commodity volume competition cannot readily erode.
What the Market Numbers Actually Tell Us
The single-year growth from USD 121.7 Billion in 2025 to USD 127.2 Billion in 2026 an increase of USD 5.5 Billion in twelve months reflects the compounding effect of rising livestock production volumes, ingredient cost inflation flowing through to compound feed pricing, and the progressive premiumisation of feed formulations toward higher-specification products that command superior margins over commodity volume categories. The trajectory to USD 180.4 Billion by 2034 implies the addition of nearly USD 60 Billion in annual market value over nine years a scale of commercial expansion that requires not only growing livestock sector output but the sustained investment in ingredient innovation, production technology, and supply chain infrastructure that transforms how the market creates and captures value per tonne of feed produced. For investors and operators, the market's geographic breadth across Germany, France, the United Kingdom, Italy, Spain, and the broader European region provides structural resilience against country-specific agricultural policy changes, weather-driven production disruptions, and livestock disease events that can materially affect individual national markets while leaving the continental aggregate relatively stable.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe compound feed market sits at the precise intersection of insect protein ingredient scaling and the aquaculture sector's urgent need for certified sustainable fishmeal alternatives that can meet the quality and consistency standards that premium European salmon, sea bass, and sea bream producers require for their export-oriented production systems. Insect protein manufacturers who have built Black Soldier Fly production capacity at commercial scale and who have invested in the processing, quality assurance, and regulatory documentation infrastructure that certified novel ingredient status requires are positioned to capture a structurally growing share of aquaculture feed formulation budgets as fishmeal prices remain elevated and retailer sustainability requirements progressively mandate reduced wild-capture ingredient incorporation across aquaculture supply chains. Simultaneously, the Feedentity traceability model represents the early commercialisation of a service category feed supply chain data management and sustainability documentation that will become progressively more valuable as EU Scope 3 emissions reporting requirements extend down through the livestock supply chain and major food processors begin requiring quantified sustainability performance data from compound feed suppliers as a condition of long-term procurement contracts. Manufacturers and technology providers who build this capability now are positioning themselves at the intersection of regulatory compliance and commercial differentiation in ways that will determine competitive outcomes across the European compound feed market well into the second half of the forecast period.