Philippines Banking Market Growth Analysis & Forecast Report 2026-2034
The Philippines banking market size reached USD 10.4 Billion in 2025. Looking forward, the market is expected to reach USD 62.6 Billion by 2034, exhibiting a growth rate (CAGR) of 22.07% during 2026-2034.
 Arlo Bennett
Market Overview
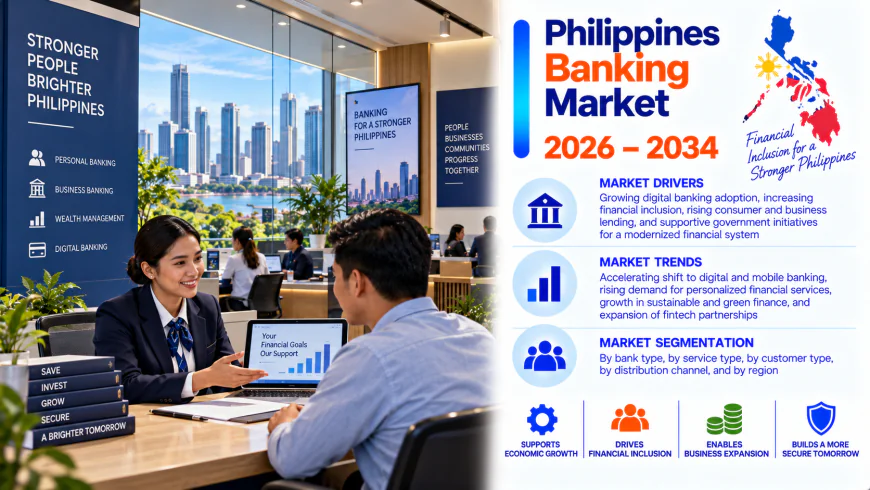
The Philippines banking market reached USD 10.4 Billion in 2025 and is projected to reach USD 62.6 Billion by 2034, growing at a CAGR of 22.07% from 2026 to 2034. The market is experiencing steady expansion, supported by rising financial inclusion, growing middle-class demand, and increasing reliance on remittance-driven services, with digital innovations and supportive regulations reshaping the sector.
Request a Sample Report for In-Depth Market Insights: https://www.imarcgroup.com/philippines-banking-market/requestsample
Philippines Banking Market Summary
- The market covers retail, commercial, investment, and corporate banking, serving individual consumers, SMEs, large corporations, and government and public sector entities.
- Mobile phone imports, including Apple and Samsung devices, reached around USD 3.93 Billion in 2024, reflecting rapid digital adoption that is reshaping how consumers interact with banks.
- Digital wallets have transformed payments, with GCash reporting more than 90 million users across the Philippines as of 2024, and Maya Bank's deposit balances growing to USD 588 Million in the first half of 2024.
- Government-backed initiatives including the National Strategy for Financial Inclusion, open banking regulation, and cashless economy promotion are reshaping the competitive and regulatory landscape.
Porter's Five Forces Analysis
- Competitive Rivalry: High, among traditional banks, digital wallets (GCash, Maya), and fintech-bank partnerships competing for a fast-digitalizing customer base. Business implication: Differentiation increasingly depends on digital platform quality and financial inclusion reach rather than branch presence alone.
- Supplier Power (Technology/Capital): Moderate, given reliance on core banking technology vendors and fintech partners for digital infrastructure upgrades. Business implication: Strategic technology partnerships, like CTBC Bank's with Hitachi Asia, help banks modernize digital offerings efficiently.
- Buyer Power (Consumers/Businesses): High, as digital wallets and mobile banking apps make switching between providers easy and low-cost. Business implication: Convenience, trust, and remittance-linked product features are key to retention.
- Threat of Substitutes: Moderate, from non-bank digital wallets and informal financial systems still used by unbanked rural populations. Business implication: Banks partnering with or acquiring fintech capability can convert informal-system users into formal customers.
- Threat of New Entrants: Moderate, as open banking regulation lowers barriers for fintech entrants, though regulatory licensing and capital requirements remain hurdles for full banking operations. Business implication: Regulatory compliance capability and scale remain durable advantages for established banks.
Market Trends
The Philippines banking market is being shaped by a rapid shift toward digitalization, as rising smartphone penetration and improved internet connectivity push online and mobile banking platforms to become consumers' preferred transaction method, reinforced by bank investment in AI and machine learning for personalized financial services; and by the rise of fintech solutions, as fintech companies fill gaps in traditional banking for underserved and unbanked communities, with collaborations between fintechs and established banks broadening available financial services and digital wallets like GCash and Maya transforming payment systems by letting users transact without a conventional bank account.
Market Growth Drivers
Growth is anchored by an expanding middle-class population, as rising household incomes drive demand for savings accounts, investment products, and credit products like personal loans, mortgages, and credit cards across both urban and semi-urban areas; by increasing focus on financial inclusion, as banks and government initiatives introduce microfinancing, mobile-based banking, and simplified account options to reach rural and underserved populations; and by strong remittance inflows, as the Philippines' position among the world's largest remittance recipients fuels household spending, savings, and bank liquidity, with banks offering remittance-linked savings accounts and preferential loan products.
Market Opportunities
The clearest opportunities lie in open banking-enabled product innovation, where secure data sharing with fintech partners can drive personalized financial products and improved lending solutions; in digital wallet and bank integration, where partnerships between banks and platforms like GCash and Maya can deepen financial inclusion and cross-sell opportunities; and in remittance-linked product expansion, where specialized savings, loan, and transfer services tailored to overseas Filipino workers represent a large, underserved revenue opportunity.
Market Challenges
The market faces the operational challenge of extending formal banking access to rural and remote communities still reliant on informal financial systems; the need to balance rapid digital transformation with cybersecurity and consumer protection, as growing digital transaction volumes raise fraud and data-security risks; and the complexity of scaling personalized, AI-driven financial services while maintaining regulatory compliance amid an evolving open banking framework.
Philippines Banking Market Segmentation
Banking Services Insights
- Retail Banking
- Commercial Banking
- Investment Banking
- Corporate Banking
- Others
End User Insights
- Individual Consumers
- Small and Medium Enterprises (SMEs)
- Large Corporations
- Government and Public Sector Entities
Regional Insights
- Luzon
- Visayas
- Mindanao
Competitive Landscape
The market features traditional banks, digital wallet operators, and fintech-bank partnerships competing on digital platform quality, financial inclusion reach, and remittance-linked product innovation. Differentiation increasingly centers on mobile banking experience, AI-driven personalization, and collaboration between established banks and fintech platforms to broaden service accessibility.
Key players: GCash, Maya Bank (formerly PayMaya), CTBC Bank Philippines, and other traditional and digital banking providers active in the market.
Recent News & Developments
- In July 2024, the Bangko Sentral ng Pilipinas issued Circular No. 1198, Series of 2024, establishing a regulatory policy for merchant payment acceptance activities aimed at securing user funds and protecting merchants' rights in dealings with payment system operators.
- In May 2024, CTBC Bank Philippines announced a strategic partnership with Hitachi Asia to upgrade its mobile banking apps and web interface, boosting digital financing services and supporting greater financial inclusion.
Regional Analysis
- Luzon: Likely the leading market, anchored by Metro Manila's concentration of banking headquarters, digital infrastructure, and financial services activity.
- Visayas: A growing market benefiting from rising digital adoption and expanding financial inclusion initiatives.
- Mindanao: A developing market where growth depends on extending formal banking access to underserved rural communities.
Key Aspects Required for the Philippines Banking Market
- Market Performance: USD 10.4 Billion in 2025, with a projected trajectory to USD 62.6 Billion by 2034.
- Market Outlook: A 22.07% CAGR through 2034, among the fastest-growing banking markets globally, reflecting a still-early stage of digital and financial inclusion development.
- Growth Drivers: An expanding middle-class population; increasing focus on financial inclusion; and strong remittance inflows.
- Key Challenges: Extending access to rural and remote communities, balancing digital transformation with cybersecurity, and scaling personalized services under an evolving regulatory framework.
- Competitive Landscape: A mix of traditional banks, digital wallets, and fintech-bank partnerships differentiating through digital platform quality and inclusion reach.
- Industry Trends: A rapid shift toward digitalization and the rise of fintech solutions.
- Strategic Recommendations: Deepen fintech and digital wallet partnerships; expand remittance-linked product lines; invest in AI-driven personalized banking services; and strengthen cybersecurity and consumer protection infrastructure to support digital growth.
Note: If you need any specific information that is not currently covered within the scope of the report, we will provide the same as a part of customization.
Speak to an analyst: https://www.imarcgroup.com/request?type=report&id=28671&flag=C
Report Format, Delivery, and Customization Details
- Report Format Mode: PDF and Excel (Editable version in PPT/Word format available on special request)
- Report Delivery Mode: Online Delivery, Physical Delivery
- Report Delivery Time: report delivered over email within 24 to 48 hours. If requested by the client, a physical copy will be delivered within three to ten days.
- Report Confirmation Mode: Yes, via email
- Report Customization Mode: Yes, via Email / Call
- Report Table of Content: Yes
- Report List of Figures: Yes
- Report Methodology Mode: Yes
- Request For Sample Report: Yes