Europe Commercial Printing Market: Why Packaging Is Becoming the Industry's Most Resilient Growth Engine
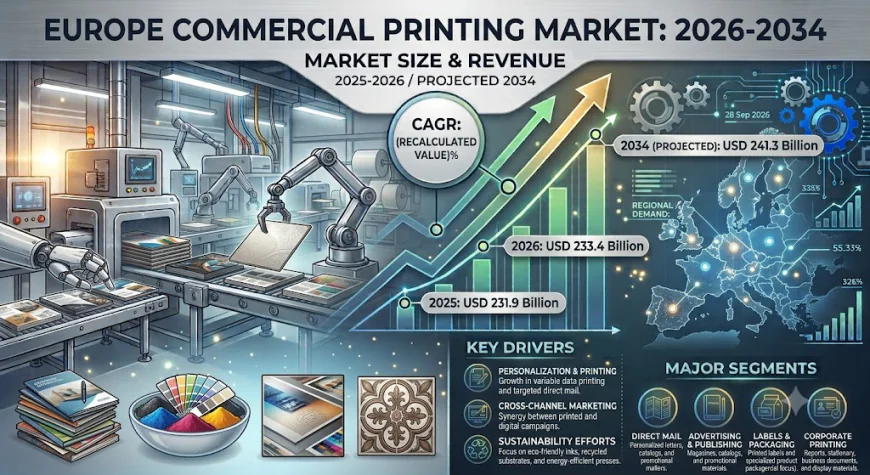
Europe commercial printing market grew from USD 231.9 Billion in 2025 to USD 233.4 Billion in 2026 and is projected to reach USD 241.3 Billion by 2034.
 Team Imarc
There is a revealing paradox at the centre of the Europe commercial printing market. An industry that media commentary has declared in structural decline for over a decade displaced by digital communication, diminished by the collapse of print advertising, and disrupted by the migration of publishing online is nonetheless a USD 233 Billion market growing steadily toward USD 241 Billion by 2034. The explanation for that paradox is packaging. While print advertising volumes contract and newspaper print runs shrink, the explosion of e-commerce parcels, branded consumer goods, and food and beverage products moving through European retail and logistics networks is generating more printed packaging than any previous point in the industry's history.
The market data captures that structural bifurcation clearly. The Europe commercial printing market grew from USD 231.9 Billion in 2025 to USD 233.4 Billion in 2026 and is projected to reach USD 241.3 Billion by 2034. That incremental but consistent expansion across a market of extraordinary scale reflects a category that has successfully reanchored its commercial centre of gravity from the declining segments of traditional publishing and advertising print toward the structurally growing segments of packaging, labels, and personalised promotional material that e-commerce and consumer goods demand is generating in expanding and predictable volumes.
What's Driving Growth in the Europe Commercial Printing Market?
- E-commerce expansion sustaining packaging print as the market's structural backbone is the single most commercially consequential demand driver across the entire European commercial printing landscape. Packaging commands a 52.6% application share in 2025 the majority of a market worth over USD 230 Billion reflecting the volume of corrugated boxes, folding cartons, flexible packaging, and branded labels that Europe's expanding parcel economy generates with each passing year. As EU online enterprise sales penetration continues to climb, the packaging print segment benefits from a demand driver that is structural and compounding rather than cyclical or discretionary.
- Image print type leading the market at 46.3% share anchored by sustained demand for packaging graphics, product labels, and photo-realistic promotional print across consumer goods, food and beverage, and retail categories reflecting how the visual presentation of products across both physical and e-commerce retail environments is commanding increasing investment from brand owners who understand that packaging design is simultaneously a brand communication and a consumer acquisition tool.
- Germany's market leadership at 26.8% of continental revenue anchored by its unmatched concentration of automotive, pharmaceutical, and industrial manufacturing activity that generates consistent demand for high-specification packaging, technical documentation, and product labelling across some of Europe's most quality-sensitive production environments. Germany's advanced press technology ecosystem and emphasis on production efficiency sustain the competitive leadership position that makes it the continental benchmark for printing quality and innovation simultaneously.
- Digital printing adoption accelerating short-run and variable-data capability across converters of all scales, enabling brands to commission more frequent, more localised, and more personalised print runs without the setup cost burden of conventional offset or gravure processes. At FESPA 2025 in Berlin, EFI showcased advanced digital printing solutions for signage and packaging a visible signal of the technology investment flowing into the European converter base from press manufacturers whose own commercial success depends on convincing operators that digital investment delivers returns across the packaging and promotional categories where order volumes and run lengths are both shifting simultaneously.
- Spain emerging as the fastest-growing national market at 9.6% share in 2025 driven by expanding food and beverage packaging exports that leverage Spain's position as one of Europe's largest agricultural producers and exporters, combined with a modernising converter base investing in digital press capacity and sustainable substrate capability that is progressively qualifying Spanish operators for international brand owner procurement programmes that previously directed packaging volumes toward higher-cost Western European facilities.
Three Trends Reshaping the Industry
Sustainable substrate and recyclable packaging mandates restructuring the entire converter supply chain
The EU's Packaging and Packaging Waste Regulation with general application beginning August 2026 is proving to be the most commercially consequential regulatory development the European commercial printing industry has encountered in a generation, and its impact is being felt not as a compliance burden but as a fundamental restructuring of which converters win large brand owner contracts. The shift toward mono-material, recyclable, and fiber-based packaging substrates is requiring printers to invest in new ink formulations compatible with recycled content paper and board, sustainable coating systems that maintain barrier performance without compromising end-of-life recyclability, and quality management processes that can certify compliance with evolving EU packaging standards across multiple national regulatory interpretations simultaneously. Converters who have made early investments in water-based and UV-curable ink systems, recyclable laminate structures, and certified sustainable substrate sourcing are finding that their compliance readiness is translating directly into competitive advantage in major brand owner tender processes where sustainability documentation has become as commercially important as price and lead time. The market concentration data underscores this dynamic: Smurfit Westrock's integrated paper-based packaging capability, Mondi's sustainable substrate innovation, and Amcor's flexible packaging material science are positioning these operators as the structural beneficiaries of a regulatory transition that is simultaneously expanding their addressable market and raising the entry barriers against converters who have deferred sustainability investment.
Workflow automation and AI-assisted prepress compressing the cost base of short-run production
The economics of short-run commercial printing historically constrained by the setup time, plate costs, and operator skill requirements of conventional offset and flexographic processes are being systematically improved by the integration of cloud-based job routing, AI-assisted colour management, and automated imposition systems that compress prepress cycles from hours to minutes and eliminate the manual intervention points that previously made short runs commercially marginal. For mid-sized converters whose competitive advantage over large integrated operators lies in flexibility, turnaround speed, and customer relationship depth rather than scale economics, these automation investments are enabling them to serve the growing market for personalised packaging, localised promotional campaigns, and seasonal packaging variants that brand owners are commissioning with increasing frequency and decreasing lead time expectations. Cimpress's continued expansion of its web-to-print mass customisation platform serving small businesses across Europe through its Vistaprint brand with automated design, production, and fulfilment workflows illustrates how the automation investment thesis is being validated at commercial scale, with the company's ability to handle millions of small, unique print orders profitably demonstrating that short-run economics can be fundamentally restructured rather than merely incrementally improved.
Smart packaging and traceability features embedding commercial printing into the digital supply chain
The integration of serialisation codes, QR-based traceability systems, and NFC-enabled packaging features into commercially printed packaging and labels is creating an entirely new value dimension for converters willing to invest in the variable data printing capability and digital-physical integration expertise these features require. European brand owners across food and beverage, pharmaceutical, and consumer electronics categories are increasingly specifying traceability features as standard packaging requirements driven simultaneously by EU regulatory traceability mandates, supply chain transparency demands from retail customers, and consumer engagement strategies that use packaging as a digital touchpoint connecting physical product with online brand experience. For converters, the ability to produce traceability-enabled packaging requires not only variable data printing capability the technical foundation that serialised codes and unique QR identifiers demand but also the data management infrastructure and customer integration capability to ensure that each printed code is correctly associated with the supply chain data record it is designed to carry. Converters who have invested in this capability are commanding premium pricing and building the kind of deep technical integration with key accounts that makes switching costs substantial a commercial moat that pure-price competition cannot readily erode.
What the Market Numbers Actually Tell Us
The single-year growth from USD 231.9 Billion in 2025 to USD 233.4 Billion in 2026 — before the longer trajectory to USD 241.3 Billion by 2034 reflects a market that has successfully navigated its structural transition from publishing and advertising dependence toward packaging leadership, and is now growing on the strength of compounding e-commerce demand, sustainability-driven substrate migration, and digital technology adoption that is progressively improving the economics of short-run production. The advertising segment's 27.8% share while under structural pressure from digital media substitution reflects the persistent commercial logic of direct mail, point-of-sale print, and promotional material that brand owners continue to commission because physical print delivers engagement rates and demographic targeting characteristics that digital channels cannot consistently replicate for specific consumer segments. For investors and operators, the market's moderate fragmentation with the top five companies including Bertelsmann, Cimpress, Smurfit Westrock, Mondi, and Amcor accounting for a meaningful but non-dominant share of regional output signals both ongoing consolidation opportunity as smaller offset operators exit declining publication print segments and meaningful space for well-positioned mid-sized converters to build durable businesses in the packaging and speciality print segments where scale advantages are less definitive than in commodity volume categories.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe commercial printing market sits at the intersection of sustainable packaging mandate compliance and Spain's accelerating converter modernisation programme. As EU packaging regulation progressively tightens the recyclability and recycled content requirements that apply to all packaging placed on the European market regardless of where it is produced Spanish converters who invest now in sustainable substrate capability, certified ink systems, and digital production technology are positioned to capture a growing share of the food and beverage packaging volumes that Northern and Western European brand owners are actively seeking to source from lower-cost, EU-compliant suppliers within the single market. For operators and investors willing to direct capital toward the Spanish converter base ahead of the regulatory transition that is making sustainability compliance a commercial prerequisite rather than a differentiation option, the combination of growing export opportunity, modernising technology infrastructure, and competitive labour economics creates a geographic investment thesis with both near-term volume capture potential and long-term structural positioning advantage as the European packaging supply chain continues to consolidate around the sustainability-capable operators that EU regulation is systematically selecting for commercial success.