Europe Biosimilar Market: How Patent Cliffs Are Unlocking the Continent's Most Compelling Healthcare Investment
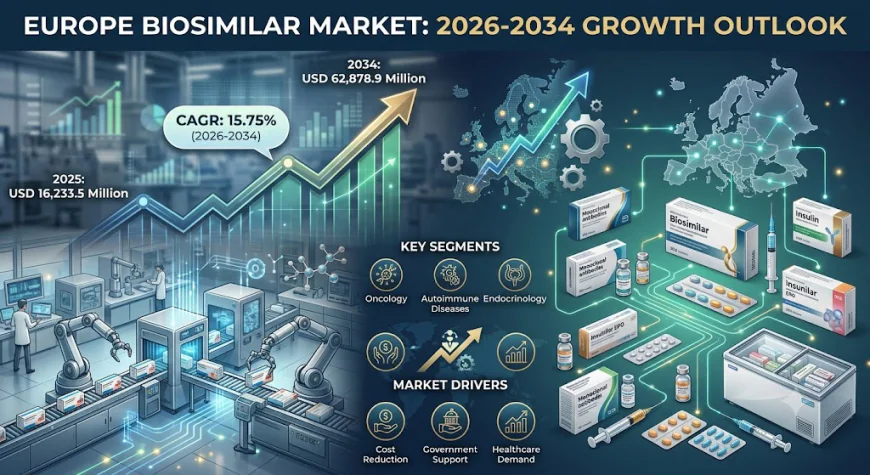
Europe biosimilar market was valued at USD 16,233.5 Million in 2025 and is estimated to reach USD 62,878.9 Million by 2034, growing at a CAGR of 15.75% during 2026–2034.
 Team Imarc
There is a financial reckoning built into every blockbuster biologic drug's commercial life cycle — the patent expiry that transforms an exclusive, high-margin therapy into a competitive marketplace where biosimilar manufacturers can offer clinically equivalent alternatives at significantly lower prices. In Europe, that reckoning is happening simultaneously across multiple high-revenue molecules, at a scale and pace that is generating one of the most commercially significant healthcare market opportunities on the continent. More than 100 biosimilar medicines have been approved for nearly 30 reference biologics in Europe since the European Medicines Agency established its biosimilar regulatory pathway in 2006 — a number that understates the acceleration now underway as the patent cliff steepens through the late 2020s.
The market data captures that acceleration with striking clarity. The Europe biosimilar market was valued at USD 16,233.5 Million in 2025 and is estimated to reach USD 62,878.9 Million by 2034, growing at a CAGR of 15.75% during 2026–2034. A near-quadrupling of market value over nine years is not incremental pharmaceutical growth — it is a structural transformation of how Europe procures, reimburses, and delivers biologic therapy to a population whose chronic disease burden is simultaneously expanding and whose healthcare systems are under mounting financial pressure to find more sustainable treatment economics.
What's Driving Growth in the Europe Biosimilar Market?
- Cascading patent expiries of major biologic molecules are the foundational commercial catalyst for the entire market. As adalimumab, ustekinumab, aflibercept, and a pipeline of other high-revenue reference biologics lose exclusivity across European markets in sequential succession, biosimilar manufacturers are gaining access to therapeutic categories that collectively represent tens of billions of euros in annual procurement spend — creating a commercial opportunity whose scale is directly proportional to the size of the originator market being disrupted.
- Chronic disease burden intensifying across an ageing European population is sustaining the clinical demand that makes biosimilar adoption economically and therapeutically consequential. More than one-third of EU residents — 36.1% — reported a long-standing chronic health condition in 2022, while non-communicable diseases account for 80% of the disease burden across EU countries. With approximately 24 million people in Italy alone afflicted by chronic diseases, and over 4 million new cancer cases estimated across Europe annually, the patient populations requiring biologic therapies are growing at precisely the moment when biosimilar competition is making those therapies more accessible.
- Italy's market leadership at 20.8% continental revenue share in 2025 anchored by its large chronic disease patient population, the Italian Medicines Agency's active biosimilar promotion policies, and a domestic regulatory environment that has systematically built prescriber and patient confidence in biosimilar switching — provides the most commercially developed national model for how biosimilar adoption scales when policy, clinical acceptance, and patient awareness align simultaneously.
- Auto-immune diseases commanding 38.2% of indication share in 2025 reflects the therapeutic category where biosimilar competition has advanced furthest and delivered the most measurable healthcare system savings. Infliximab — the market's leading molecule at 17.5% share — has demonstrated the commercial template for biosimilar market development in Europe: initial hospital tender competition drives rapid price reduction, followed by expanding community prescribing as clinical familiarity and prescriber confidence grow across rheumatology, gastroenterology, and dermatology specialties.
- In-house manufacturing's 80.3% dominance reflects the strategic commitment of leading biosimilar developers to controlling the entire production process — from cell line development through formulation and fill-finish — ensuring the quality consistency, regulatory compliance, and supply chain resilience that health system procurement bodies require as prerequisites for large-scale tender participation. This manufacturing philosophy is simultaneously a competitive moat and a capital commitment signal that distinguishes biosimilar developers with genuine long-term market ambitions from those pursuing opportunistic portfolio licensing strategies.
Three Trends Reshaping the Industry
EMA regulatory acceleration building the approval pipeline that sustains decade-long market expansion
The European Medicines Agency's biosimilar regulatory pathway — the world's most established and scientifically rigorous framework for demonstrating similarity in efficacy, safety, and quality with reference biologics — is processing an expanding pipeline of applications with accelerating efficiency as both regulatory science and manufacturer submission quality mature. The April 2024 Committee for Medicinal Products for Human Use recommendation of marketing authorisation for two biosimilar medicines covering rheumatoid arthritis, COVID-19, polyarticular juvenile idiopathic arthritis, and systemic juvenile conditions illustrates the therapeutic breadth of molecules entering the approved biosimilar catalogue. Sandoz's January 2024 launch of Pyzchiva — biosimilar ustekinumab developed by Samsung Bioepis, approved for autoimmune disorders across gastroenterology and dermatology — followed by its May 2025 relaunch as an autoinjector format beginning in Spain, demonstrates how the regulatory approval pipeline translates into commercial launches that progressively expand patient access to more affordable biologic therapy across multiple disease areas simultaneously.
Strategic alliance architecture accelerating pan-European commercial reach
The biosimilar industry's most commercially significant structural development is the rapid proliferation of strategic licensing and co-commercialisation alliances that are enabling developers with manufacturing expertise to access the distribution networks, market access capabilities, and country-specific regulatory knowledge of established European pharmaceutical operators — without replicating those capabilities organically across twenty-seven national markets. Alvotech and Advanz Pharma's May 2025 expansion of their strategic alliance to include three additional biosimilar candidates — covering ofatumumab, canakinumab, and an early-stage molecule — illustrates how alliance frameworks are being structured to build diversified biosimilar portfolios rather than pursuing molecule-by-molecule licensing arrangements. Teva's January 2025 partnership with Klinge Biopharma and Formycon to commercialise FYB203, a biosimilar to aflibercept targeting ophthalmic indications, under the AHZANTIVE brand across major European countries further demonstrates how established pharmaceutical distribution organisations are becoming active participants in biosimilar commercialisation — bringing market access infrastructure that pure-play biosimilar developers cannot build independently at equivalent speed or cost.
Autoinjector and patient-friendly delivery format innovation expanding adoption beyond hospital channels
The biosimilar market's commercial expansion into community prescribing settings — beyond its initial concentration in hospital tender frameworks — is being actively enabled by delivery format innovation that makes self-administration accessible, comfortable, and adherence-supporting for patients managing chronic conditions on long-term biologic therapy. Sandoz's May 2025 launch of Pyzchiva as the first ustekinumab biosimilar available in autoinjector format in Europe represents precisely the kind of device innovation that transitions a biosimilar from a hospital procurement decision into a patient-initiated and general practitioner-supported therapy choice in dermatology and gastroenterology community settings. Dong-A ST's sequential expansion of its Stelara biosimilar Imuldosa — from its January 2025 debut in Germany through April 2025 launches in the United Kingdom and Ireland, with planned rollouts across France, Spain, and Italy — illustrates how biosimilar commercialisation strategies are being executed through careful, sequenced national market entries that build prescriber familiarity and reimbursement framework inclusion progressively across the continent.
What the Market Numbers Actually Tell Us
A CAGR of 15.75% sustained over nine years — producing a market that grows from USD 16.2 Billion to nearly USD 62.9 Billion — is a growth trajectory that reflects simultaneous expansion across therapeutic categories, national markets, and patient populations rather than concentration in any single high-velocity segment. The near-quadrupling of market value implies that the incremental USD 46.6 Billion in annual biosimilar spend being generated by 2034 represents a combination of new therapeutic categories entering biosimilar competition as reference biologics lose patent protection, growing penetration of existing biosimilar categories within national markets that are still in early adoption phases, and the absolute growth of the chronic disease patient populations requiring biologic therapy across an ageing European demographic. For the healthcare systems of Germany, France, the United Kingdom, Spain, and Italy — all managing the fiscal challenge of expanding biologic treatment access within constrained pharmaceutical budgets — the biosimilar market's growth trajectory represents an expanding fiscal resource rather than a commercial abstraction.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the Europe biosimilar market sits at the intersection of oncology biosimilar adoption and the health technology assessment frameworks that are progressively standardising how European payers evaluate and reimburse biologic cancer therapies. Oncology biosimilars — currently representing a smaller indication share than auto-immune disease applications despite the scale of the cancer treatment market — are positioned for accelerating adoption as rituximab, trastuzumab, and bevacizumab biosimilar competition matures and as new oncology reference biologics approach patent expiry. The therapeutic stakes in oncology — where biologic therapies can cost tens of thousands of euros per patient annually — mean that biosimilar price competition delivers healthcare system savings of a magnitude that no other pharmaceutical policy intervention can readily replicate at equivalent scale. For biosimilar manufacturers with the manufacturing capability, regulatory expertise, and commercial infrastructure to compete credibly in oncology tendering across multiple European national markets simultaneously, the oncology indication represents the next frontier where the Europe biosimilar market's exceptional growth trajectory will be most directly concentrated over the second half of the forecast period.