Electric Vehicle Motor Market Size, Share, Industry Trends, Analysis and Forecast 2026-2034
The global electric vehicle motor market reached USD 54.02 Billion in 2025 and is projected to reach USD 211.72 Billion by 2034, growing at a CAGR of 16.39% during 2026-2034.
 Robertmarketresearcher
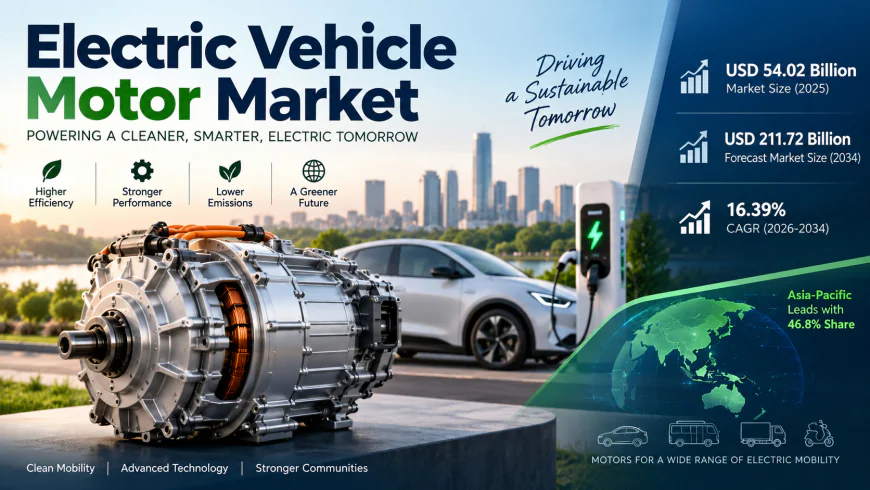
According to a research report by IMARC Group, the global electric vehicle motor market size reached USD 54.02 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 211.72 Billion by 2034, exhibiting a growth rate (CAGR) of 16.39% during 2026-2034. Asia-Pacific currently leads the regional landscape, supported by China's large-scale production of battery electric vehicles, Japan's strength in motor manufacturing, and India's fast-growing electric two-wheeler segment. Growth in the market is chiefly attributed to rising global EV sales, tightening emission regulations, expanding government incentive programs, and continuous advances in permanent magnet synchronous motor technology.
Request for a Sample Report for Detailed Evaluation: https://www.imarcgroup.com/electric-vehicle-motor-market/requestsample
● Market Size & Growth: The global electric vehicle motor market was valued at USD 54.02 Billion in 2025 and is projected to reach USD 211.72 Billion by 2034, registering a CAGR of 16.39% during 2026–2034, according to IMARC Group.
● Regional Leadership: Asia-Pacific represents the largest regional market, holding a 46.8% share in 2025, supported by China's electric vehicle production scale, Japan's motor manufacturing base, and India's rapidly electrifying two-wheeler fleet.
● By Power Rating: The market is segmented into up to 20 kW, 20 kW to 100 kW, 100 kW to 250 kW, and above 250 kW, with the 100 kW to 250 kW band forming the largest segment at a 38.4% share.
● By Application: The market is divided into two-wheelers, three-wheelers, passenger vehicles, and commercial vehicles, with passenger vehicles accounting for the largest share at 47.9%.
● Key Market Drivers: Rising global BEV sales, declining battery costs, stricter emission mandates, and government incentive schemes supporting electric mobility adoption.
● Key Market Trends: Growing adoption of 800V high-voltage platforms with SiC inverter-integrated e-axles, development of in-wheel hub motors, and the shift from standalone motor supply toward integrated motor-inverter-gearbox e-axle systems.
● Key Market Challenges: Rising R&D and manufacturing capital requirements, uneven grid infrastructure in emerging markets, and increasing competitive pressure from domestic Chinese motor suppliers.
● Key Players: Leading players in the global electric vehicle motor market include NIDEC CORPORATION, BorgWarner Inc., ZF Friedrichshafen AG, Magna International Inc., and others.
What Is Driving Electric Vehicle Motor Market Growth in 2026?
Rising Global EV Sales and Expanding BEV Fleets
Global electric car sales moved past the 20-million-unit mark in 2025, up roughly 20% from the prior year, with China alone contributing more than 13 million units and close to 60% of worldwide demand. As every battery electric vehicle needs one or more traction motors, this scale of vehicle output is translating directly into stronger demand for electric vehicle motors, particularly as multi-motor dual and quad-motor platforms become more common and raise the number of motors required per vehicle.
Declining Battery Costs Improving EV Affordability
Falling battery prices are bringing down the overall cost of electric vehicles, widening their appeal beyond early adopters and into mainstream car buyers. As affordability improves, automakers are scaling up BEV production to meet growing demand, and this expansion feeds through directly into higher procurement volumes for traction motors and related drivetrain components.
Government Incentives and Emission Regulations
Subsidies, tax credits, purchase incentives, and tightening emission standards continue to push automakers toward electrified powertrains. In India alone, government schemes had incentivized more than 16.29 lakh electric vehicles as of mid-2025 across two-wheelers, three-wheelers, four-wheelers, and buses, illustrating how policy support is accelerating EV output and, in turn, motor demand across vehicle categories.
Connect for Detailed Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=8470&flag=C
Electric Vehicle Motor Market Segmentation Analysis:
By Power Rating
● Up to 20 kW
● 20 kW to 100 kW
● 100 kW to 250 kW
● Above 250 kW
The 100 kW to 250 kW band leads the market with a 38.4% share, covering the mainstream battery electric passenger car segment and growing at roughly 17.2% CAGR as multi-motor platforms expand. The 20 kW to 100 kW range holds 31.7% of the market, serving small passenger BEVs and performance electric motorcycles, while motors up to 20 kW account for 19.6%, driven largely by India and China's electric two- and three-wheeler volumes. Motors above 250 kW, at 10.3%, serve performance BEVs and electric commercial vehicles at higher per-unit values.
By Application
● Two-Wheeler
● Three-Wheeler
● Passenger Vehicle
● Commercial Vehicle
Passenger vehicles form the largest application segment at 47.9%, supported by the highest per-unit motor value and the fastest-growing multi-motor platform trend, which is lifting this segment's CAGR to around 17.5%. Two-wheelers follow at 26.4% and represent the highest unit-count application worldwide, led by China's electric bicycle output and India's electric scooter sales. Commercial vehicles, at 15.2%, are seeing the fastest absolute revenue growth as electric buses and delivery vans enter fleets, while three-wheelers hold 10.5%, concentrated in India's and China's autorickshaw and cargo three-wheeler markets.
By Region
● Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
● Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
● North America (United States, Canada)
● Latin America (Brazil, Mexico, Others)
● Middle East and Africa
Asia-Pacific commands the largest regional share at 46.8%, driven by China's EV production scale, Japan's motor manufacturing strength, and India's two-wheeler electrification. Europe follows at 23.7%, propelled by CO2 emission mandates and continued investment in EV manufacturing capacity. North America holds 18.5% of the market on the back of EV production expansion, incentive programs, and growing domestic supply chains, while Latin America (6.2%) and the Middle East and Africa (4.8%) remain earlier-stage but growing markets, led respectively by Brazil's electric bus fleets and premium EV imports in the Gulf region.
Key Regional Insight: Asia-Pacific's Strategic Position
Asia-Pacific's leadership in the global electric vehicle motor market rests on China's unmatched scale of BEV production, Japan's long-standing expertise in precision motor manufacturing, and India's rapidly expanding electric two-wheeler and three-wheeler segments. Continued government support for EV adoption, combined with expanding battery and motor manufacturing capacity across the region, is expected to keep Asia-Pacific at the center of global demand through 2034.
Competitive Landscape in the Electric Vehicle Motor Industry
The competitive landscape is moderately concentrated, with established Tier-1 suppliers, specialty motor technology firms, and an expanding base of domestic Chinese manufacturers competing across different tiers of the market. Leading suppliers are investing in integrated e-axle systems that combine motors, inverters, and gearboxes into single, ready-to-install drivetrain modules, while also advancing silicon carbide inverter technology and axial flux motor designs. OEM decisions to bring motor manufacturing in-house are reshaping the external supply market, though the sheer scale of global BEV production growth continues to generate more opportunity than captive integration can absorb.
Key Electric Vehicle Motor Market Players Include:
● NIDEC CORPORATION
● BorgWarner Inc.
● ZF Friedrichshafen AG
● Magna International Inc.
Conclusion: Electric Vehicle Motor Market Outlook to 2034
The global electric vehicle motor market is set for sustained growth through 2034, underpinned by rising BEV sales, falling battery costs, supportive government policy, and continued innovation in motor and inverter technology. While high development costs and uneven charging infrastructure in emerging markets present ongoing challenges, suppliers remain focused on delivering more efficient, compact, and cost-effective traction motor solutions.
With Asia-Pacific maintaining its position as the leading regional market and Europe, North America, Latin America, and the Middle East and Africa offering further growth avenues, the outlook through 2034 remains strongly positive. Companies investing in SiC vertical integration, axial flux motor commercialization, and two-wheeler and commercial vehicle motor manufacturing will be best placed to capture value as the market evolves alongside the broader shift to electrified transport.
About the Author:
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Energy and Mining, Construction and Manufacturing, Automotive, Chemicals and Materials, and more.
Media & Sales Contact:
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104