European Frozen Seafood Market: How Discount Retail Expansion Is Democratising Access to Ocean Protein
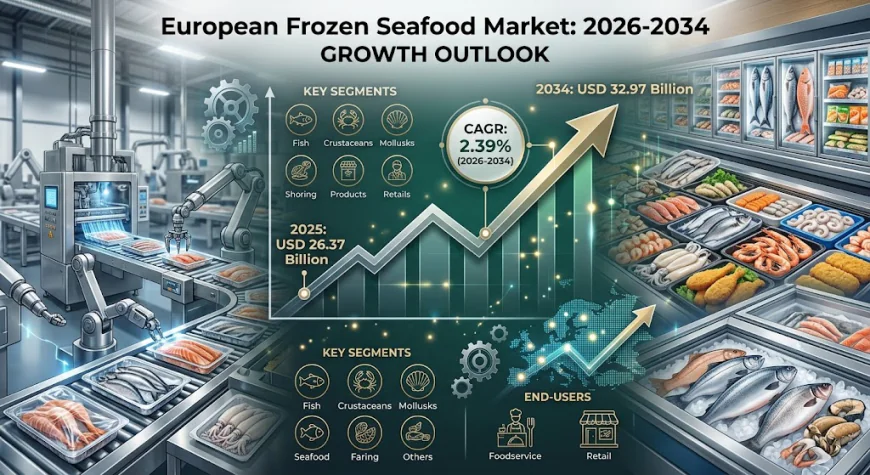
European frozen seafood market was valued at USD 26.37 Billion in 2025 and is projected to reach USD 32.97 Billion by 2034.
 Team Imarc
Frozen seafood has always occupied a pragmatic position in the European kitchen — the protein that offers the nutritional profile of fresh fish at a price point accessible to households managing budgets rather than indulging preferences. What has changed is the commercial infrastructure surrounding that pragmatism. Discount retail formats have expanded across the continent with a speed and geographic reach that no previous retail model achieved, cold-chain technology has advanced to the point where frozen products are genuinely competitive with fresh on taste and nutrition, and sustainability certification has given environmentally conscious consumers a credible framework for choosing frozen over fresh without the perception of compromise.
The market data captures that structural evolution clearly. The European frozen seafood market was valued at USD 26.37 Billion in 2025 and is projected to reach USD 32.97 Billion by 2034, growing at a CAGR of 2.39% during 2026–2034. That measured, consistent growth trajectory across a food category defined by deep cultural embeddedness and conservative consumer behaviour reflects the cumulative effect of convenience demand, discount retail penetration, and sustainability-driven supply chain investment — forces that operate independently of economic cycles and compound quietly over the long term.
What's Driving Growth in the European Frozen Seafood Market?
- Rising demand for convenient, protein-rich meal solutions is the foundational consumer driver across every European market. As dual-income households become the continental norm and preparation time shrinks as a priority in meal planning, frozen seafood's combination of instant availability, extended shelf life, and superior nutritional retention through IQF technology is converting previously hesitant consumers into consistent purchasers. Breaded cod fillets, marinated prawn packs, and portioned salmon fillets are gaining consistent traction across retail channels because they eliminate the preparation complexity that has historically deterred weekday seafood consumption.
- Discount retailer dominance commanding 42.3% of distribution share in 2025 is the single most commercially consequential structural feature of the European frozen seafood market. Lidl and ALDI's expansion across thousands of stores throughout Central and Eastern Europe has positioned frozen seafood as a core category through competitively priced private-label offerings — making frozen fish and shellfish accessible to consumer segments that branded product pricing had previously excluded. This channel dynamic is simultaneously expanding the total consumer base for frozen seafood and creating intense pricing pressure on established branded players.
- Spain's market leadership at 22.4% of continental revenue anchored by approximately 41.92 kilograms per capita annual seafood consumption — among the highest globally — provides the demand foundation that no other European country replicates at equivalent scale. Spain's mature domestic frozen seafood processing industry, concentrated in Galicia and the Basque Country, supports both domestic consumption volumes and significant export activity, creating the supply chain depth and commercial sophistication that define the market's most developed national ecosystem.
- Cold-chain infrastructure modernisation across Eastern Europe is progressively unlocking market penetration in the continent's highest-growth geography. Investments in cold storage and refrigerated logistics across Poland, Italy, and Portugal are improving product availability and quality at the retail level — while IQF freezing technology's ability to preserve nutrition comparable to fresh seafood is eroding the quality perception gap that previously limited category penetration among less established frozen food consumers.
- MSC and ASC sustainability certification gaining retail mandate status is restructuring supply chains rather than simply influencing consumer preference. European retailers including Lidl, ALDI, and Carrefour are increasingly mandating certified sustainable sourcing across their frozen seafood private-label ranges — compelling suppliers throughout the value chain to invest in certification compliance as a commercial prerequisite rather than a voluntary differentiator. Nomad Foods' achievement of 99.6% MSC/ASC-certified seafood sourcing in 2024 illustrates the pace at which leading operators are meeting these retail mandates.
Three Trends Reshaping the Industry
Private-label expansion rewriting the competitive economics of the entire category
The most commercially consequential trend reshaping the European frozen seafood market is the accelerating displacement of branded products by retailer-owned private-label offerings across discount and mainstream supermarket channels. As Lidl, ALDI, Tesco, and Carrefour invest in expanding and upgrading their own-brand frozen seafood ranges — offering comparable product quality at meaningfully lower prices — the commercial justification for branded product premiums is being systematically eroded. This dynamic is simultaneously expanding total category consumption by making frozen seafood accessible to price-sensitive households and compressing the margins of established branded players who cannot match discount retailers' private-label cost structures. For branded manufacturers, the strategic response increasingly involves product innovation and format differentiation in the value-added ready-to-cook segment — the one category where brand equity and recipe development can sustainably justify the premium over private-label alternatives. Nomad Foods' EUR 3.1 Billion revenue in 2024 across its Birds Eye, Findus, and Iglo brand portfolio demonstrates that scale, innovation investment, and sustainability credentials can sustain branded positioning even in a market where private-label growth is structurally advantaged.
Poland's emergence as Eastern Europe's frozen seafood processing and distribution hub
Poland's trajectory from a secondary consumption market to the fastest-growing country in the European frozen seafood market — and simultaneously a significant re-export hub serving Western European retailers — represents one of the most commercially significant geographic developments in the market's recent history. Poland's 8.6% share in 2025 is supported by expanding domestic seafood processing capacity that serves both rising local consumption — driven by growing disposable incomes and increasing health awareness around seafood nutrition — and the cost-competitive processing economics that make Polish facilities attractive for Western European private-label supply chains. The country's position within the EU single market, combined with its access to Baltic Sea catches and well-developed cold-chain logistics infrastructure, is enabling Polish processors to capture value chain activity that previously occurred closer to the point of consumption in higher-cost Western European markets. For investors and operators, Poland's dual role as a high-growth consumption market and a low-cost processing base creates a strategically unusual combination of demand-side and supply-side commercial opportunity within a single geographic investment decision.
Ready-to-cook and value-added formats capturing the category's fastest-growing commercial segment
The structural divergence within the European frozen seafood market between commodity volume categories and value-added ready-to-cook formats is creating a two-speed commercial dynamic that is reshaping investment and innovation priorities across the entire industry. While groundfish's 28.4% volume share reflects the category's established demand base, it is the breaded, battered, marinated, and portioned product formats growing faster than overall market averages that represent the most commercially attractive investment frontier. Consumers across Germany, the United Kingdom, and France are demonstrating consistent and measurable willingness to pay premiums for frozen seafood products that eliminate preparation steps — garlic prawn packs, battered haddock portions, and teriyaki salmon fillets that convert a category purchase into a complete meal solution. Nueva Pescanova's July 2025 announcement of a EUR 16 Million investment in a new seafood processing facility in Spain — specifically targeting expanded value-added frozen seafood production capacity — illustrates how leading operators are directing capital toward the format segments where consumer willingness to pay is highest and private-label competitive pressure is most manageable through recipe differentiation.
What the Market Numbers Actually Tell Us
Adding USD 6.6 Billion in cumulative market value over nine years across a food category as mature and culturally embedded as European seafood consumption reflects the compounding effect of three simultaneously operating demand forces — geographic expansion into Eastern European markets, format migration toward value-added products that command higher per-unit revenue, and sustainability-driven supply chain investment that is progressively improving the quality and trustworthiness of frozen seafood as a category. The market's moderate concentration structure — with the top five companies including Nomad Foods, Mowi ASA, Thai Union, Nueva Pescanova, and Frosta accounting for approximately 30–35% of European revenue in 2025, while numerous regional processors and private-label suppliers maintain significant collective market presence — reflects a competitive landscape where scale advantages coexist with meaningful fragmentation at the national level. For investors, this fragmentation signals ongoing consolidation opportunity as smaller processors facing sustainability certification compliance costs and cold-chain energy inflation become acquisition targets for larger integrated operators with the capital to absorb these structural cost pressures.
Where New Opportunities Are Emerging
The most commercially significant emerging opportunity in the European frozen seafood market sits at the intersection of land-based aquaculture technology and the frozen premium segment's growing appetite for traceable, sustainably produced product. Norway's RAS aquaculture investment — including Mowi's development of a 6,000-tonne post-smolt RAS facility with first deliveries expected in 2026 — is building the supply chain infrastructure for a category of frozen salmon products whose provenance, environmental footprint, and quality consistency can be certified at a granularity that wild-catch and conventional aquaculture supply chains cannot match. For brands and retailers able to communicate this traceability advantage credibly to premium-oriented consumers, the frozen segment can capture purchase occasions that currently default to fresh — particularly in markets including France and Italy where the cultural preference for fresh seafood has historically been the primary barrier to frozen category penetration at the premium tier. Simultaneously, the plant-based frozen seafood segment — with Good Catch and Nestlé's Garden Gourmet already establishing positions in European retail — represents a structurally new demand layer that is additive to rather than substitutive of conventional frozen seafood volume, attracting flexitarian and health-conscious consumers who represent an incremental rather than a cannibalistic commercial opportunity for the category.