Complete Guide to Royal Enfield Bike Insurance Coverage
Understand Royal Enfield bike insurance coverage, including third-party liability, comprehensive protection, theft, accidental damage, IDV, add-ons, exclusions, premiums and renewal tips to choose suitable protection for your bike.
 squareinsurance
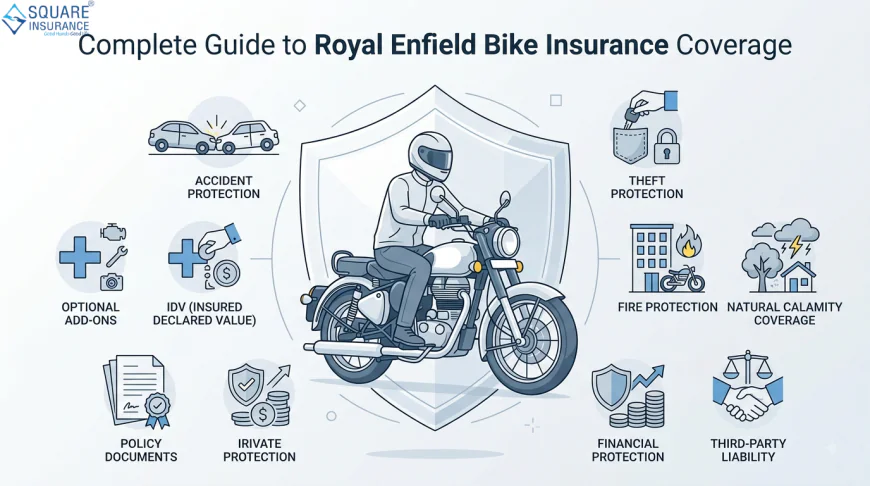
Royal Enfield motorcycles are known for their distinctive design, strong road presence and long-distance riding appeal. Whether you own a Classic, Bullet, Hunter, Meteor, Himalayan or another Royal Enfield model, protecting the motorcycle with suitable insurance is an important part of responsible ownership.
A bike can be exposed to accidents, theft, fire, natural calamities and third-party liabilities. While third-party motor insurance is mandatory for vehicles used on public roads in India, it generally does not cover damage to your own motorcycle. A comprehensive policy can provide broader protection by combining third-party liability coverage with own-damage protection against specified risks.
This Royal Enfield bike insurance guide explains the coverage options, important policy features, add-ons, exclusions and factors to consider before purchasing or renewing insurance.
What Is Royal Enfield Bike Insurance?
Royal Enfield bike insurance is a motor insurance policy designed to provide financial protection for your insured Royal Enfield motorcycle and, depending on the policy, third-party liabilities.
The two primary types of coverage are:
Third-Party Bike Insurance
Third-party insurance provides protection against eligible legal liabilities arising from injury, death or property damage caused to a third party by the insured motorcycle, subject to applicable terms and regulations.
This cover is mandatory for vehicles used on public roads in India.
Comprehensive Bike Insurance
Comprehensive insurance generally combines third-party liability protection with own-damage coverage against specified events.
Depending on the policy, own-damage protection may cover events such as:
- Accidents
- Theft
- Fire
- Natural calamities
- Certain man-made events
- Other covered external risks
The exact coverage depends on the policy wording, exclusions and applicable conditions.
Why Is Insurance Important for a Royal Enfield?
Royal Enfield motorcycles are available in different engine capacities and variants, and the cost of repairs can vary depending on the model and parts involved.
Insurance can help reduce the financial impact of covered incidents.
For example, an accident could result in damage to the motorcycle's body panels, lights, suspension, engine components or other parts. Similarly, theft could result in a substantial financial loss.
A suitable insurance policy can provide financial support for covered losses while also helping the owner fulfil mandatory third-party insurance requirements.
What Does Comprehensive Royal Enfield Bike Insurance Cover?
The exact inclusions vary by insurer and policy, but comprehensive insurance generally provides two broad areas of protection.
Own-Damage Protection
Own-damage coverage can protect your Royal Enfield against specified risks such as:
- Accidental damage
- Theft
- Fire
- Natural calamities
- Certain man-made events
The claim amount is determined according to the policy terms, applicable depreciation, deductibles, IDV and other conditions.
Third-Party Liability
If your motorcycle causes covered injury, death or property damage to another person, the third-party section can provide protection for eligible liabilities according to applicable laws and policy terms.
This makes comprehensive insurance broader than a basic third-party policy.
Understanding IDV for Royal Enfield Insurance
Insured Declared Value (IDV) is an important part of a bike insurance policy. It generally represents the approximate insured value of the motorcycle for certain claims, particularly theft or total loss.
The IDV generally changes as the motorcycle ages.
When buying Royal Enfield bike insurance, avoid choosing an unusually low IDV simply to reduce the premium. A lower IDV can affect the potential claim amount in applicable total-loss or theft situations.
At the same time, an unnecessarily high IDV may increase the premium. Review the available IDV and select an appropriate value according to the policy terms.
Add-On Covers for Royal Enfield Bikes
Comprehensive insurance can often be customised with optional add-ons. Availability and eligibility depend on the insurer, vehicle and policy.
Some commonly available add-ons include:
Zero Depreciation Cover
This cover may reduce applicable depreciation deductions on eligible parts during an admissible claim, subject to policy conditions.
It can be useful for eligible newer motorcycles where repair costs may be significant.
Roadside Assistance
Roadside assistance may provide help in certain situations such as breakdowns, flat tyres or other eligible roadside emergencies, depending on the policy.
This can be particularly useful for riders who frequently take long-distance trips.
Engine Protection Cover
Engine protection may cover certain engine-related losses resulting from specified situations, subject to terms and exclusions.
Consumables Cover
Consumables cover may help cover eligible consumable items used during an insured repair, depending on the policy.
Return to Invoice Cover
Where available and applicable, this add-on may provide additional protection for certain total-loss or theft situations, subject to eligibility and policy conditions.
Add-ons increase the overall premium, so select only those that match your riding habits and requirements.
Factors Affecting Royal Enfield Bike Insurance Premium
The premium can vary based on several factors.
Bike Model and Variant
Different Royal Enfield models and variants can have different values and risk profiles, which may influence the premium.
Age of the Motorcycle
The age of the bike can affect its IDV and, consequently, the premium.
Registration Location
The location where the motorcycle is registered can influence insurance pricing because risk levels can vary between areas.
Coverage Selected
Comprehensive insurance generally costs more than third-party-only coverage because it offers broader protection.
Add-Ons
Optional covers increase the premium depending on the selected benefits.
Claim History
An eligible No Claim Bonus can affect the premium during renewal according to applicable terms.
Deductibles
The deductible selected for the policy can influence the premium and your contribution towards eligible claims.
How to Choose the Right Royal Enfield Bike Insurance
Choosing a policy requires more than comparing prices.
Compare Similar Policies
When comparing quotes, make sure the policies offer comparable coverage. Check the IDV, add-ons and deductibles before deciding.
Review the Exclusions
Exclusions explain circumstances where coverage may not apply. Read them carefully to understand the limitations of the policy.
Check Claim Services
Consider the insurer's claim reporting process, customer support and available repair-related services.
Select Appropriate Add-Ons
Choose additional covers based on your motorcycle's age, usage and riding conditions rather than adding unnecessary benefits.
Verify Policy Details
Before completing your purchase or renewal, check your registration number, model, variant, personal details and other information for accuracy.
Common Exclusions to Understand
Comprehensive insurance does not cover every type of loss.
Depending on the policy, common exclusions may include:
- Normal wear and tear
- Certain mechanical or electrical breakdowns
- Damage caused by excluded circumstances
- Riding without a valid driving licence
- Unauthorised or prohibited use
- Certain consequential losses
- Other exclusions specifically listed in the policy
The policy document should always be reviewed for the exact exclusions applicable to your coverage.
How to Buy Royal Enfield Bike Insurance Online
The online purchase process is generally straightforward.
Step 1: Enter Vehicle Details
Provide the required registration and motorcycle information.
Step 2: Review Available Plans
Compare suitable third-party or comprehensive options based on your requirements.
Step 3: Select Coverage
Choose the required policy type, IDV and applicable add-ons.
Step 4: Check the Premium
Review the final premium after selecting your coverage and deductible options.
Step 5: Verify Information
Check all vehicle and policyholder details before proceeding.
Step 6: Complete Payment
Make the applicable payment through the available online method.
Step 7: Save the Policy Document
Once the policy is issued, save a digital copy for future reference.
Tips for Royal Enfield Bike Insurance Renewal
Renewing insurance on time helps avoid an unintended coverage gap.
Before renewal:
- Check your current policy's expiry date
- Review your existing coverage
- Verify your NCB
- Reassess add-ons
- Check the IDV
- Compare available options
- Confirm your vehicle details
Do not renew automatically without checking whether the coverage still matches your current needs.
Common Mistakes to Avoid
Royal Enfield owners should avoid these common insurance mistakes:
- Choosing the cheapest policy without comparing coverage
- Ignoring exclusions
- Selecting an unsuitable IDV
- Buying unnecessary add-ons
- Providing incorrect information
- Forgetting the renewal date
- Not understanding deductibles
- Assuming comprehensive insurance covers every type of damage
- Delaying claim intimation after an accident
Understanding the policy before purchasing it can help avoid many unnecessary complications.
Conclusion
A suitable Royal Enfield bike insurance policy can provide valuable financial protection against covered risks while helping owners meet mandatory third-party insurance requirements. Comprehensive insurance can offer wider protection by covering third-party liabilities along with specified damage to your own motorcycle.
Before selecting a policy, consider the bike's model, age, IDV, usage, premium, deductibles, exclusions, add-ons and claim services. The right policy is not necessarily the cheapest one; it is the one that provides suitable protection for your motorcycle and financial requirements.
Square Insurance can help customers explore suitable insurance options and manage their insurance requirements conveniently. By comparing policies carefully and understanding the terms before purchasing or renewing coverage, Royal Enfield owners can make a more informed insurance decision.
FAQs
Q1. Is Royal Enfield bike insurance mandatory in India?
Yes. Third-party motor insurance is mandatory for vehicles used on public roads in India. Royal Enfield owners must maintain valid insurance as required under applicable regulations.
Q2. What does comprehensive Royal Enfield bike insurance cover?
It generally combines third-party liability protection with own-damage coverage against specified risks such as accidents, theft, fire and natural calamities, subject to policy terms and exclusions.
Q3. Does Royal Enfield insurance cover theft?
Comprehensive insurance generally provides coverage for theft of the insured motorcycle, subject to policy conditions, exclusions and applicable claim requirements.
Q4. What is IDV in Royal Enfield bike insurance?
IDV stands for Insured Declared Value. It generally represents the approximate insured value of the motorcycle for certain claims, particularly theft or total loss, subject to the policy terms.
Q5. Which add-ons are useful for Royal Enfield bikes?
Depending on eligibility, riders may consider Zero Depreciation, Roadside Assistance, Engine Protection, Consumables and Return to Invoice covers. The right choice depends on the bike and riding requirements.
Q6. Can I buy Royal Enfield bike insurance online?
Yes. Royal Enfield bike insurance can generally be purchased online by providing the required vehicle details, selecting suitable coverage and completing the applicable payment process.
Q7. How can I reduce my Royal Enfield insurance premium?
You can compare policies, maintain an eligible No Claim Bonus, select appropriate deductibles and avoid unnecessary add-ons. However, reducing coverage solely to obtain a lower premium may not always be suitable.