Can Australian Steel Forge a Green Future Amid Global Pressures?
Australia's steel market is set to grow from USD 20.1B to USD 26.6B by 2034. Explore green steel investment, infrastructure demand, and opportunities.
 Ranjeet Sharma
Introduction
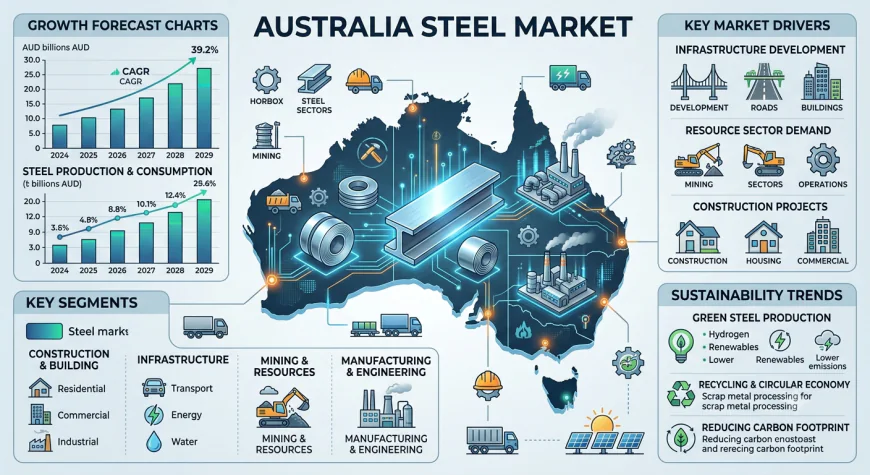
Australian steel executives are confronting a defining moment. The nation's construction cranes continue to rise, infrastructure pipelines stretch to the horizon, and renewable energy projects demand unprecedented volumes of structural materials. Yet this apparent strength masks deep vulnerabilities. Low-cost imports are pressuring domestic fabricators, global price volatility is complicating procurement, and acute labour shortages are threatening project timelines. Against this backdrop, a more fundamental transformation is underway: the pivot toward low-emission steelmaking. The Australia steel market sits at the centre of this industrial reinvention. Valued at USD 20.1 billion in 2025, the market is projected to reach USD 26.6 billion by 2034, growing at a compound annual growth rate of 3.03 per cent from 2026 to 2034. These figures reflect an industry balancing immediate demand pressures with long-term strategic repositioning.
What's Driving Growth of Australia's Steel Market?
Large-scale infrastructure investment is anchoring domestic demand. Government expenditure on transportation networks, urban development, and public infrastructure is reinforcing consistent steel consumption across the country. Major programs like Sydney Metro West, which awarded approximately $7.7 billion in contracts for stations, track systems, and operations, illustrate the scale of steel-intensive projects underway.
The renewable energy transition is creating new demand categories. Wind farms, solar installations, and electricity transmission networks require durable structural materials capable of supporting long-term energy production. Steel is indispensable in wind turbine towers, transmission structures, and supporting frameworks. The Australian Government's $500 million investment through the Future Made in Australia Innovation Fund, delivered through ARENA, is strengthening local production of materials required for renewable energy infrastructure.
Domestic manufacturing initiatives are building strategic resilience. Policymakers are increasingly introducing financial support programs to secure the long-term viability of local steel production. The A$1 billion Green Iron Fund, including an initial A$500 million allocation aimed at stabilising the Whyalla steelworks in South Australia, exemplifies this commitment to domestic supply chain security.
Research collaboration is accelerating technological advancement. Partnerships between steel manufacturers and research institutions are driving innovation in production methods and sustainable manufacturing. Tata Steel and Monash University's agreement to establish a Centre for Innovation on Environment and Intelligent Manufacturing supports research into decarbonisation, resource recovery, and advanced manufacturing systems.
Three Trends Reshaping the Industry
Low-carbon steelmaking is moving from ambition to commercial reality.
The industry is undergoing a fundamental transition toward low-emission production as companies invest in cleaner technologies and energy-efficient processes. Greensteel Australia partnered with Danieli to develop a 600,000-ton-per-year rolling mill in New South Wales powered entirely by green hydrogen, incorporating a hydrogen-fuelled reheating furnace designed to eliminate fossil fuel use. The company has since announced plans to invest $1.6 billion in a new steel plant incorporating direct reduced iron units, electric arc furnaces, and advanced rolling mills.
Why it matters: Low-carbon production is becoming a competitive differentiator as customers and regulators demand verifiable emissions reductions.
Business implication: Producers must invest in hydrogen-based technologies and electric arc furnaces or face exclusion from premium supply chains.
Future impact: Australia's steel industry could transition from a high-emission commodity producer to a global leader in green iron and steel exports.
Government policy is strategically repositioning domestic steel supply chains.
Policymakers are introducing financial support programs to secure local steel production while ensuring Australian iron ore remains competitive in a global market transitioning toward lower-emission manufacturing. The A$1 billion Green Iron Fund and the $500 million Future Made in Australia Innovation Fund represent coordinated efforts to support domestic processing capacity and promote green iron as a strategic industrial resource. The Western Australian government has launched an Expression of Interest to encourage the use of locally produced green steel in major public infrastructure projects.
Why it matters: Policy support provides long-term visibility for capital-intensive investments in green steel technology.
Business implication: Producers must align investment strategies with government funding priorities to access co-investment opportunities.
Future impact: Australia could capture value from its iron ore resources domestically rather than exporting raw materials for processing offshore.
Technological modernisation is transforming fabrication and processing efficiency.
Steel producers are adopting advanced fabrication technologies, automation systems, and digital production management tools to enhance product quality and streamline manufacturing. Modern processing methods enable production of specialised steel grades designed to meet evolving needs in construction, automotive, and industrial sectors. Metal Logic's acquisition of a 1,000-hectare site in Western Australia's Pilbara region for its modular clean steel smelting technology aims to establish an initial one-million-ton-per-year facility capable of producing lower-emission steel while processing a wide range of iron ore grades.
Why it matters: Technological modernisation is essential for maintaining competitiveness against lower-cost international producers.
Business implication: Companies must invest in automation and digital systems to improve productivity and product quality.
Future impact: Advanced manufacturing will enable Australia to compete on value rather than volume in global steel markets.
What the Market Numbers Actually Tell Us
A market expanding from USD 20.1 billion to USD 26.6 billion over nine years suggests significantly greater commercial activity across domestic producers, fabricators, distributors, and international suppliers. The 3.03 per cent compound annual growth rate signals steady, reliable expansion driven by construction activity and infrastructure investment. Flat steel dominates with a 52.4 per cent share in 2025, driven by broad applications across construction, automotive manufacturing, and renewable energy infrastructure. Structural steel leads the product segment at 34.2 per cent, anchored by large-scale building and civil infrastructure projects. Building and construction represents the largest application segment at 42.3 per cent, reflecting Australia's ongoing urban development. New South Wales and the Australian Capital Territory dominate regionally with a 32.1 per cent share, owing to Sydney's infrastructure expansion and the concentration of industrial activity in the region. For investors, the trajectory indicates that steel remains a cornerstone of Australia's industrial economy, with growth increasingly driven by value-added and sustainable production rather than commodity volume.
Where New Opportunities Are Emerging
The most significant opportunities lie at the intersection of decarbonisation and domestic value capture. The Green Iron Fund and Future Made in Australia Innovation Fund are catalysing investment in low-carbon production technologies that could reposition Australia as a global leader in green steel. Metal Logic's Pilbara smelting project aims to process a wide range of iron ore grades while producing lower-emission steel near major mining regions. The Western Australian government's initiative to use green steel in public infrastructure projects—railways, roads, hospitals, and energy infrastructure—creates guaranteed demand for early movers. Companies that can navigate the regulatory landscape, secure government co-investment, and deliver verifiable emissions reductions are well-positioned to capture premium pricing in domestic and export markets. Key players including BlueScope Steel, InfraBuild, LIBERTY Steel Group, and Greensteel Australia are advancing dual strategies of maximising existing capacity while investing in the technologies that will define the industry's next decade.