Loan Against MF Interest Rate: A Practical Guide to Borrowing Against Mutual Funds
The loan against mutual funds interest rate is an important part of evaluating a secured borrowing facility, but it should always be considered alongside LTV, fees, repayment terms and the conditions attached to pledged investments. Interest rates vary between lenders and can change over time. Therefore, borrowers should verify current rates and charges directly with the relevant financial institution and understand the complete terms before applying.
 Fintrac Ventures
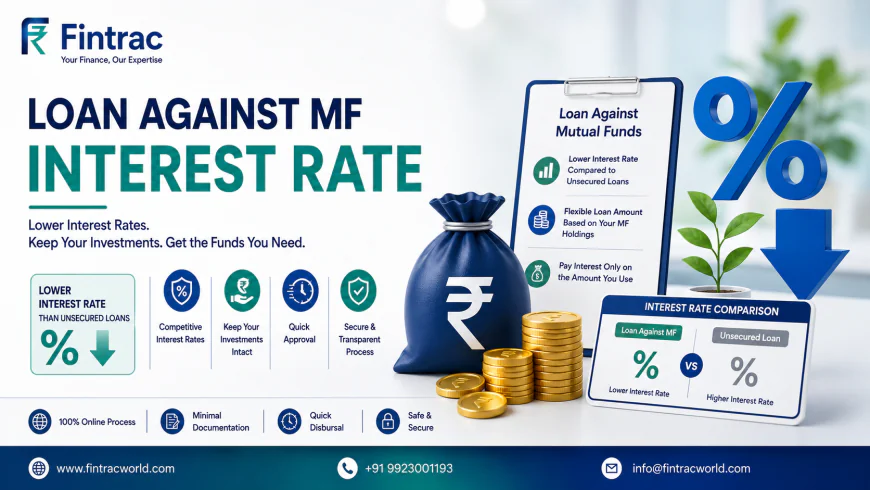
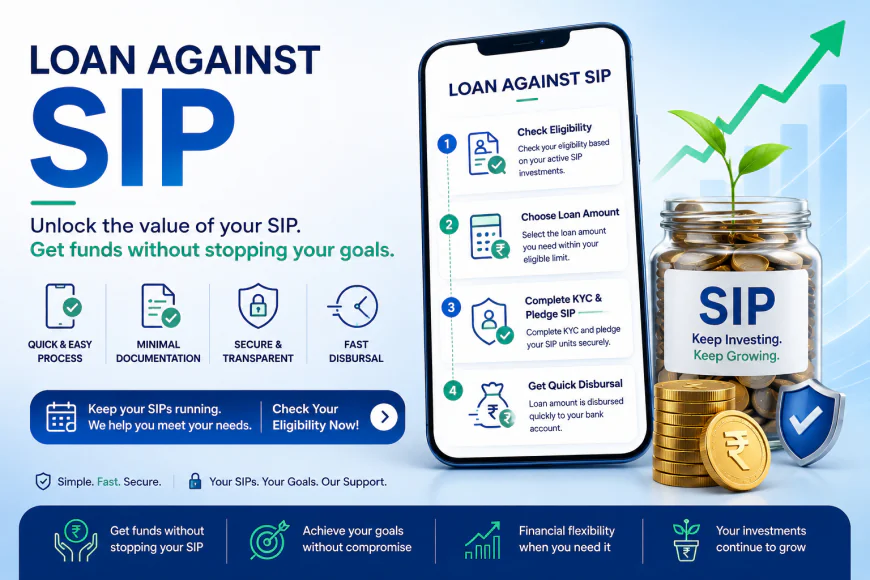
Mutual funds are generally considered a long-term investment option, but there may be situations when an investor needs access to money without immediately selling their investments. A loan against mutual funds can provide an alternative by allowing eligible investors to use their mutual fund holdings as security for borrowing. One of the first things borrowers usually want to understand is the loan against mf interest rate. The interest charged can affect the overall cost of borrowing, so it is important to understand how the rate is determined, what other charges may apply, and what repayment terms should be checked before applying.
What Is a Loan Against Mutual Funds?
A loan against mutual funds is a secured borrowing facility where eligible mutual fund units are offered as security to the lender. Instead of redeeming the investment to arrange funds, the investor may be able to borrow against the value of the eligible holdings.
The amount available depends on several factors, including the type of mutual fund, the value of the units and the lender's applicable loan-to-value requirements.During the loan period, the mutual fund investment generally remains linked to the lending arrangement until the outstanding dues are settled according to the agreed terms.
Understanding Loan Against MF Interest Rate
The loan against mf interest rate is an important part of the borrowing cost. Unlike a single rate that applies to every borrower, the applicable rate can vary depending on the lender, loan amount, repayment structure, applicant profile and other lending conditions.
Before proceeding, borrowers should look beyond the headline interest rate and understand the complete cost of the facility. Processing charges, applicable taxes, documentation charges or other fees may affect the total amount payable. A borrower should therefore compare the applicable rate and terms rather than choosing a facility based only on the advertised starting rate.
Why Consider a Loan Instead of Redeeming Investments?
Selling mutual fund units to meet a short-term financial requirement may change the investor's existing investment position. A loan against eligible holdings can offer another approach, subject to lender approval and applicable terms.
However, borrowing also creates a repayment obligation. The decision should therefore be based on the purpose of borrowing, expected repayment capacity and total cost rather than convenience alone. At Fintracworld, borrowers can explore information related to financing options and understand important aspects of borrowing against investments before making an informed decision.
What Can Affect the Interest Rate?
Several factors may influence the rate offered on a loan against mutual funds:
Type of Mutual Fund
Different categories of mutual funds may have different lending conditions. The lender may consider the nature and liquidity of the underlying investment while determining the eligible loan amount and applicable terms.
Loan Amount
The amount being borrowed can also influence the terms offered. The lender may have different conditions for different loan sizes.
Applicant Profile
The borrower's financial profile and relationship with the lender may be considered as part of the lending process. Eligibility criteria can vary between providers.
Repayment Terms
The structure and duration of the loan can affect the overall borrowing cost. Borrowers should carefully review the repayment schedule before accepting an offer.
Lender's Policies
Interest rates and lending conditions differ among financial institutions. Rates can also change over time, so applicants should verify the current terms directly with the concerned lender.
How Does the Process Work?
The process generally begins with an application to a lender offering loans against eligible mutual fund investments. The lender checks the applicant's details and verifies the mutual fund holdings. Once the investment is accepted as security and the application meets the lender's requirements, the eligible loan amount and applicable terms are communicated to the borrower.
After completion of the required formalities, the approved amount can be made available according to the lender's process. The borrower then repays the loan and applicable interest according to the agreed schedule. Once the outstanding obligations are cleared, the security arrangement can be released as per the applicable terms.
What Should You Check Before Applying?
Before choosing a loan facility, review the following points carefully:
-
Applicable interest rate
-
Processing and other applicable charges
-
Eligible mutual fund schemes
-
Maximum loan amount
-
Loan-to-value requirement
-
Repayment schedule
-
Prepayment or foreclosure conditions
-
Consequences of delayed repayment
-
Conditions related to the pledged mutual fund units
Understanding these points can help borrowers estimate the actual cost and avoid surprises later.
Can You Apply for a Loan Against Mutual Funds Online?
Many lenders provide digital application facilities, making it possible to start the process online. An applicant may need to provide personal information, complete required verification and provide details of eligible mutual fund investments.
When considering loan against mutual funds online, borrowers should use the official website or application of the concerned financial institution and carefully review the terms before submitting an application. Online convenience should not replace proper evaluation. The interest rate, charges, eligibility requirements and repayment conditions should all be checked before accepting the facility.
Conclusion
A loan against mutual funds can provide access to funds without requiring an immediate redemption of eligible investments. The loan against mf interest rate is one of the key factors to evaluate, but it should be considered together with processing fees, repayment conditions, eligibility requirements and other applicable charges.
Borrowing against mutual fund investments can be useful when an investor needs funds and has eligible holdings that can be offered as security. However, understanding the interest rate and complete loan terms is essential before making a decision. Rather than focusing only on the advertised rate, borrowers should review the full cost, repayment schedule and lender-specific conditions. For information and guidance related to financial borrowing options, Fintracworld can be explored as a resource while comparing available options and understanding the process.
Frequently Asked Questions
1. What is loan against mf interest rate?
It is the interest rate applicable to a loan secured against eligible mutual fund holdings. The actual rate can vary according to the lender, applicant profile, loan terms and other applicable conditions.
2. Does the interest rate remain the same for every borrower?
Not necessarily. Different lenders may offer different rates, and the applicable terms can depend on factors such as loan amount, applicant profile and lending policies.
3. Can I apply for a loan against mutual funds online?
Yes, some lenders provide online application facilities. Applicants should verify the lender's current process and review all applicable terms before proceeding.
4. Can all mutual funds be used as security?
Not necessarily. Lenders may specify which mutual fund categories or schemes are eligible for the facility. Eligibility should be confirmed with the concerned lender.
5. What happens if I do not repay the loan?
The consequences depend on the loan agreement and lender's terms. Since the mutual fund units serve as security, borrowers should understand the applicable default and security-related conditions before taking the loan.